A trading strategy can look excellent on one chart and disappointing on another—even when the rules are exactly the same. One of the biggest reasons is market session.
The forex market operates across global financial centres, so the same setup can encounter very different levels of liquidity, volatility, order flow and news activity depending on when it appears. A breakout strategy, for example, may struggle during a quiet Asian session but move much faster when London and New York are both active. This does not automatically mean the strategy is broken. It may mean the market conditions have changed.
For traders, especially those managing funded or prop firm accounts, understanding this difference matters because a strategy’s entry logic, stop distance, holding time and expected trade frequency can all interact with the session in which the trade occurs.
What Changes Between Market Sessions?
The market does not behave identically throughout the 24-hour trading day. As different financial centres open and close, the amount and type of participation changes.
- Liquidity: More active participants can make execution and price discovery different from quieter periods.
- Volatility: The average size and speed of price movements can change significantly.
- Order flow: Different regions and instruments can dominate activity at different times.
- News: Economic releases are concentrated around particular regional trading hours.
- Spreads: Lower liquidity can contribute to wider spreads, while active periods often have tighter spreads on major pairs.
- Market structure: A range, breakout, trend or reversal setup may behave differently when participation increases.
IG notes that liquidity and volatility vary by session and that overlaps between major centres can produce increased activity. It also points out that different currency pairs respond differently to different sessions.
Why the Same Strategy Can Produce Different Results
Consider a simple breakout system. The rules might be:
- Identify resistance.
- Wait for a candle close above resistance.
- Enter on confirmation.
- Place a stop below the breakout structure.
- Target a predefined risk-to-reward ratio.
The rules have not changed. But the environment has.
During a quieter period, price may break resistance by a small amount, fail to attract enough follow-through and return inside the range. During a more active session, the same technical break can attract substantially more participation and travel much farther.
That is why strategy rules and market conditions should be analysed separately. A strategy may have a valid edge only under a particular combination of volatility, liquidity and news conditions.
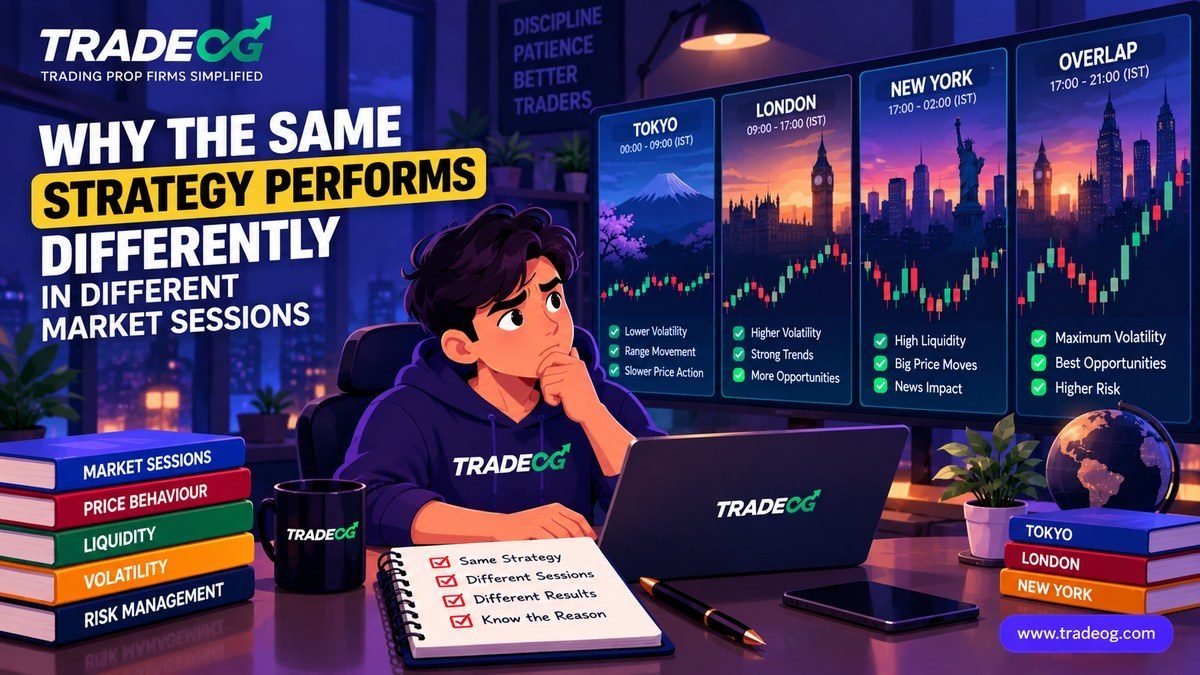
Asian or Tokyo Session: Why Breakouts Can Behave Differently
The Tokyo session is particularly relevant for JPY-related pairs, while AUD and NZD markets can also become more active during the Asia-Pacific period.
For a trader using a breakout system on EUR/USD, however, the same setup may not behave like it does during London or the London-New York overlap. If the market is relatively quiet and price remains inside a narrow range, a breakout signal may have less follow-through.
This can create a common problem: the trader sees a technically valid breakout but expects the same momentum that normally occurs later in the day.
A range or mean-reversion strategy may therefore have very different characteristics from a high-volatility breakout strategy during this period. The important point is not that one session is universally better; it is that the strategy must be tested against the conditions in which it is actually being used.
London Session: The Market Often Becomes More Active
When London opens, participation generally increases. IG describes the London session as a major liquidity centre and notes that volatility can increase around the London open.
This can materially change the behaviour of technical setups.
A resistance level that survived several hours of quieter trading can suddenly break. A tight Asian range can become the reference structure for a London breakout. At the same time, increased volatility can also create false breaks, fast stop-outs and larger candles.
That creates a trade-off for strategy design:
- Breakout systems may encounter more movement.
- Stops based on very small ranges may be hit more frequently.
- Trend-following systems may receive stronger momentum.
- Mean-reversion systems may face greater risk when a genuine directional move begins.
London-New York Overlap: Why Strategy Behaviour Can Change Again
The London-New York overlap is one of the most active periods in the FX market. Both major financial centres are operating at the same time, and US economic releases frequently occur during the New York portion of the trading day. IG describes the overlap as a period of particularly high liquidity and activity.
This matters because a strategy calibrated during a quiet period can behave very differently when volatility expands.
For example, suppose a strategy normally uses a 10-pip stop. If the market’s short-term volatility rises sharply, that stop may represent a much smaller amount of normal price noise than it did during a quieter session. The strategy can therefore experience more stop-outs even though its directional idea is not necessarily wrong.
For gold and other highly reactive instruments, the effect can be even more noticeable around major US economic releases. A technical setup that appears clean before a release can become a completely different trade once liquidity and volatility change.
News Is a Major Reason for Session Differences
Market session and economic calendar are closely connected. US CPI, NFP, FOMC decisions and other major releases can create abrupt changes in price behaviour during the New York session.
News can change several variables simultaneously:
- Volatility can expand rapidly.
- Spreads can widen around major releases.
- Slippage risk can increase.
- Technical levels can be broken quickly.
- Previously low-volatility ranges can become irrelevant.
IG also notes that volatility and news can influence forex spreads, and that spreads can widen around major economic releases.
This is one reason backtesting a strategy without recording the economic environment can produce misleading conclusions.
Same Strategy, Different Stop-Loss Behaviour
Stop placement is another reason session performance can look completely different.
Imagine a strategy that places a stop just beyond the most recent swing low. During a quiet session, that swing may be relatively close to the entry. During a volatile session, the structure may be much wider.
If the trader uses the same fixed lot size in both situations, the actual monetary risk can be very different.
This is why position sizing should be connected to the distance between entry and stop rather than chosen independently. A strategy that changes stop distance with market structure should generally be paired with position sizing rules that account for that distance.
Why a Backtest Can Give the Wrong Impression
One of the most overlooked issues in strategy testing is mixing all trading hours together.
Suppose a strategy produces 100 trades:
- 30 trades during Asia
- 40 trades during London
- 30 trades during New York
If the overall win rate is 55%, that number does not tell you whether the strategy performs consistently across sessions.
You could discover that the results are heavily concentrated in one session while another session contributes most of the losses. The combined statistic hides that difference.
A more useful analysis is to record results by session and compare:
- Win rate
- Average reward-to-risk
- Average trade duration
- Maximum losing streak
- Average favourable excursion
- Average adverse excursion
- Spread at entry
- Time of day
- News conditions
This lets you determine whether the strategy is genuinely session-sensitive instead of simply reacting to a few unusual trades.
How Prop Firm Traders Should Think About Session Risk
For a funded account, the question is not only whether a setup can make money. The trader also has to consider daily loss limits, maximum drawdown and the consequences of a short sequence of losses.
A high-volatility session can produce larger winners, but it can also produce faster losses. A strategy that looks attractive on a percentage-return chart may have a completely different risk profile when applied during a volatile news window.
This is particularly important when traders increase position size because they expect a session to move more.
Higher expected movement does not justify ignoring account-level risk. Position size should still be determined from the predefined amount of capital the trader is willing to risk and the stop distance.
For related risk-management concepts, see our guides on why small losses become large losses in funded accounts and why traders move their stop loss after entering a trade.
Should You Change the Strategy for Every Session?
Not necessarily.
Changing rules every time market conditions change can lead to overfitting. Instead, separate the strategy into two layers:
- Core rules: the conditions that define the setup and entry.
- Session filter: the market conditions under which the setup is allowed to trade.
For example, a trader may decide through historical testing that a particular breakout model is only evaluated during specific liquid hours. Another strategy may be designed specifically for range conditions.
The key is that the restriction should come from testing and a predefined trading plan—not from changing rules after seeing a losing trade.
How to Test Your Strategy Across Sessions
A practical session-based test can be simple.
Step 1: Keep the strategy rules fixed
Do not change the entry, stop or target just because a trade occurred in a different session.
Step 2: Add a session label
Record whether every trade occurred during Asia, London, New York or an overlap period.
Step 3: Record market conditions
Note whether the market was trending, ranging, highly volatile or affected by scheduled news.
Step 4: Compare the distributions
Do not focus only on total profit. Look at win rate, expectancy, drawdown, losing streaks and trade duration.
Step 5: Test a session filter separately
If one session consistently behaves differently, test whether excluding that period improves the strategy without creating excessive curve-fitting.
What Indian Traders Should Remember About Session Times
Indian traders should be careful with fixed session tables because London and New York daylight-saving changes can shift their relationship with Indian Standard Time.
Instead of memorising one permanent clock schedule, use the relevant session’s current local time and confirm the conversion for the date being traded.
This is especially important for traders who build automated alerts around London open, New York open or major US economic releases.
The Main Lesson
The same strategy does not operate in a vacuum. Its results depend on the interaction between the rules and the market environment in which those rules are executed.
Tokyo, London and New York can have different liquidity profiles, volatility characteristics, dominant currency flows and scheduled news. Overlaps can further change the speed and structure of price movement. That means a strategy can legitimately produce different results at different times of day without the underlying rules changing.
For serious traders, the solution is not to chase the session that recently produced the biggest move. The better analytical approach is to measure strategy performance by session, understand the market conditions behind the results and define any session filters before trading.
Once you know when your strategy works, when it struggles and why, your performance data becomes much more useful than a single overall win-rate number.
Sources
- IG — UK Forex Market Hours and Trading Sessions
- IG Academy — Trading the London Session
- IG Academy — Trading the New York Session
- IG Academy — Navigating the Forex Spread
Frequently Asked Questions
Why does the same strategy perform differently in different sessions?
Because liquidity, volatility, order flow, spreads and scheduled news can change throughout the trading day. The entry rules may be identical while the market environment is not.
Is the London-New York overlap always better for every strategy?
No. Different strategies are designed for different conditions. A high-volatility breakout model and a range-trading model can react very differently to the same session.
Should Indian traders use different strategies for different sessions?
Not automatically. First test the same rules separately by session. If the data shows a meaningful and repeatable difference, a predefined session filter can be evaluated without changing the core strategy after individual losses.