Receiving a foreign-currency payment does not always mean the money will arrive at your bank account in the same currency in which it was sent. A USD payment, for example, can be converted into INR before the funds are finally credited to an Indian bank account.
This can happen because the payment route, the beneficiary account currency, the receiving bank’s processing rules, an intermediary bank or the payment provider may determine where the foreign-exchange conversion takes place.
For traders receiving prop firm payouts, broker withdrawals or other international payments, understanding this process is important because the conversion point can affect the exchange rate, fees, timing and the amount ultimately credited.
Why Can a Foreign Currency Payment Be Converted Before It Reaches Your Bank?
The simplest reason is that the destination account may not be able to receive or hold the currency being sent.
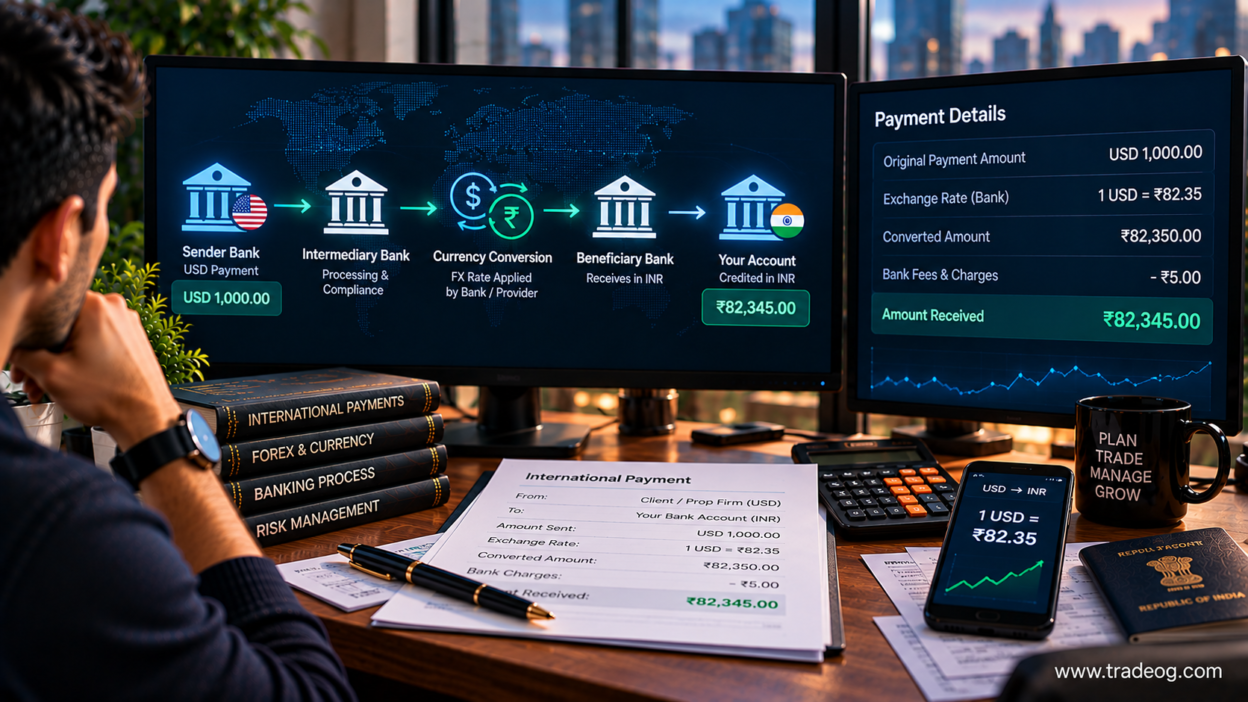
For example, imagine a prop firm sends USD 1,000 to an Indian bank account that is intended to be maintained in INR. The payment does not necessarily have to arrive as USD 1,000 in a USD balance first. Depending on the payment arrangement, a bank or intermediary can convert the payment into INR during the processing chain and then deliver the converted amount to the beneficiary bank or customer account.
Swift’s Payments Market Practice Group specifically describes auto foreign currency conversion as the automatic or systematic conversion of a payment into another currency by a bank somewhere in the payment chain. Its guidance notes that receiving banks may convert incoming foreign currency when the recipient cannot receive or be paid in that currency, while sending banks or intermediary banks can also provide automatic conversion services. Swift’s Auto Foreign Currency Conversion white paper explains the practice in detail.
SWIFT Is the Messaging Network, Not Necessarily the Converter
One common misunderstanding is that SWIFT itself decides the exchange rate or converts every international payment.
That is not how the system works.
SWIFT provides messaging and payment infrastructure used by financial institutions. The actual foreign-exchange conversion can be performed by a bank or other financial institution participating in the payment chain.
The conversion can therefore happen:
- At the sending bank
- At an intermediary or correspondent bank
- At the receiving bank
- At a payment provider connected to the bank route
The exact location depends on the payment instructions, currencies involved, account capabilities, correspondent relationships and local market practices.
The Bank for International Settlements notes that cross-currency payments require FX conversion at some point and that, in correspondent-banking arrangements, conversion can be performed by one or more correspondent banks along the payment chain. It may occur at the first bank, the last bank or another institution in the chain.
Example: A $1,000 Payment to an INR Bank Account
Consider a simplified example:
| Stage | Illustrative Value |
|---|---|
| Original payment | USD 1,000 |
| FX conversion rate used | ₹82.35 per USD |
| Converted amount | ₹82,350 |
| Illustrative bank charge | – ₹5 |
| Final credited amount | ₹82,345 |
This is only an illustration. The exchange rate, fee and final amount can vary by bank, payment route, currency, transaction date and account arrangement.
The important point is that the trader may never see a USD 1,000 balance inside the Indian INR account. The conversion can occur before the final account credit.
Where Can the Currency Conversion Happen?
1. Conversion by the Sending Bank
The sending bank may convert the original currency before sending the payment onward.
For example, a payment provider may receive instructions to pay an Indian beneficiary in INR. Instead of sending USD through the entire route, the provider or its banking partner may convert USD into INR and initiate the downstream payment in INR.
This can simplify processing, but it means the exchange rate used earlier in the payment chain becomes important.
2. Conversion by an Intermediary Bank
An intermediary bank can sit between the sender and beneficiary banks. If the payment route requires a currency conversion, that intermediary may perform it.
This is more likely to matter when the payment involves currencies or banking relationships that do not have a direct settlement route.
TradeOG’s guide on how intermediary banks affect international trading payments explains why an international payment can pass through multiple institutions before reaching the beneficiary.
3. Conversion by the Receiving Bank
A receiving bank can convert an incoming foreign-currency payment when the beneficiary account is denominated in the local currency or when the account cannot accept and hold the incoming currency under the applicable arrangement.
This is one of the most intuitive examples for Indian traders: a USD payment reaches the banking system, but the final customer account is an INR account, so the bank processes the foreign currency into INR before crediting the account.
4. Conversion by a Payment Provider
Some trading platforms, payout providers and financial services do not operate exactly like a traditional direct bank-to-bank wire. They may use their own payment infrastructure or banking partners and convert the currency before sending the final local-currency payment.
In that situation, the exchange rate may be determined by the provider rather than the trader’s receiving bank.
Why Would a Bank Convert the Payment Automatically?
Automatic conversion can make international payments easier to process.
A bank may receive a foreign-currency transfer but know from the beneficiary account and local payment instructions that the customer is supposed to receive domestic currency. Converting the payment can allow the bank to complete the credit without requiring the customer to maintain a foreign-currency account.
Swift’s 2026 market-practice documentation describes this as a way to facilitate efficient processing and straight-through processing in situations where the receiving customer cannot receive or be paid in the original currency.
Does the Beneficiary Need a USD Account to Receive USD?
Not necessarily.
A bank account’s currency capability is important, but the exact result depends on the account type, bank, payment route and instructions.
A customer with an eligible multi-currency account may be able to receive and hold USD without immediate conversion. A standard INR account may instead be credited after the incoming foreign currency is converted.
Therefore, “the sender sent USD” does not automatically mean “the beneficiary will receive USD in a USD balance.”
How the Conversion Point Can Affect the Exchange Rate
The biggest practical issue for traders is not simply whether conversion occurs. It is which exchange rate is used.
Suppose the public market reference rate is ₹83.00 per USD. The bank or provider may apply a different customer conversion rate after considering its applicable spread, pricing model or charges.
For a USD 1,000 payment:
- At ₹83.00/USD: ₹83,000
- At ₹82.50/USD: ₹82,500
- At ₹82.00/USD: ₹82,000
A difference of ₹1 per USD produces a ₹1,000 difference on a USD 1,000 payment.
This is why comparing only the visible bank fee can be misleading. The exchange-rate difference can be economically larger than the explicit transaction charge.
Could the Payment Be Converted More Than Once?
In some payment structures, multiple currency conversions can occur, although this is not inevitable.
For example, a payment could move through an intermediary relationship involving USD and EUR before ultimately being converted into INR. Each additional conversion introduces another exchange-rate event and potentially another spread or cost.
BIS research on cross-border payments highlights that correspondent-banking chains can involve FX conversion along the payment chain, depending on how the settlement relationships are structured.
This is one reason less direct currency corridors can be more complicated than a straightforward USD-to-INR payment.
Why the Conversion Can Happen Before the Beneficiary Bank Sees the Money
The phrase “before reaching your bank” needs a little precision.
Your customer account is not necessarily the first place at which the payment reaches your banking institution. A bank may have a correspondent account or relationship through another institution. A payment can therefore be converted at an upstream bank and arrive at the beneficiary bank already denominated in the destination currency.
In other cases, the beneficiary bank receives the foreign-currency payment internally and converts it before posting the final customer credit.
So there are two different situations:
| Situation | What Happens |
|---|---|
| Conversion upstream | An intermediary or sending-side institution converts the payment before it reaches the beneficiary bank’s customer-processing stage. |
| Conversion at receiving bank | The beneficiary bank receives the foreign currency and converts it before crediting the customer’s INR account. |
The final bank statement may not make the upstream path obvious.
Why a Trader May See INR Even Though the Payout Was Sent in USD
This is common when the payout is destined for an INR-denominated account.
The prop firm may show:
USD 1,000 approved → USD 1,000 sent
But the Indian bank statement may show:
INR credit after FX conversion
That does not automatically indicate an error.
The payment can be correctly processed while the currency changes somewhere between the sender’s payment instruction and the final customer credit.
TradeOG’s related guide on why the amount received can differ from the payout amount covers the broader effect of intermediary fees, bank charges and currency conversion.
Can Currency Conversion Reduce the Final Trading Payout?
Yes, but it is useful to distinguish conversion loss from an explicit fee.
A bank may not display a line saying “FX loss.” Instead, the cost can be embedded in the exchange rate used to convert the payment.
For example, if a reference rate is ₹83.00 but the applicable customer rate is ₹82.50, the 50-paise difference on USD 1,000 equals ₹500.
That does not necessarily mean the bank charged an additional ₹500 transaction fee. It means the conversion produced a lower INR value than the reference rate.
For more detail, see Why Bank Conversion Charges Can Reduce Your Forex Trading Returns.
How to Find Out Where Your Payment Was Converted
If you want to understand what happened to a specific trading payout, work through the payment chain rather than guessing from the final bank statement.
Check 1: What currency did the sender actually instruct?
Ask the prop firm or payment provider whether the payment was instructed in USD, EUR, GBP or INR.
Check 2: What currency was expected at the beneficiary?
Confirm whether the payment instructions specified a foreign-currency account or a local-currency beneficiary account.
Check 3: Ask whether FX conversion was performed
The payment provider or bank may be able to confirm whether conversion occurred before the payment reached the beneficiary bank.
Check 4: Ask for the exchange rate used
This is more useful than asking only for the transaction fee. Request the actual conversion rate applied to the transaction.
Check 5: Compare the payment confirmation with your bank statement
Compare the original amount, currency, date, converted amount and any separately listed charges.
Check 6: Check whether an intermediary was involved
If the payment passed through a correspondent bank, the conversion may have happened there rather than at your final bank.
Does a SWIFT Payment Always Arrive in the Currency It Was Sent?
No.
The payment currency and the beneficiary’s credit currency can be different.
Swift’s payment guidance recognises that when a transfer is instructed in a currency different from the beneficiary’s account currency, local practices of the beneficiary country or bank can determine how the foreign exchange is handled.
This is an important distinction for traders: SWIFT transmission does not guarantee that the original currency will remain unchanged all the way to the customer account.
How This Affects Indian Traders Receiving Prop Firm Payouts
Indian traders should pay particular attention to four things:
- Original payout currency: Was the payout actually sent in USD or another currency?
- Beneficiary account currency: Is the receiving account denominated in INR or capable of holding the original currency?
- Conversion point: Did the sending provider, intermediary or Indian bank perform the FX conversion?
- Applied exchange rate: What rate was actually used to calculate the INR credit?
These questions help separate a normal currency conversion from a payment error or unexplained deduction.
Also remember that receiving an international payment can involve compliance or purpose-of-payment checks. Swift notes that local regulatory reporting and foreign-exchange controls can affect the final stage of a cross-border payment.
Foreign Currency Conversion vs Bank Charges
These costs should be analysed separately.
| Item | How It Can Affect You |
|---|---|
| FX conversion | Changes the foreign currency into INR or another destination currency. |
| FX spread | Can produce a less favourable rate than a market reference rate. |
| Transfer fee | Explicit charge for sending or processing the payment. |
| Intermediary fee | Charge associated with a correspondent or intermediary bank. |
| Receiving fee | Charge applied by the beneficiary bank. |
TradeOG’s recent guide on how SWIFT-related charges can reduce a trading payout explains the difference between payment fees, intermediary deductions, receiving-bank charges and FX costs.
How to Reduce Surprises on Future International Payouts
- Confirm the payout currency before requesting payment.
- Ask whether the provider converts the payment before sending it.
- Ask which institution performs the FX conversion.
- Ask for the applicable exchange rate where available.
- Confirm whether your bank account can receive and hold the original currency.
- Check your bank’s current inward-remittance and foreign-exchange terms.
- Keep the payment reference and payout confirmation.
- Compare the final INR credit with the expected value after realistic fees and FX costs.
Swift’s newer payment frameworks increasingly focus on upfront visibility into fees, FX rates and the amount expected to reach the beneficiary. Availability depends on participating institutions and payment corridors, but the direction of travel is toward greater transparency and predictability.
Frequently Asked Questions
Can a bank convert USD into INR before the payment reaches my account?
Yes. Depending on the payment route and account arrangement, a sending bank, intermediary or receiving bank can convert the foreign currency before the final customer credit.
Does SWIFT itself convert the money?
No. SWIFT provides messaging and payment infrastructure. A participating bank or financial institution performs the actual currency conversion.
Why did my prop firm send USD but my bank statement show INR?
If your destination account is INR-based, the payment may have been converted during the international payment process or by your receiving bank before the account was credited.
Can an intermediary bank convert the payment?
Yes. Depending on the correspondent-banking arrangement, an intermediary can perform an FX conversion as part of the payment route.
How can I know which exchange rate was used?
Ask the payment provider or receiving bank for the transaction’s applied FX rate. Then compare it with an appropriate market reference for the transaction date.
Can the conversion reduce my trading payout?
Yes. Even when there is no separate conversion fee, the exchange rate applied to the transaction can result in a lower INR value than a market reference rate.
Final Takeaway
A foreign-currency payment does not necessarily remain in its original currency until it reaches your customer account. Depending on the payment route, the sender, an intermediary bank, a payment provider or the receiving bank can convert the funds before the final credit.
For an Indian trader receiving a USD payout, the most important questions are therefore not just “How much was sent?” but also “In what currency was it sent, where was it converted, and what exchange rate was used?”
Once you identify the conversion point, you can distinguish the effect of the FX rate from transfer fees, intermediary deductions and receiving-bank charges. That makes it much easier to understand why the final INR amount may differ from the original foreign-currency payout.
Disclaimer: TradeOG provides educational and informational content only. Nothing in this article should be treated as financial, investment, legal, tax, banking or professional advice. Payment processing, fees, exchange rates, bank requirements and prop firm rules can vary by provider, country, bank, transaction and time. Always verify the applicable terms and transaction details with your prop firm, payment provider and bank before making financial decisions.