What Is Real Yield and Why Does It Matter for Gold Traders?
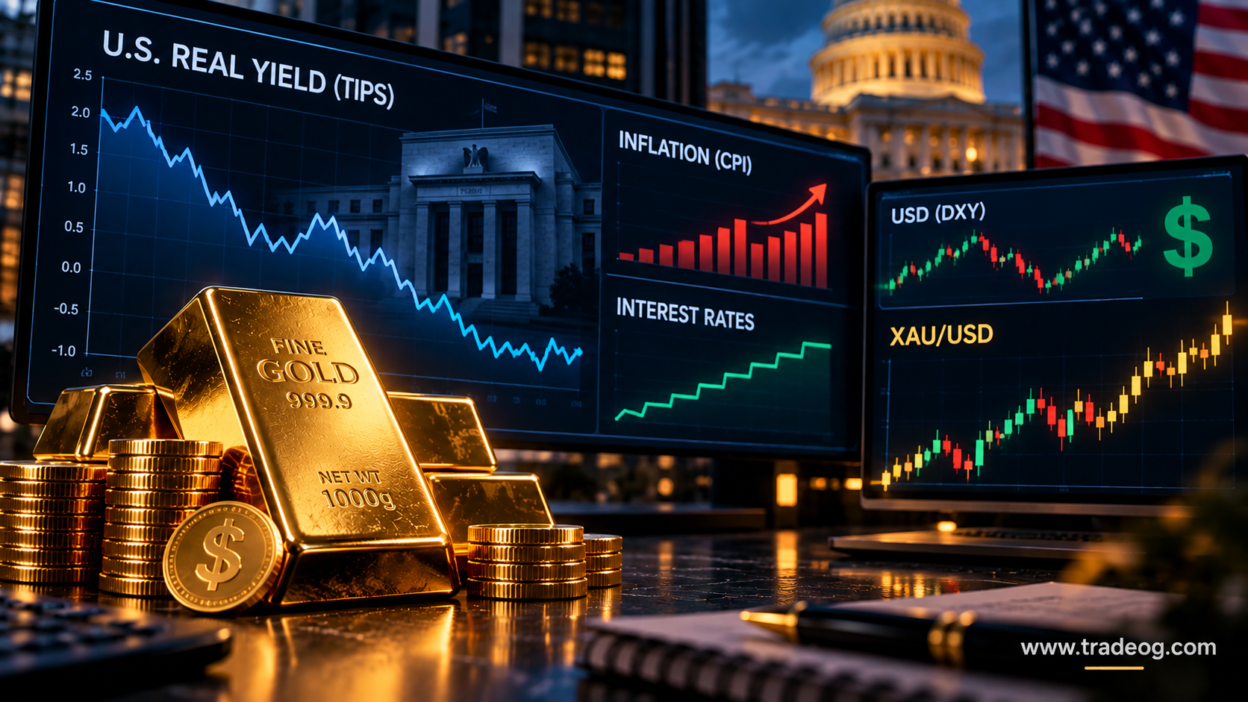
Gold traders often watch the Federal Reserve, CPI, NFP, Treasury yields and the U.S. dollar. But there is another market variable that can explain a large part of gold’s reaction to macroeconomic news: real yield.
If you trade XAU/USD, understanding real yields can help you interpret why gold sometimes falls when inflation rises, why gold can rally even when nominal Treasury yields are high, and why a Federal Reserve decision can affect gold through a chain of market reactions rather than through the interest rate alone.
The key idea is simple:
Real yield measures the return investors expect to receive after accounting for inflation.
For gold traders, the most closely watched reference is often the U.S. real yield, particularly the yield on Treasury Inflation-Protected Securities, commonly called TIPS.
This guide explains what real yield means, how it differs from nominal yield, why it matters for gold, how to read TIPS yields, and how Indian XAU/USD traders can incorporate the concept into a practical trading framework.
What Is Real Yield?
A nominal bond yield is the interest rate or market yield quoted without directly adjusting it for inflation.
A real yield attempts to measure the return after inflation.
A simplified relationship is:
Real Yield ≈ Nominal Yield − Expected Inflation
For example, imagine a 10-year U.S. Treasury yield is 4.50% and expected inflation is approximately 2.50%.
The simplified real yield would be:
4.50% − 2.50% = 2.00%
This does not represent the exact market calculation for every situation, but it is a useful way to understand the relationship.
The market also has instruments designed specifically to provide a market-based measure of real yields. U.S. TIPS are inflation-protected securities whose principal and interest payments are linked to inflation.
Why Does Real Yield Matter for Gold?
Gold does not pay a coupon or dividend.
A Treasury security, in contrast, provides a yield.
When real yields become more attractive, investors have a stronger opportunity cost for holding an asset that does not generate conventional interest income.
That creates an important macro relationship:
Higher real yields → higher opportunity cost of holding gold → potential pressure on gold.
Lower real yields → lower opportunity cost of holding gold → potential support for gold.
Historically, this relationship has been important, although it is not a mechanical trading rule.
The World Gold Council identifies opportunity cost, including real rates and the U.S. dollar, as important drivers of gold performance. Its more recent research also emphasizes that gold can deviate from the traditional real-yield relationship because central-bank demand, Asian investment, geopolitical risk, positioning and other factors can become powerful enough to offset the impact of real rates.
This distinction is extremely important for traders.
Real yields matter.
But real yields do not control gold by themselves.
Nominal Yield vs Real Yield
Many traders make the mistake of watching only the U.S. 10-year Treasury yield.
That can provide useful information, but it does not tell the entire story.
Suppose the 10-year Treasury yield rises from 4.00% to 4.50%.
At the same time, expected inflation rises from 2.00% to 3.00%.
The simplified real yield changes from:
4.00% − 2.00% = 2.00%
to:
4.50% − 3.00% = 1.50%
Nominal yields increased, but the real yield decreased.
That can create a very different environment for gold than a situation where nominal yields rise because real yields are rising strongly.
This is one reason gold traders should avoid the simple rule:
“Yields up = gold down.”
The better question is:
“Why are yields rising, and what is happening to real yields?”
How TIPS Help Traders Read Real Yields
Treasury Inflation-Protected Securities are designed to provide inflation protection.
The market yield on TIPS is therefore commonly used as an observable measure of real interest rates.
The U.S. 10-year TIPS yield is particularly useful for macro traders because it provides a market-based signal about the real return available from inflation-protected U.S. government debt.
When the 10-year TIPS yield rises, the opportunity cost of holding gold can increase.
When it falls, the opportunity cost can decrease.
This is why traders often place the following markets on the same dashboard:
XAU/USD
U.S. 10-year Treasury yield
U.S. 10-year real yield
DXY
U.S. inflation expectations
The goal is not to find a perfect one-to-one correlation.
The goal is to understand the macro environment behind the gold move.
The Gold and Real Yield Relationship
A simplified framework looks like this:
Real yields rising + DXY rising = generally a tougher environment for gold.
Real yields falling + DXY falling = generally a more supportive environment for gold.
But there are mixed scenarios.
For example:
Real yields rising + DXY falling.
Or:
Real yields falling + DXY rising.
In those situations, gold can behave differently depending on which force is stronger and what investors are worried about.
This is why professional macro analysis is based on multiple variables rather than a single indicator.
Scenario 1: Real Yields Rise Sharply
Imagine U.S. inflation expectations remain stable while Treasury yields rise.
If the increase is primarily reflected in real yields, investors may receive a more attractive inflation-adjusted return from U.S. government securities.
The opportunity cost of holding gold increases.
Possible market reaction:
Real yields rise
→ U.S. fixed-income becomes more attractive
→ opportunity cost of gold increases
→ gold faces potential selling pressure.
If DXY also strengthens, the pressure on XAU/USD can become stronger.
Scenario 2: Real Yields Fall
Now imagine Treasury yields fall while inflation expectations remain relatively stable.
Real yields decline.
The opportunity cost of holding gold decreases.
Possible reaction:
Real yields fall
→ relative attractiveness of non-yielding gold improves
→ gold can receive support.
If the U.S. dollar also weakens, the environment can become even more supportive for XAU/USD.
Scenario 3: Inflation Rises Faster Than Nominal Yields
This is a very important situation.
Suppose nominal Treasury yields rise from 4.00% to 4.40%.
But inflation expectations rise from 2.00% to 3.00%.
The simplified real yield falls from 2.00% to 1.40%.
Gold may respond positively even though nominal yields are higher.
This is why a trader who watches only the headline Treasury yield can misunderstand the gold reaction.
Scenario 4: Fed Turns More Hawkish
Suppose the Federal Reserve signals that interest rates may remain high for longer.
Markets may respond by pushing nominal yields higher.
If inflation expectations do not rise enough to offset the move, real yields can also increase.
That combination can create pressure on gold.
The macro chain becomes:
Hawkish Fed
→ higher future-rate expectations
→ higher real yields
→ stronger opportunity cost
→ stronger USD in many cases
→ potential XAU/USD pressure.
However, if the market interprets the policy as damaging to economic growth or financial stability, safe-haven demand can partially or completely offset the traditional real-yield effect.
Why Gold Can Rise Even When Real Yields Are High
This is one of the most important exceptions to understand.
If the relationship were perfect, gold would fall every time real yields increased.
That does not happen.
Gold can rise despite elevated real yields because gold has multiple sources of demand.
Central banks may continue accumulating gold.
Asian investors may increase physical or investment demand.
Geopolitical risk can increase safe-haven demand.
Concerns about fiscal sustainability can change investor preferences.
Currency diversification can support gold.
ETF flows and speculative positioning can also alter the short-term reaction.
The World Gold Council has highlighted that gold has continued to perform in periods when real rates were historically restrictive, with central-bank buying and Asian demand helping offset the traditional headwind from real yields.
Therefore, real yield should be treated as a major macro input, not an automatic buy-or-sell signal.
Real Yield and the U.S. Dollar
Gold is usually quoted in U.S. dollars, so the relationship between real yields and DXY is particularly important for XAU/USD traders.
A stronger dollar can make dollar-priced gold more expensive for buyers using other currencies.
At the same time, rising U.S. real yields can increase the relative attractiveness of dollar-denominated assets.
This creates a common macro combination:
Higher real yields + stronger DXY = potential bearish pressure on XAU/USD.
The opposite combination can be supportive:
Lower real yields + weaker DXY = potential bullish pressure on XAU/USD.
But again, markets can diverge.
If investors are aggressively seeking safe-haven assets, gold can rise even while the dollar is strong.
Real Yield and Inflation
Inflation is one of the reasons the relationship between nominal yields and gold can become complicated.
Consider three variables:
Nominal yield
Inflation expectations
Real yield
A rise in nominal yields does not automatically mean real yields are rising.
For example, if investors suddenly expect significantly higher inflation, nominal yields can increase because bond investors demand more compensation for inflation.
Gold can sometimes respond positively to this type of environment because inflation concerns can increase demand for assets perceived as stores of value.
But if the central bank responds aggressively and real yields rise sharply, the gold reaction can change.
This is why traders should ask:
Is inflation rising?
Are nominal yields rising?
Are inflation expectations rising?
Are real yields rising?
Is the central bank becoming more restrictive?
Is DXY strengthening?
The combination matters more than any single number.
How CPI Can Affect Gold Through Real Yields
CPI is one of the most important U.S. economic releases for gold traders.
But the market does not simply see a high CPI number and automatically buy gold.
Suppose CPI comes in hotter than expected.
The initial reaction could be:
Higher inflation
→ higher rate expectations
→ higher Treasury yields
→ stronger USD
→ higher real yields
→ gold falls.
But another scenario is possible.
If the market believes the inflation shock will eventually weaken the economy or reduce the real return available from bonds, the reaction can be different.
This is why gold traders should watch the bond market immediately after CPI.
The CPI number is the economic information.
The movement in yields and the dollar is the market interpretation.
Real Yield During NFP
The same principle applies to the U.S. jobs report.
A strong NFP number can increase expectations for restrictive Federal Reserve policy.
If real yields rise and DXY strengthens, gold may come under pressure.
A weak jobs report can produce the opposite response.
But the market reaction depends on the details.
Payroll growth
Unemployment rate
Average hourly earnings
Labour-force participation
Previous-month revisions
all contribute to the market’s interpretation.
The important question for a gold trader is not simply:
“Was NFP strong or weak?”
Instead ask:
“How did the report change expectations for real rates and future Fed policy?”
Real Yield Around FOMC
Federal Reserve decisions can produce some of the largest short-term changes in rate expectations.
Before an FOMC decision, traders should know what the market already expects.
Then monitor:
Policy rate
Statement language
Economic projections
Dot plot when available
Press conference
Treasury yields
Real yields
DXY
XAU/USD
Suppose the Fed holds rates but becomes more hawkish.
If the market pushes real yields higher, gold can sell off even though the current policy rate did not change.
This is another example of why the future path of policy matters more than the headline rate alone.
How Indian Traders Can Use Real Yield
For Indian traders, real yields are particularly useful when trading XAU/USD because the international gold market is heavily influenced by U.S. monetary conditions.
A practical dashboard can contain:
XAU/USD
DXY
U.S. 10-year Treasury yield
U.S. 10-year TIPS yield
U.S. inflation expectations
Fed rate expectations
USD/INR
MCX Gold
You do not need to trade every instrument.
The purpose is to understand the environment.
For example:
XAU/USD rising
Real yields falling
DXY falling
This is generally a supportive macro combination for gold.
Another example:
XAU/USD falling
Real yields rising
DXY rising
This is generally a more defensive environment for gold longs.
Now consider:
XAU/USD rising
Real yields rising
DXY rising
That is a warning that another gold driver may be overpowering the traditional rate relationship.
Perhaps safe-haven demand is strong.
Perhaps central-bank buying is supporting the market.
Perhaps positioning is forcing short covering.
This is where a trader should investigate rather than blindly follow one indicator.
Real Yield and MCX Gold
Indian traders often focus on MCX Gold rather than XAU/USD.
The international gold price still matters.
But MCX Gold is influenced by the relationship between global gold prices and the Indian rupee.
A simplified relationship is:
MCX Gold ≈ Global Gold Price × USD/INR + local market factors.
This means an Indian trader can see a situation where international gold is relatively flat but MCX Gold is stronger because the rupee weakens.
Therefore, when using real yields for Indian-market analysis, think in layers:
U.S. real yields
→ XAU/USD
→ USD/INR
→ MCX Gold.
This is much more useful than looking at the real yield alone.
A Practical Real-Yield Trading Framework
Here is a simple framework that can be used before major U.S. events.
Step 1: Check Real Yield Direction
Is the U.S. 10-year real yield rising, falling or moving sideways?
Do not focus only on the current level.
The direction and speed of the move can be important for short-term trading.
Step 2: Check DXY
Is the dollar confirming the real-yield move?
Rising real yields plus rising DXY is a stronger bearish environment for gold than rising real yields with a falling DXY.
Step 3: Check XAU/USD Structure
Look at the actual price.
Identify:
Previous day high
Previous day low
Major support
Major resistance
Recent swing high
Recent swing low
Breakout zones
Liquidity areas
Macro analysis should provide context, not replace price structure.
Step 4: Check the Economic Catalyst
Ask what caused the real-yield movement.
Was it:
CPI?
NFP?
PPI?
FOMC?
Retail Sales?
GDP?
Fed speech?
Treasury auction?
Geopolitical risk?
Fiscal news?
The reason behind the yield move matters.
Step 5: Wait for Confirmation
If your strategy requires confirmation, wait for price to react to a technical level.
For example:
Real yields rising
DXY rising
XAU/USD breaks support
Retest fails
Bearish structure confirms
That provides a much stronger trading framework than simply selling because a yield chart moved higher.
A Four-Box Gold Macro Model
You can simplify the entire concept into four boxes.
Box 1: Real Yields
Rising real yields generally create a headwind.
Falling real yields generally create a tailwind.
Box 2: DXY
Rising DXY generally creates pressure on dollar-priced gold.
Falling DXY generally supports dollar-priced gold.
Box 3: Risk Sentiment
Risk-off conditions can create safe-haven demand.
Risk-on conditions can reduce defensive demand, although this relationship is not always consistent.
Box 4: Gold-Specific Demand
Central-bank purchases, ETF flows, Asian demand, physical demand and positioning can override the traditional macro relationship.
The best gold analysis combines all four.
Common Mistakes Traders Make With Real Yield
Mistake 1: Watching Nominal Yield Only
A trader sees the 10-year Treasury yield rise and immediately sells gold.
But if inflation expectations are rising faster, real yields may actually be falling.
Mistake 2: Treating Correlation as a Guarantee
Gold and real yields can diverge.
A historical relationship is not a guaranteed intraday signal.
Mistake 3: Ignoring DXY
Real yields and the dollar often interact.
Ignoring DXY can leave part of the macro picture missing.
Mistake 4: Ignoring Safe-Haven Demand
During major geopolitical or financial stress, investors may buy gold even when real yields are high.
Mistake 5: Trading the Indicator Instead of the Price
Macro indicators explain market conditions.
They do not automatically provide an entry price, stop-loss level or take-profit level.
Mistake 6: Using Delayed Data Without Context
Real-yield data can move rapidly around major economic events.
Always understand whether the number you are looking at is live, delayed or based on an end-of-day observation.
Real Yield and Prop-Firm Trading
If you trade XAU/USD through a prop-firm evaluation or funded account, real-yield analysis can be useful for identifying high-risk periods.
Major changes in real yields can occur around:
FOMC decisions
CPI
NFP
PPI
Fed speeches
Treasury auctions
Major fiscal announcements
These events can create rapid gold moves.
A macro trader may correctly identify the direction and still lose money because of poor execution.
During high-volatility events:
Reduce position size when appropriate.
Avoid oversized leverage.
Know the firm’s news-trading rules.
Check spread conditions.
Account for slippage.
Do not move your stop-loss emotionally.
Remember that being correct about the macro direction does not guarantee a profitable trade.
How to Read a Real-Yield Move in Real Time
When gold suddenly moves, ask five questions.
Question 1:
What happened to the U.S. 10-year real yield?
Question 2:
What happened to DXY?
Question 3:
What happened to nominal Treasury yields?
Question 4:
What economic or policy event caused the move?
Question 5:
Is XAU/USD confirming the macro signal or fighting it?
If all major variables point in the same direction, the macro signal is stronger.
If they disagree, expect more complex price action.
Example: A Bullish Gold Environment
Imagine the market receives weak U.S. economic data.
Rate-cut expectations increase.
Treasury yields decline.
Real yields decline.
DXY weakens.
XAU/USD breaks above resistance.
This is a clean macro alignment.
The chain is:
Weak data
→ lower rate expectations
→ lower real yields
→ weaker USD
→ stronger gold environment.
A trader can then use technical analysis to identify the entry rather than chasing the initial headline.
Example: A Bearish Gold Environment
Now imagine U.S. inflation comes in hotter than expected.
Markets price fewer rate cuts.
Treasury yields rise.
Real yields rise.
DXY strengthens.
XAU/USD breaks below support.
Again, the macro variables are aligned.
The chain becomes:
Hot inflation
→ higher rate expectations
→ higher real yields
→ stronger USD
→ bearish pressure on gold.
But even in this situation, the trader should manage event risk because the initial move can reverse.
When Real Yield and Gold Diverge
One of the most useful skills is recognizing divergence.
Suppose:
Real yields rise.
DXY rises.
Gold also rises.
Do not immediately conclude that the real-yield relationship is broken.
Investigate what else is happening.
Possible explanations include:
Safe-haven demand
Central-bank buying
Strong Asian demand
Positioning changes
Short covering
Geopolitical risk
Concerns about fiscal stability
Expectations of future inflation
Technical breakout
Divergence is information.
It tells you that another market force is currently strong enough to offset the traditional macro pressure.
The 2026 Context
The relationship between gold and real yields remains important in 2026, but recent market behavior demonstrates why traders should not use it mechanically.
World Gold Council research in 2026 has highlighted that real yields and the U.S. dollar remain important opportunity-cost variables while central-bank demand and Asian investment can materially influence gold.
That means the modern gold trader needs a broader framework.
Instead of asking:
“Are real yields high?”
Ask:
“Are real yields rising or falling, what is driving the move, how is DXY reacting, and what other sources of gold demand are active?”
That is a much better trading question.
Final Takeaway
Real yield is one of the most useful macro concepts for gold traders.
The basic relationship is straightforward:
Higher real yields can increase the opportunity cost of holding gold.
Lower real yields can reduce that opportunity cost.
But gold is not controlled by real yields alone.
The U.S. dollar, inflation expectations, Federal Reserve policy, Treasury yields, central-bank demand, geopolitical risk, investor positioning and Asian demand can all change the final outcome.
For Indian traders, the most practical framework is:
Real Yield → DXY → XAU/USD → USD/INR → MCX Gold.
Use real yields to understand the macro environment.
Use DXY and Treasury markets to confirm the direction.
Use XAU/USD price structure to find the trade.
Use risk management to decide whether the trade is worth taking.
The objective is not to predict every move in gold. The objective is to understand the forces behind the move and avoid trading blindly against the macro environment.
FAQs
What is real yield?
Real yield is an inflation-adjusted measure of the return available from an investment. In simple terms, it can be approximated as nominal yield minus expected inflation.
Why does real yield matter for gold?
Gold does not pay a conventional interest rate. When real yields rise, the opportunity cost of holding gold can increase. When real yields fall, that opportunity cost can decrease.
What is the best real-yield indicator for gold traders?
The U.S. 10-year TIPS yield is one of the most commonly watched market-based measures of U.S. real yields.
Does higher real yield always mean lower gold?
No. Gold can rise despite higher real yields because of safe-haven demand, central-bank buying, Asian demand, positioning, geopolitical risk and other factors.
Should Indian traders watch real yield for MCX Gold?
Yes. Real yields can help explain movements in international gold prices. For MCX Gold, traders should also monitor USD/INR because currency movements can amplify or offset changes in global gold prices.
What is the difference between nominal yield and real yield?
Nominal yield is the market yield before adjusting for inflation. Real yield attempts to capture the inflation-adjusted return.
How does CPI affect real yield?
CPI can change expectations for inflation and Federal Reserve policy. The resulting changes in Treasury yields and inflation expectations can push real yields higher or lower.
How does the Fed affect gold through real yields?
A hawkish Fed can increase expectations for higher or longer-lasting interest rates, potentially pushing real yields higher and creating pressure on gold. A dovish Fed can have the opposite effect.
Can real yield be used as a standalone trading signal?
It is better used as a macro filter rather than a standalone entry signal. Price structure, volatility, DXY, event risk and technical confirmation should also be considered.
Sources & Further Reading
Federal Reserve — Policy Rate
https://www.federalreserve.gov/economy-at-a-glance-policy-rate.htm
World Gold Council — Gold Market Commentary: Making Waves
https://www.gold.org/goldhub/research/gold-market-commentary-july-2026
World Gold Council — Gold Demand Trends Q2 2026
https://www.gold.org/goldhub/research/gold-demand-trends/gold-demand-trends-q2-2026/outlook
World Gold Council — Investment Update: Rates Pose Risks but Also Unlock Opportunities for Gold
https://www.gold.org/goldhub/research/investment-update-rates-pose-risks-also-unlock-opportunities-gold
TradeOG provides educational information only and does not provide financial advice. Trading leveraged instruments such as XAU/USD can result in substantial losses.