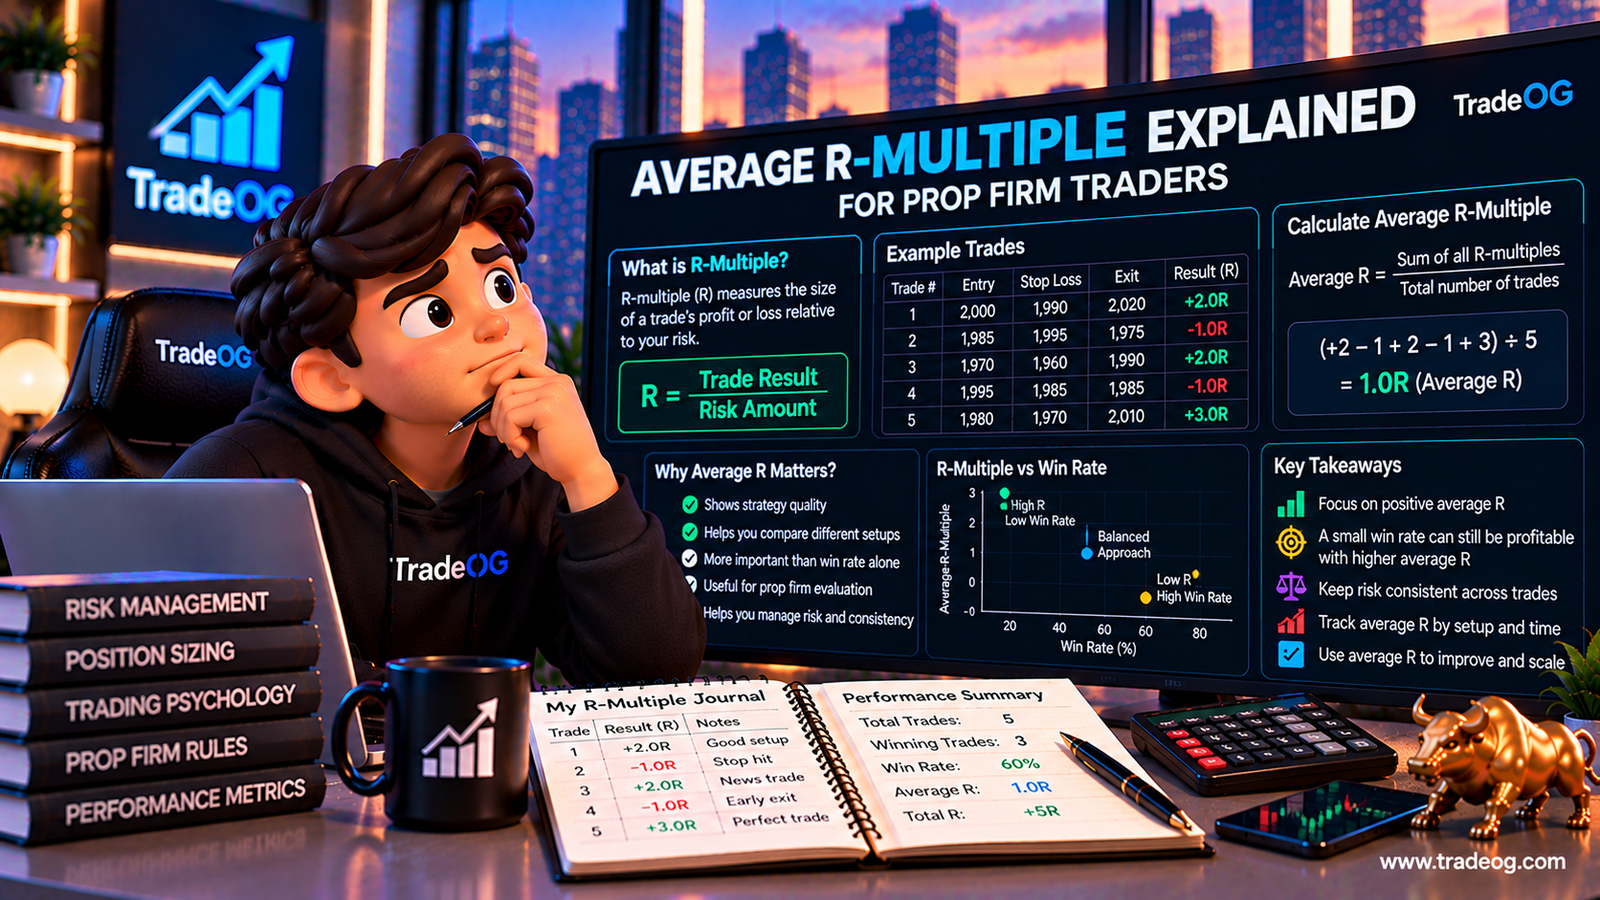
If you want to understand whether your prop trading strategy is actually producing consistent results, looking only at dollars, win rate, or profit is not enough. One of the most useful performance metrics is the R-multiple.
R-multiple puts every trade on the same risk scale. Instead of saying one trade made $100 and another made $500, you can describe them relative to the amount you originally planned to risk. That makes it easier to compare trades, setups, instruments and time periods even when your position size changes.
Average R-multiple takes this one step further. It tells you the average R result across a group of trades. For prop traders, this can help answer a practical question: How much has each trade actually produced or lost relative to the risk I took?
This guide explains what R means, how to calculate it, how to calculate average R-multiple, why it can be more useful than looking at dollars alone, how it connects with win rate and expectancy, and how to use it in a prop firm trading journal.
What Is an R-Multiple?
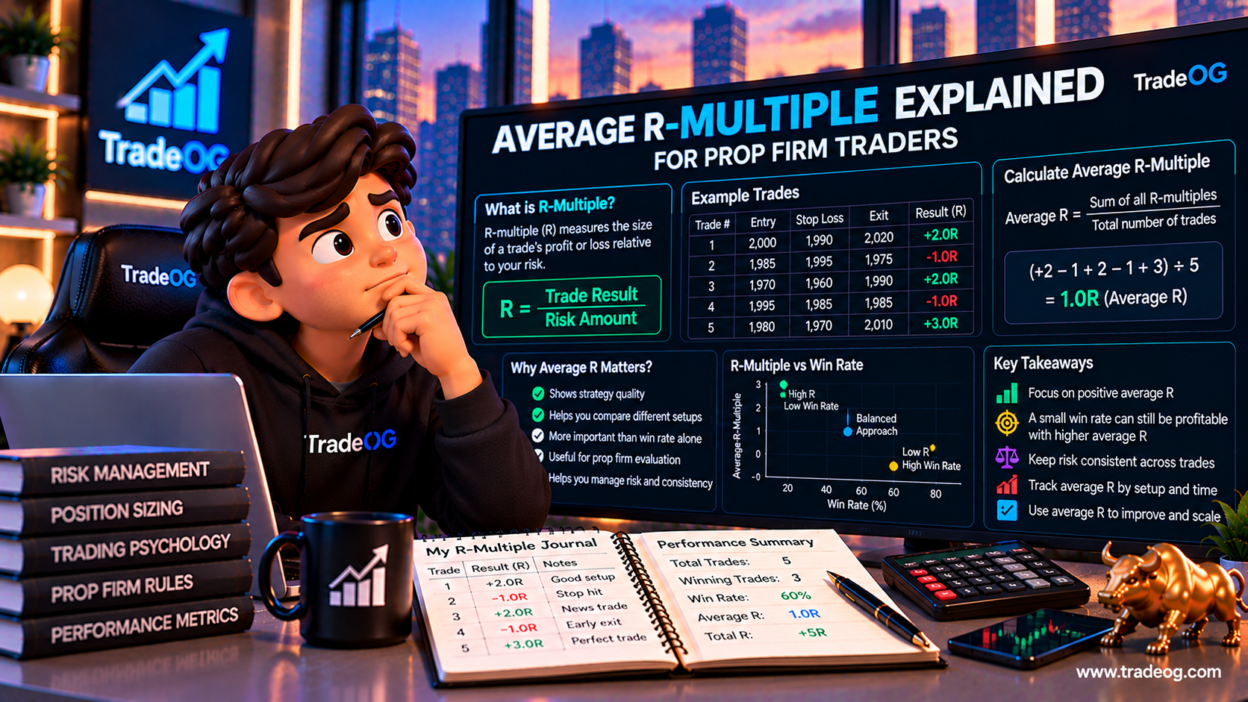
R-multiple expresses a trade’s result as a multiple of the initial amount you planned to risk.
The basic formula is:
R-Multiple = Net Trade Result ÷ Initial Planned Risk
If you planned to risk $100 and the trade makes $200, the result is +2R.
If the trade loses the full planned $100, the result is -1R.
If the trade makes $50, the result is +0.5R.
| Trade Result | Initial Risk | R-Multiple |
|---|---|---|
| +$200 | $100 | +2R |
| +$50 | $100 | +0.5R |
| $0 | $100 | 0R |
| -$100 | $100 | -1R |
| -$150 | $100 | -1.5R |
The important part is that 1R must be defined before the trade. If you change the definition after seeing the outcome, your R statistics can become misleading.
What Does 1R Mean in Prop Trading?
For a prop trader, 1R is normally the amount you planned to lose if the original trade idea reached its stop-loss under your predefined risk model.
For example, suppose your account risk plan says that a particular trade can risk $200.
Then:
- 1R = $200
- 2R = $400
- 0.5R = $100
- -1R = -$200
- -2R = -$400
This does not mean every trade will actually lose exactly $200 at the stop. Slippage, partial fills, fees, execution and discretionary changes can make the realized dollar result different.
The purpose of R is to create a consistent measurement framework.
Why R-Multiple Is Useful for Prop Firm Traders
Prop traders often change position size. You might trade Micro contracts on one setup and a different contract size on another. You might also reduce size when volatility increases or when the remaining drawdown buffer becomes smaller.
If you judge performance only in dollars, these changes can make two otherwise similar trades look completely different.
R-multiple removes much of that distortion.
Imagine:
- Trade A makes $100 with $100 planned risk = +1R
- Trade B makes $300 with $300 planned risk = +1R
Dollar profit is different, but both trades produced the same result relative to planned risk.
That makes R especially useful when comparing performance across different position sizes.
What Is Average R-Multiple?
Average R-multiple is the arithmetic average of the R results from a defined set of trades.
The formula is:
Average R = Sum of all R-multiples ÷ Number of trades
Suppose five trades produce:
- +2R
- -1R
- +2R
- -1R
- +3R
Total R is:
2 − 1 + 2 − 1 + 3 = +5R
There are five trades, so:
Average R = +5R ÷ 5 = +1R per trade
In this hypothetical sample, the average trade produced +1R.
Average R Is Not the Same as Average Winning R
This distinction matters.
Average winning R looks only at profitable trades.
Average R includes winning trades, losing trades and zero-result trades in the selected sample.
For example, suppose your results are:
- +3R
- +2R
- -1R
- -1R
- 0R
Average winning R is:
(3 + 2) ÷ 2 = +2.5R
But overall average R is:
(3 + 2 − 1 − 1 + 0) ÷ 5 = +0.6R
Both numbers can be useful, but they answer different questions.
How to Calculate Average R-Multiple Step by Step
Step 1: Define 1R
Before analyzing your trades, decide what 1R represents. For example, it could be your planned dollar risk based on the initial stop and position size.
Step 2: Calculate the R Result for Every Trade
Use:
R = Net Trade Result ÷ Planned Risk
Keep the same methodology across the dataset.
Step 3: Record the R Values in Your Journal
Your journal might look like this:
| Trade | Planned Risk | Net Result | R Result |
|---|---|---|---|
| 1 | $100 | +$200 | +2R |
| 2 | $100 | -$100 | -1R |
| 3 | $200 | +$400 | +2R |
| 4 | $200 | -$200 | -1R |
| 5 | $100 | +$300 | +3R |
Step 4: Add the R Results
2 − 1 + 2 − 1 + 3 = 5R
Step 5: Divide by the Number of Trades
5R ÷ 5 = +1R average
You now have the average R-multiple for that sample.
Why R-Multiple Can Be Better Than Dollars for Strategy Comparison
Suppose you have two months of trading data.
In Month One, you made $3,000.
In Month Two, you made $2,000.
At first glance, Month One looks better. But suppose your average planned risk was $500 per trade in Month One and $200 in Month Two.
Dollar profit alone does not tell the whole story.
R-based analysis can show whether the trading process generated similar or different results relative to the risk taken.
This becomes particularly useful when you deliberately reduce position size after a drawdown. A smaller dollar result does not necessarily mean your strategy became less effective.
Average R vs Win Rate
Win rate tells you how frequently trades are profitable. Average R tells you the average result relative to planned risk.
Consider two hypothetical strategies.
| Strategy | Win Rate | Average Winner | Average Loser | Average R |
|---|---|---|---|---|
| A | 70% | +0.8R | -1R | +0.26R |
| B | 40% | +2.5R | -1R | +0.40R |
These are simplified hypothetical examples. Strategy B wins fewer trades but produces a larger average result per trade because its winners are larger relative to its losses.
This is why a trader should not automatically chase the highest win rate.
Average R and Expectancy
Average R is closely connected to expectancy.
If every trade is expressed in R, the average R across all trades is essentially the historical expectancy measured in R per trade for that dataset.
For example, if 100 trades produce a combined result of +35R:
Average R = +35R ÷ 100 = +0.35R per trade
This means the sample generated an average of +0.35 units of planned risk per trade.
It does not mean the next trade will make +0.35R. Individual trades can be strongly positive, strongly negative or close to zero.
Average R Does Not Guarantee Future Profit
This is an important limitation.
A positive historical average R does not guarantee that future trades will have positive results.
Trading outcomes are variable. A strategy can have a positive historical average while experiencing a sequence of losses in a different period.
For prop traders, this means average R should always be viewed alongside:
- Maximum consecutive losses
- Maximum drawdown
- Largest losing trade
- Largest losing streak
- Risk per trade
- Sample size
- Market conditions
A positive average is useful information, but it is not a promise about the next trade.
Average R and Risk-to-Reward Ratio Are Different
These two concepts are often confused.
Planned risk-to-reward ratio describes the structure of a trade before entry.
Realized R describes what actually happened after the trade closed.
For example, you might plan a trade with a 1:3 target.
But if you close the position at +0.5R, the realized result is +0.5R—not +3R.
Similarly, a planned -1R stop could become -1.2R because of slippage or execution differences.
That is why your journal should track both planned R:R and realized R.
How Partial Exits Affect R-Multiple
Partial exits can make R calculations more interesting.
Suppose you risk $200 on a trade. You close half the position at +1R and the remaining half at +3R.
The final trade result is not automatically +3R because only part of the position reached that outcome.
Your journal should calculate the actual net P&L of the complete trade and divide it by the original planned risk.
This produces the realized R for the entire position.
That method prevents traders from recording only their best partial exit and ignoring what happened to the rest of the position.
What Happens When You Move Your Stop?
Moving a stop can change the relationship between the original risk and the eventual loss.
Suppose the initial plan was:
- Planned risk = $200
- Initial stop = -1R
If the stop is moved farther away and the final loss becomes $350, the trade result is approximately -1.75R based on the original $200 risk.
That distinction is important for performance analysis because the realized R reveals that the trade exceeded the original risk plan.
Do not silently redefine 1R after the loss simply to make the statistics look cleaner.
Average R by Trading Setup
One of the best uses of R-multiple analysis is comparing setups.
Tag every trade with the setup that generated the entry.
Then calculate average R for each meaningful group.
| Setup | Trades | Total R | Average R |
|---|---|---|---|
| Breakout | 50 | +18R | +0.36R |
| Pullback | 60 | +30R | +0.50R |
| Reversal | 40 | -4R | -0.10R |
These numbers are hypothetical. The important idea is that overall performance can hide differences between individual setups.
A trader might discover that the account is profitable because one setup has positive average R while another setup consistently consumes risk.
Average R by Instrument
You can use the same framework for different markets.
For example, a futures trader might separate:
- ES
- MES
- NQ
- MNQ
- Gold futures
- Other instruments permitted by the trading program
The point is not to assume that one market is better. The objective is to measure your own historical performance by instrument.
Because R normalizes the result relative to planned risk, it can make cross-instrument comparisons easier than comparing raw dollars.
Average R by Trading Session
Session analysis can reveal another layer of information.
Track average R separately for the time windows you actually trade.
For example:
- London session
- New York open
- New York afternoon
- Overnight session
- Specific high-volatility windows
If one session has consistently negative average R over a meaningful sample, investigate the reason. It could be related to market conditions, liquidity, execution, setup quality or simply a strategy that is not designed for that period.
Average R and Maximum Consecutive Losses
Average R tells you about average trade performance. Maximum consecutive losses tells you about the clustering of losing outcomes.
You need both.
Consider a strategy with +0.40R average performance but a historical maximum of eight consecutive losses. The average looks positive, but the trader still needs a risk plan that can withstand an eight-loss sequence and a larger stress scenario.
That is especially relevant when the prop firm’s drawdown buffer is relatively small compared with the trader’s normal position risk.
Average R and Drawdown
A positive average R does not tell you the size or duration of drawdowns.
Two strategies can both average +0.30R while having very different equity curves.
Strategy A might produce small, relatively stable fluctuations.
Strategy B might alternate between large winning and losing clusters.
For prop trading, the second profile may create more difficult drawdown conditions even though the average R is identical.
Track average R together with maximum drawdown, losing streaks and recovery time.
How to Use Average R When Choosing Position Size
Average R should not be used by itself to determine position size.
Suppose your historical average is +0.40R. If you define 1R as $100, the historical average dollar result is approximately +$40 per trade.
If you increase 1R to $500, the same historical average becomes approximately +$200 per trade.
But the downside scales too.
A -2R trade at $100 risk is -$200.
A -2R trade at $500 risk is -$1,000.
The R statistic remains -2R, while the dollar impact changes substantially.
This is why position sizing should be connected to the actual drawdown buffer and risk plan, not simply to an attractive historical average.
Average R for a Prop Firm Evaluation
During an evaluation, traders sometimes focus heavily on reaching a profit target. R-based analysis can provide a more useful process view.
Instead of asking only, “How much money have I made?” also ask:
- How much R have I generated?
- What is my average R per trade?
- How much R am I risking?
- What is my largest negative R result?
- How many consecutive losses have occurred?
- How much of the available drawdown has been consumed?
This can help separate a disciplined performance period from a period where the trader reached a target by taking unusually large risks.
Average R in a Funded Account
The same measurement remains useful after an evaluation.
In a funded account, the objective is not simply to maximize average R. The risk structure of the account still matters.
A trader could have positive average R while using a position size that creates unacceptable drawdown volatility.
Use average R as a performance statistic, then use drawdown and risk limits as constraints.
How Trading Costs Affect R
Decide whether your R calculation uses gross or net trade results.
If you want R to represent what the account actually earned or lost, using net trade results after applicable commissions, fees and execution costs can make the statistic more representative of realized performance.
For example, suppose your planned risk is $100 and a trade generates $120 before costs. If $20 of relevant costs reduce the final result to $100, the net result is +1R rather than +1.2R.
The exact treatment depends on what your journal defines as the trade result, but the methodology should remain consistent across the dataset.
Average R vs Average Profit Per Trade
These metrics are related but not identical.
Average profit per trade is measured in currency.
Average R is measured relative to planned risk.
If your position size remains constant, the two may move closely together. If position size changes significantly, R can provide a cleaner way to compare trading performance.
How Many Trades Do You Need?
There is no universal number of trades that makes average R statistically reliable.
A small sample can be dominated by one or two unusually large winners or losers.
For example, a five-trade sample of +3R, +2R, -1R, -1R and +3R produces a very different average from another five-trade sample. Adding the next 50 trades could materially change the result.
For that reason, track average R over multiple periods and use a meaningful sample before making major conclusions about a setup.
Rolling Average R
A useful advanced method is a rolling average R.
Instead of calculating one number from your entire history, calculate the average across the most recent group of trades.
For example:
- Last 20 trades
- Last 50 trades
- Last 100 trades
This can help identify whether recent performance is changing while the lifetime average remains stable.
Do not automatically interpret a short-term decline as proof that a strategy no longer works. Use the rolling statistic as a signal for deeper review.
A Practical Prop Firm R-Multiple Journal
| Journal Field | What to Record |
|---|---|
| Date | Trade date and session |
| Instrument | Market and contract |
| Setup | Entry model |
| Planned Risk | Dollar amount defining 1R |
| Planned R:R | Initial target structure |
| Net P&L | Final trade result |
| Realized R | Net P&L ÷ planned risk |
| Exit Reason | Target, stop, manual, partial or other |
| Rule Violation | Yes or no |
| Notes | Execution and lesson |
At the end of each week or month, calculate:
- Total trades
- Total R
- Average R
- Average winning R
- Average losing R
- Win rate
- Maximum consecutive losses
- Maximum drawdown
- Profit factor
What a Strong R-Multiple Review Looks Like
A useful review should not stop at “my average R was positive.” Ask why the number was positive.
For example:
- Did one unusually large winner create most of the positive result?
- Was risk consistent?
- Did average R remain positive across different months?
- Which setup contributed most of the R?
- Which setup produced negative R?
- Were losses larger than the original 1R plan?
- Did slippage materially change results?
- Did performance deteriorate during a specific session?
- Did the strategy maintain its results after position-size changes?
These questions turn R-multiple from a statistic into a decision-support tool.
Common R-Multiple Mistakes
1. Changing 1R After the Trade
Do not redefine your risk after seeing the result. Use the original planned risk consistently.
2. Confusing R:R With R-Multiple
A planned 1:3 risk-to-reward ratio does not mean the trade earned +3R. R-multiple records the realized outcome.
3. Ignoring Position Size
R standardizes the result, but your actual dollar exposure still matters for account survival.
4. Ignoring Partial Exits
Calculate the complete trade result rather than recording only the best portion of the position.
5. Ignoring Costs
Choose a gross or net methodology and apply it consistently.
6. Using Too Small a Sample
A few trades can produce an impressive average R that disappears when more observations are added.
7. Looking Only at Average R
Average R should be reviewed with drawdown, losing streaks, win rate and distribution of outcomes.
Frequently Asked Questions
What is a good average R-multiple?
There is no universal number that should be treated as a target for every prop trader. A positive historical average R means the selected sample produced a positive average result relative to planned risk. The useful question is whether the result is consistent, based on a meaningful sample, and compatible with your drawdown and risk rules.
Is average R the same as expectancy?
When every trade is expressed in R and the average includes all trades in the selected sample, average R represents the historical expectancy measured in R per trade.
Can average R be positive with a low win rate?
Yes. A strategy can have a lower win rate and still produce positive average R if its average winners are sufficiently larger than its average losers.
Should I calculate R using gross or net profit?
Either can be useful, but define the methodology clearly. If your goal is to understand realized account performance, net results after relevant trading costs can provide a more practical measure.
Does a positive average R mean I should increase my position size?
No. Average R is a historical performance statistic, not a position-sizing instruction. Position size should also account for drawdown, losing streaks, execution risk and the specific account rules.
Can I use average R for different futures contracts?
Yes. R can normalize trade results relative to planned risk, which can make comparisons between different contract sizes more meaningful. Always retain the actual contract, quantity and dollar risk in your journal.
Final Takeaway
Average R-multiple is one of the clearest ways to measure trading performance relative to risk.
The calculation is simple:
R = Net Trade Result ÷ Planned Risk
Then:
Average R = Total R Across Trades ÷ Number of Trades
The real value comes from using the metric consistently. Define 1R before the trade, record the actual result, and calculate average R across meaningful samples. Then break it down by setup, instrument, session and time period.
For prop traders, do not view average R in isolation. Pair it with win rate, average winning R, average losing R, maximum consecutive losses, maximum drawdown and the account’s actual risk limits.
A strategy producing +0.40R per trade historically can still experience a losing streak. A strategy producing a high average R from a tiny sample can still regress as more trades are added. The metric is useful because it makes the relationship between performance and risk visible—not because it predicts the next trade.
The practical goal is simple: know how much each trade has historically produced relative to what you risked, understand how stable that result is, and make sure your position sizing leaves enough room for normal losing sequences.