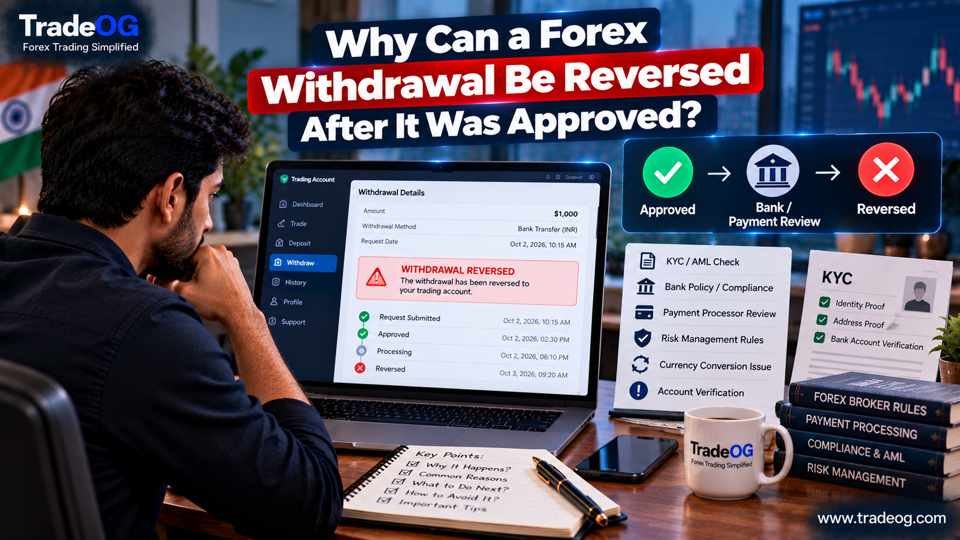
Seeing a forex withdrawal marked “Approved” and then seeing it reversed can be confusing. You may assume that approval means the money is already on its way to your bank. In practice, approval can be only one stage in the withdrawal process.
A withdrawal can still be stopped, returned or reversed after approval if a payment provider, bank, compliance team or broker identifies a problem before final settlement. The exact reason depends on the broker, withdrawal method, account history and destination bank.
This guide explains why an approved forex withdrawal can be reversed, what the status actually means, what to check first, and when you should contact the broker or bank.
What Does “Withdrawal Approved” Actually Mean?
“Approved” normally means the broker has accepted the withdrawal request for processing. It does not necessarily mean the receiving bank has completed the transfer.
A simplified withdrawal path can look like this:
Trading account → broker approval → payment processor/bank → intermediary → receiving bank → your account
A transaction can therefore be approved at the broker stage and still fail at a later stage.
| Status | What It Usually Means |
|---|---|
| Requested | You submitted the withdrawal. |
| Pending | The request is waiting for review or processing. |
| Approved | The broker has authorised the request to proceed. |
| Processing | The payment is being sent or settled. |
| Completed | The broker considers its processing complete. |
| Reversed | The payment did not complete as intended and the amount was returned or credited back. |
The exact terminology differs between brokers, so always check the broker’s own withdrawal-status definitions.
Why Can a Forex Withdrawal Be Reversed After Approval?
1. The Receiving Bank Rejected the Payment
One of the simplest explanations is that the receiving bank could not accept the payment.
Possible reasons include incorrect beneficiary information, an inactive account, unsupported payment instructions, compliance checks or a mismatch between the account details and the payment information.
In an international withdrawal, there may also be an intermediary or correspondent bank between the broker’s payment provider and your Indian bank. A problem at any stage can result in the payment being returned.
2. Bank Account Details Were Incorrect
A small mistake in the destination details can stop a withdrawal after it has already been approved.
Check:
- Account holder name
- Bank account number
- IFSC or other bank identifier where applicable
- SWIFT/BIC information for international wires
- Bank branch information where required
- Currency details
Do not assume that an approved status means the destination details were accepted by every bank in the chain.
3. Name Mismatch
Name matching is an important part of financial-account controls.
If the broker account is in one person’s name but the withdrawal destination belongs to another person, the broker or payment provider may stop the payment.
For example, FOREX.com states that the name on the trading account must match the name on the financial institution account for funding and withdrawal purposes. It also says that third-party withdrawals are not permitted and that additional verification may be required for a new bank account.
This is why you should normally use a bank account held in your own name when the broker requires name matching.
4. The Original Funding Method Creates a Withdrawal Restriction
Many brokers use a “return to source” approach for withdrawals.
That means money deposited by card may need to be returned to that card or its associated account before excess funds can be sent elsewhere. This is designed partly around anti-money-laundering and fraud controls.
FOREX.com, for example, says deposited funds must be returned to the originating source and explains that excess funds can be withdrawn through bank transfer or wire under its stated conditions.
If you request the withdrawal to a different destination without meeting the broker’s funding hierarchy, the transaction can be delayed, rejected or reversed.
5. KYC or AML Review Happens After Initial Approval
Approval does not necessarily mean every compliance check is permanently finished.
A broker or payment provider may identify something that requires additional verification during processing, such as:
- Unusual transaction activity
- Large or unexpected withdrawal
- Change in bank details
- Different funding source
- Incomplete account information
- Source-of-funds questions
- Potential fraud indicators
- Required KYC re-verification
Financial institutions use KYC and ongoing transaction monitoring to identify unusual activity and verify customer information.
In that situation, an approved withdrawal can still be stopped before final settlement.
6. The Payment Processor Could Not Complete the Transfer
Your broker may use a separate payment processor to handle the actual payout.
The broker can approve your request, but the processor may subsequently reject or return it because of a technical, banking or compliance issue.
This is particularly relevant when the withdrawal crosses several payment networks or countries.
7. The Bank Account Was Not Fully Verified
Some brokers require proof that a destination bank account belongs to you before sending a withdrawal.
A bank statement may be requested showing your name, account details and other identifying information.
FOREX.com states that it can require a bank statement when a customer wants excess funds sent to a new bank account.
8. The Original Card or Bank Account Is Closed
A common problem occurs when the payment method used for the original deposit is no longer available.
For example, you might have deposited using a debit card and then closed that card before requesting a withdrawal.
The broker may need evidence from the bank showing that the original funding account is closed or unavailable before allowing an alternative withdrawal route. FOREX.com explicitly describes this type of verification for unavailable funding accounts.
9. The Withdrawal Amount Exceeds the Amount That Can Be Returned to the Original Method
Card withdrawals can sometimes be limited to the amount previously deposited through the card, with profits or excess funds handled through another method.
For example, if you deposited $500 by card and your account later grew to $1,000, a broker may return the original $500 to the card and require the remaining $500 to be withdrawn by bank transfer or wire, subject to its rules.
FOREX.com explains a similar “return deposited funds to the originating source” structure.
10. Currency or Payment-Rail Problem
An international withdrawal may involve currency conversion and multiple banking systems.
For an Indian trader, a withdrawal could involve:
USD balance → broker → international payment provider → correspondent bank → Indian bank → INR conversion/credit
If one institution cannot process the currency or payment instruction, the transfer may be returned.
11. Bank or Payment Network Technical Failure
Not every reversal is caused by something you did.
Payment systems can experience technical failures, rejected messages, incomplete settlement or temporary processing problems.
If the broker confirms that the withdrawal was returned by the payment network, ask for the transaction reference and the precise return reason.
12. Open Positions or Margin Requirements Changed
A withdrawal can reduce the funds available to support open positions.
If market prices move after the withdrawal request, your available margin can change. A broker may therefore reconsider or restrict a withdrawal if processing it would leave the account unable to support its positions under the broker’s rules.
FOREX.com warns that withdrawing funds can reduce available margin and may contribute to liquidation of open positions if the account no longer has enough margin.
This is different from a payment reversal, but it is an important reason to understand your available balance before requesting a withdrawal.
Approved vs Completed: They Are Not the Same
This distinction is one of the most important things to understand.
| Status | Can It Still Fail? | Why? |
|---|---|---|
| Requested | Yes | Awaiting broker review |
| Approved | Yes | Payment still has to settle |
| Processing | Yes | Bank/payment network may reject or return it |
| Completed by broker | Possibly | Receiving bank may still take time to post funds |
| Credited to bank | Generally no | Funds have reached the destination account |
Always distinguish between broker-side completion and actual bank credit.
What Happens to the Money After a Withdrawal Is Reversed?
In a normal reversal, the amount is returned to the trading account or otherwise made available again according to the broker’s process.
However, the exact treatment depends on the reason for the reversal.
You should check whether the transaction is:
- Returned to available trading balance
- Still under review
- Marked as failed
- Waiting for a corrected bank destination
- Being refunded through the original payment method
If the broker says the withdrawal was reversed but the balance has not reappeared, ask for a transaction reference and written confirmation of where the funds currently are.
What Should You Do When a Withdrawal Is Reversed?
Step 1: Check the Exact Status
Do not rely only on an email subject such as “Withdrawal Approved”. Open the broker’s transaction history and check the latest status and any reason code.
Step 2: Check Your Trading Balance
Confirm whether the reversed amount has returned to your available balance.
Step 3: Check Your Email and Support Messages
The broker may have requested additional documents or explained that the bank rejected the transaction.
Step 4: Verify Your Bank Details
Compare the destination account information with the bank details saved at the broker.
Step 5: Check Name Matching
Make sure the bank account holder name matches the broker account where the broker requires this.
Step 6: Check the Original Funding Method
Look at how you deposited the money. If you used a card, bank transfer or multiple methods, the broker may apply a specific withdrawal hierarchy.
Step 7: Contact Official Support
Ask the broker for the exact reversal reason instead of simply asking when the money will arrive.
A useful support message is:
“My withdrawal request was approved but later reversed. Please confirm the exact reversal reason, whether the funds have returned to my available balance, which payment stage rejected the transaction, and whether any document or bank-detail correction is required.”
What Information Should You Give the Broker?
| Information | Why It Helps |
|---|---|
| Withdrawal ID | Identifies the transaction |
| Amount | Helps locate the payment |
| Request date/time | Narrows the transaction search |
| Withdrawal method | Identifies the payment route |
| Bank details | Helps check destination problems |
| Approval timestamp | Shows when the broker approved it |
| Reversal timestamp | Helps identify where processing stopped |
| Error/reason code | May identify the exact problem |
Why Does a Broker Ask for a Bank Statement?
A bank statement can help verify ownership of the destination account.
It may show:
- Your legal name
- Bank name
- Account number or last four digits
- Address where required
- Relevant funding transaction
Do not send a statement to an unofficial WhatsApp number or random email address. Upload documents through the broker’s authenticated portal or its official support process.
Can a Withdrawal Be Reversed Because of a Name Mismatch?
Yes, depending on the broker’s rules and payment provider.
A withdrawal to someone else’s bank account can trigger compliance or payment controls. Even if the broker initially approves the request, the payment may later be rejected when the destination institution checks the account information.
This is why the safest workflow is to use a destination account that satisfies the broker’s ownership and name requirements.
Can a Withdrawal Be Reversed Because of KYC?
Yes. If the broker or payment provider needs updated verification, the withdrawal can be stopped until the required information is supplied.
Do not assume that completing KYC when you opened the account means you will never be asked for additional verification. Financial institutions can conduct ongoing monitoring and request updated information when circumstances change.
What If the Broker Says the Bank Reversed It?
Ask for the payment reference or return message.
You want to know whether:
- The bank rejected the transfer
- An intermediary bank returned it
- The payment processor rejected it
- The beneficiary information was invalid
- The transaction was stopped for compliance reasons
- The payment was returned because the account could not accept the currency
The phrase “bank rejected it” is not enough to diagnose the problem. Ask which bank or payment stage rejected the transaction and why.
What If the Money Does Not Return After the Reversal?
Do not send another withdrawal request immediately.
First ask the broker:
- Has the original withdrawal been formally reversed?
- Has the amount been credited back to my trading balance?
- What is the reversal reference?
- Is the money currently with the broker or payment provider?
- Do I need to submit new bank details?
If the broker confirms that the funds have been returned to the trading account but your displayed balance does not reflect them, request a transaction ledger or account statement.
Be Careful With Fake Withdrawal “Unlock” Fees
A reversal can create an opportunity for scammers to contact traders.
Be suspicious if someone claims you must pay an additional:
- Release fee
- Unlock fee
- Security deposit
- Special withdrawal tax
- Anti-money-laundering clearance fee
- Refund activation fee
Do not send additional money simply because someone says your withdrawal is frozen. Verify the situation through the broker’s official website and authenticated support channel.
What About Forex Withdrawals for Indian Traders?
Indian traders need to consider a separate regulatory issue before focusing only on payment processing.
The Reserve Bank of India states that resident persons can undertake forex transactions only with authorised persons and for permitted purposes under FEMA. RBI has also cautioned residents against undertaking forex transactions on unauthorised electronic trading platforms or depositing money for unauthorised forex transactions.
Therefore, a successful deposit or an approved withdrawal does not by itself establish that a forex platform is authorised for an Indian resident.
Before sending or receiving funds, verify the relevant broker, authorised person and electronic trading platform status under the applicable RBI/FEMA framework.
RBI warning on unauthorised forex platforms
Example: ₹1,00,000 Withdrawal Approved Then Reversed
Imagine an Indian trader requests a ₹1,00,000 equivalent withdrawal.
The broker shows:
- Request submitted: 10:00 AM
- Approved: 1:30 PM
- Processing: 4:00 PM
- Reversed: next morning
The trader should not assume that the broker simply “took back” the money.
The next step is to identify where the payment failed.
Possible explanations could include a bank rejection, beneficiary mismatch, payment-provider issue, additional compliance review or an incorrect withdrawal route.
The trader should request the withdrawal ID, return/reversal reference and exact rejection reason before submitting another request.
How to Prevent Withdrawal Reversals
- Use a bank account in your own name where required.
- Keep your KYC information current.
- Verify bank details before submitting a withdrawal.
- Understand the broker’s return-to-source rules.
- Do not repeatedly change withdrawal destinations.
- Keep proof of your original deposits.
- Save withdrawal IDs and transaction references.
- Maintain enough free margin when withdrawing with open positions.
- Use only official broker payment channels.
- Never pay an unofficial person to “unlock” a withdrawal.
Withdrawal Reversal Checklist
| Check | What to Confirm |
|---|---|
| Withdrawal status | Approved, processing, reversed or failed? |
| Account balance | Has the money returned? |
| Bank details | Correct and verified? |
| Name | Matches the broker account? |
| Funding method | Does the withdrawal comply with return-to-source rules? |
| KYC | Any new verification request? |
| Withdrawal ID | Saved for support? |
| Reversal reason | Obtained in writing? |
| Payment reference | Available for bank/payment-provider tracing? |
Final Takeaway
An approved forex withdrawal can still be reversed because approval is not always the final settlement stage. The payment may subsequently fail at the bank, payment processor, intermediary, compliance review or destination-account stage.
The most important thing is to find the exact point where the withdrawal was returned. Check the withdrawal ID, bank details, name match, original funding method, KYC status and any reversal reference.
If the funds have not returned to your trading balance, ask the broker to confirm exactly where the money is and provide a transaction reference. Do not pay an unofficial “release” or “unlock” fee and do not submit repeated withdrawals until the original reversal is understood.
FAQs
Can a forex withdrawal really be reversed after approval?
Yes. Approval can mean that the broker accepted the request for processing, while the payment still has to pass through a bank or payment processor.
Why was my forex withdrawal approved and then rejected?
Possible reasons include incorrect bank details, name mismatch, payment-provider rejection, compliance review, original funding-method restrictions, technical failure or a bank return.
Does an approved withdrawal mean the money has reached my bank?
No. A broker’s approved status is not necessarily the same as bank credit. Check whether the transaction is still processing and whether the receiving bank has posted the funds.
Can a name mismatch reverse a withdrawal?
Yes, depending on the broker and payment provider. Many brokers require withdrawals to go to an account that matches the trading-account holder.
What should I do if my withdrawal is reversed?
Check whether the funds returned to your trading balance, identify the reversal reason, verify your bank details and contact official broker support with the withdrawal ID and transaction reference.
Can a broker ask for more KYC after approving a withdrawal?
Yes. Additional verification can be required during transaction processing or ongoing compliance monitoring.
Should I submit another withdrawal immediately?
No. First determine why the original withdrawal was reversed and whether the funds have returned to your available balance.
Should I pay a withdrawal release fee?
Do not pay an unofficial release or unlock fee. Verify any legitimate charge directly through the broker’s official website and authenticated support channel.
Can an Indian trader use any forex broker for withdrawals?
No. RBI says resident persons can undertake forex transactions only with authorised persons and for permitted purposes, and has cautioned against unauthorised electronic trading platforms. Verify the applicable RBI/FEMA requirements before funding a platform.