A trading withdrawal can arrive at a different INR value simply because you requested the conversion over a weekend. When you withdraw USD, EUR, GBP or another foreign currency into an Indian bank account, the final INR amount depends not only on the amount you withdraw but also on the conversion rate, spread, provider markup, processing time and any separate fees.
The important point is that a weekend rate is not necessarily the same as the live weekday market rate. The global FX market is not continuously active through Saturday and Sunday, so banks, brokers, payment providers and currency platforms may use different pricing methods during the weekend window. Some may hold a reference rate, while others may add a wider margin or weekend buffer.
For Indian traders, this matters because a withdrawal that looks like $1,000 on the trading platform does not automatically mean a fixed INR amount will reach the bank account. The conversion decision can change the final payout.
Why Weekend Currency Conversion Rates Are Different
The foreign exchange market operates across global financial centres during the business week, but the main institutional FX market is closed during the traditional weekend period. As a result, there is no continuously updating wholesale market price that every retail provider must use on Saturday or Sunday.
A provider that continues to offer currency conversion during this period has to decide how to price the transaction. It may use a recent reference rate, apply its own spread, or build additional protection into the quoted rate because the underlying market can move before normal liquidity returns.
That is why two providers can show different USD-to-INR conversion rates for the same $1,000 withdrawal.
Does the FX Market Stop Moving Completely on the Weekend?
For practical retail-conversion purposes, traders should not treat a Saturday or Sunday quote as the same thing as a live interbank market quote. Some platforms can continue displaying prices, and some providers can continue processing conversions, but the underlying liquidity and pricing environment is different from a normal weekday.
This distinction is important when comparing the rate shown by a withdrawal provider with a Google or mid-market reference rate. A displayed weekend rate can be a provider’s executable rate rather than a pure market benchmark.
How a Weekend Rate Can Reduce Your Trading Withdrawal
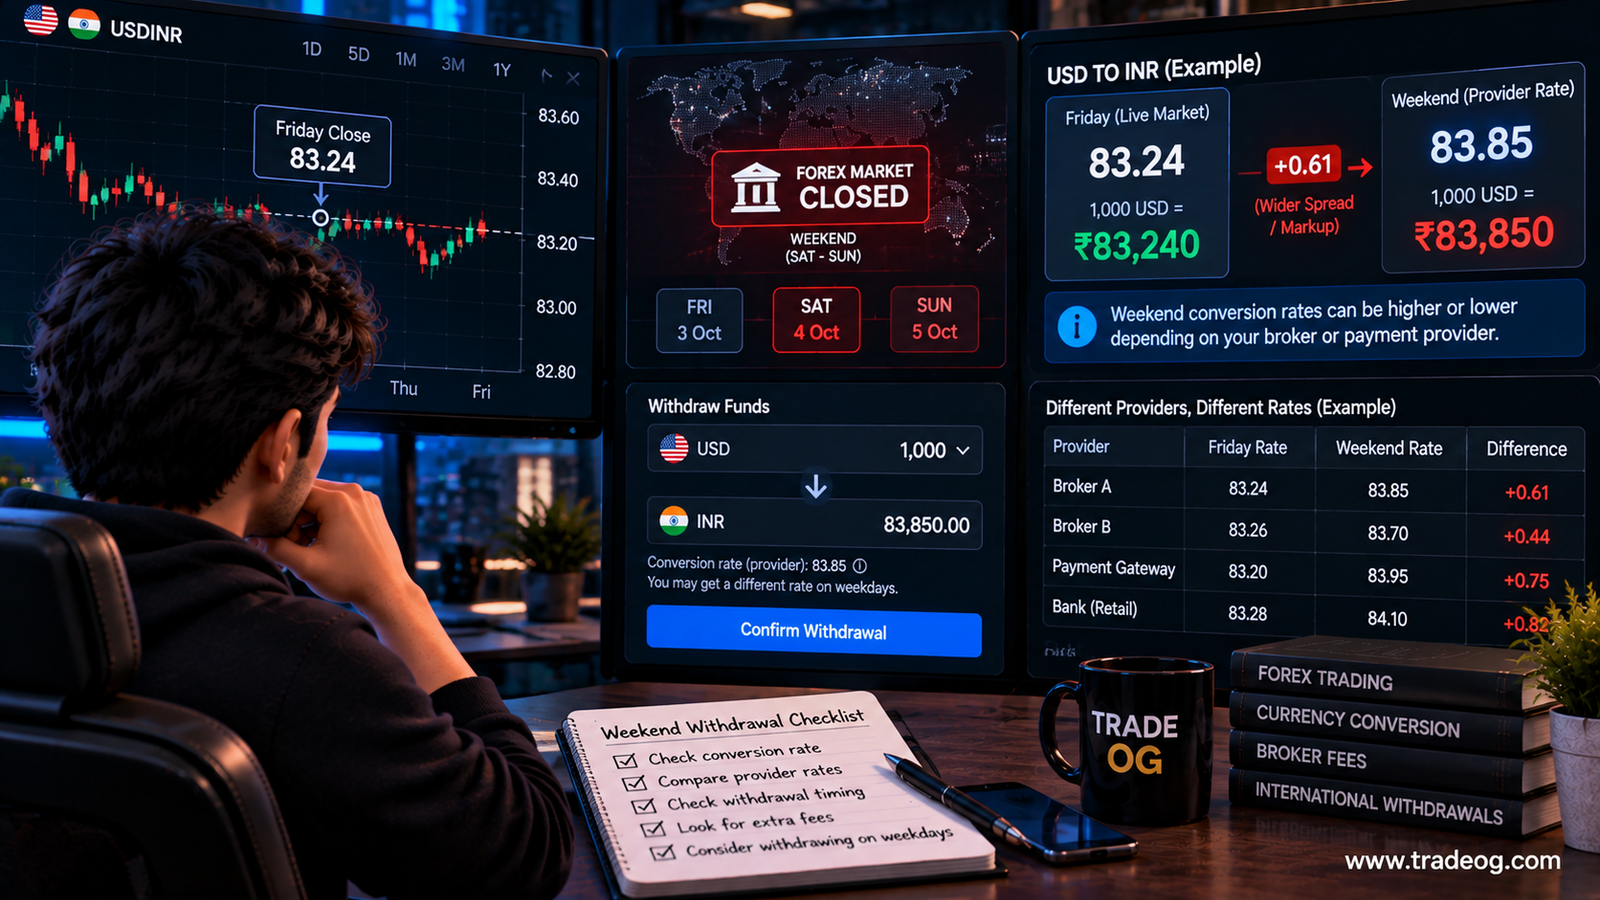
Consider a simple example. You have a $1,000 trading withdrawal.
| Scenario | Example USD/INR rate | INR before fees |
|---|---|---|
| Weekday conversion | ₹83.24 | ₹83,240 |
| Weekend provider rate | ₹82.85 | ₹82,850 |
| Difference | ₹0.39 | ₹390 |
These figures are only an illustration, not a current market quote. The point is that a small rate difference becomes a real rupee difference when the withdrawal amount is large.
At $5,000, the same ₹0.39 difference would represent ₹1,950 before considering any additional fees.
Weekend Markup vs Normal FX Spread
It is useful to separate two concepts that traders often combine.
Normal FX spread
A provider may quote a rate that is slightly worse than the mid-market rate as part of its normal pricing model. This spread can apply on weekdays as well as weekends.
Weekend markup or buffer
Some providers may widen the margin specifically during periods when major FX markets are closed. The provider is effectively protecting itself against uncertainty between the weekend transaction and the next active market session.
Not every bank, broker or payment service applies a weekend markup. You have to check the provider’s own pricing policy.
Why Weekend Withdrawals Can Be More Expensive Even When USD/INR Looks Stable
Suppose the USD/INR reference rate has barely moved since Friday. Your provider can still quote a different rate on Saturday.
Why?
- The provider may be using its own executable rate.
- The provider may have a wider spread during the weekend.
- The displayed rate may be based on a previous market reference.
- A conversion fee may be embedded into the quoted rate.
- The provider may price in the risk of Monday’s market reopening.
So a stable-looking reference chart does not guarantee an identical withdrawal conversion rate.
Trading Withdrawal Rate vs Google Exchange Rate
Google is useful as a reference, but it should not automatically be treated as the exact rate you will receive from a broker, bank or payment provider.
Your actual withdrawal can be affected by the provider’s spread, pricing feed, conversion policy and timing. TradeOG explains this in more detail in Why Does Your Broker Use a Different Exchange Rate Than Google?.
The same principle applies to weekend withdrawals: compare the provider’s final executable rate with a benchmark, rather than assuming the benchmark itself is your payout rate.
What Happens When a Broker Sends USD to an Indian Bank?
A foreign-currency withdrawal can pass through several stages before the final INR credit appears in your bank account. Depending on the withdrawal method, there may be an international payment, correspondent-bank processing, currency conversion and domestic bank credit.
The exact process varies by broker, bank and payment route. For a detailed explanation, see Forex Broker USD Withdrawal to Indian Bank Account: What Happens?.
The important point for weekend conversions is that the rate used at one stage may not be the same as the rate you saw when initiating the withdrawal.
Can the Rate Be Locked When You Request a Withdrawal?
Not always. Some providers lock the conversion rate immediately, while others treat the displayed amount as indicative until their payment or banking partner completes a later step.
This distinction can be especially important on Saturday and Sunday. A provider may accept the withdrawal request immediately but apply its conversion rate at a defined processing time or on the next business day.
Always check these questions before assuming the INR amount shown on the withdrawal screen is final:
- When is the exchange rate actually locked?
- Is the displayed INR amount indicative or final?
- Does weekend processing use a different rate?
- Does the provider add an FX markup?
- Are intermediary or receiving-bank fees separate?
- What happens if the withdrawal is processed on the next business day?
Why the Final Bank Credit Can Be Lower Than Your Calculation
Suppose you calculate a withdrawal using the Google USD/INR rate and expect ₹8,32,400 from a $10,000 withdrawal. Your provider may use a different conversion rate, and a bank or intermediary may apply additional charges.
That can create a gap between:
Expected INR = foreign-currency withdrawal × reference exchange rate
and
Actual INR received = withdrawal × provider’s applicable rate − applicable fees/charges
This is why comparing only the headline exchange rate can be misleading. The total landed amount is what matters.
Weekend Conversion and Small Trading Withdrawals
Weekend pricing can become more noticeable when the withdrawal is small because fixed charges consume a larger percentage of the amount.
For example, a ₹500 equivalent cost has a much larger percentage impact on a $200 withdrawal than on a $10,000 withdrawal. TradeOG covers this issue in Why Do Small Forex Transactions Cost More to Convert Into INR?.
Therefore, traders should evaluate both the exchange-rate difference and any fixed withdrawal or conversion charge.
How Currency Conversion Fees Reduce Trading Withdrawals
A withdrawal can lose value through several layers rather than one obvious fee. These can include the provider’s FX spread, a conversion markup, a withdrawal fee, correspondent-bank charges or a receiving-bank charge.
Our guide How Foreign Currency Conversion Fees Reduce Trading Withdrawals in India explains how these costs can reduce the amount ultimately received in INR.
Weekend timing adds another variable because the conversion rate itself can be different from the rate available during normal market hours.
Should Indian Traders Avoid Weekend Withdrawals?
Not necessarily. A weekend withdrawal can still make sense if the money is needed urgently or if the provider does not apply a meaningful weekend difference.
But if the withdrawal is flexible, it is sensible to compare the provider’s weekend quote with its normal weekday pricing before confirming the transaction.
For a large withdrawal, even a small rate difference can be worth checking.
Example: $5,000 Trading Withdrawal
Imagine a trader has $5,000 available to withdraw.
| Item | Weekday example | Weekend example |
|---|---|---|
| Withdrawal | $5,000 | $5,000 |
| Provider rate | ₹83.24 | ₹82.85 |
| Gross INR | ₹416,200 | ₹414,250 |
| Rate difference | ₹1,950 | |
Again, this is an educational example rather than a live quote. If both transactions had the same fees, the weekend rate alone would create a ₹1,950 difference.
If an additional withdrawal fee or bank charge also applied, the final difference would be larger.
How to Check a Weekend Trading Withdrawal Rate
- Record the foreign-currency withdrawal amount.
- Note the provider’s quoted exchange rate.
- Check whether the quote is final or indicative.
- Compare it with a reliable mid-market reference.
- Check the provider’s weekend pricing terms.
- Check fixed withdrawal and bank charges separately.
- Save the transaction timestamp and quote.
- Compare the final bank credit with your calculation.
What If the Provider Says the Rate Is “Live” on Saturday?
The word live does not automatically mean the quote is identical to a wholesale interbank rate.
A provider can continuously update its own executable rate based on internal pricing, liquidity sources, market references and risk controls. What matters is the rate actually applied to your transaction and the provider’s stated pricing methodology.
That is why the best comparison is always between the transaction rate and a clearly defined benchmark at the same time.
Weekend Withdrawals and INR Depreciation
The exchange-rate effect can also work in the opposite direction. If the INR weakens against the currency you are withdrawing between the time you plan the withdrawal and the time it is converted, the eventual INR value can be higher.
However, traders should separate their trading performance from the currency effect. TradeOG discusses this in How Indian Traders Can Calculate Their Real Return After INR Depreciation.
This is particularly useful when reviewing monthly or yearly trading performance in INR while the underlying account is denominated in USD.
Weekend Withdrawal Checklist for Indian Traders
- Check the USD/INR reference rate.
- Check the actual provider conversion rate.
- Confirm whether a weekend markup applies.
- Check if the rate is locked immediately.
- Check whether the INR amount is indicative.
- Check fixed withdrawal fees.
- Check correspondent-bank or receiving-bank charges where applicable.
- Keep a screenshot or record of the quoted rate.
- Compare the final bank credit with the expected amount.
- For large withdrawals, compare the cost of processing on a weekday if timing is flexible.
Final Takeaway
Weekend currency conversion rates can affect the amount you receive from a trading withdrawal because the normal FX market is closed and providers may use different pricing, spreads or risk buffers. Not every provider charges a weekend markup, and the exact policy varies, so traders should not assume that every Saturday or Sunday withdrawal will be more expensive.
The safest approach is to look beyond the headline USD/INR number. Check the provider’s actual conversion rate, when that rate is locked, whether the quote is indicative, and what separate fees may apply.
For Indian traders, the calculation that matters is simple: foreign currency withdrawn × actual conversion rate − applicable charges = INR received. If the withdrawal is large and timing is flexible, comparing the weekend quote with the provider’s normal weekday rate can reveal whether waiting is worthwhile.
FAQs
Do currency exchange rates change on weekends?
The main institutional FX market is not operating in the same way as during normal weekday sessions. Providers may still quote and process conversions, but their weekend rates can be based on reference prices, internal pricing or wider margins.
Can a weekend withdrawal receive a worse USD-to-INR rate?
Yes, it can, if the provider applies a weekend spread or markup. Some providers do not apply one, so the terms of the specific broker, bank or payment service matter.
Is the Google exchange rate the rate I will receive?
No. Google can be useful as a reference, but your actual withdrawal rate can include provider spreads, markups and other pricing differences.
Should I wait until Monday to withdraw trading profits?
If the withdrawal is not urgent, comparing the weekend quote with the provider’s normal weekday pricing can make sense. There is no guarantee that Monday will produce a better rate because USD/INR can move in either direction.
Can weekend FX costs affect prop-firm payouts?
Yes. If a payout is denominated in USD and ultimately converted into INR, the applicable conversion rate and fees can change the rupee value received even though the nominal payout amount in USD is unchanged.
How can I calculate my real withdrawal rate?
Divide the INR amount actually credited by the foreign-currency amount converted. Then compare that effective rate with a mid-market reference and account for any separate fees.
Educational content only. Exchange rates, provider pricing, bank charges and withdrawal policies vary by institution and can change. Always check the current terms of the service handling your transaction.