


Forex withdrawal fees can look small when viewed as a fixed dollar amount, but they can become a surprisingly large cost when the trading account or payout is small. A $10, $20 or $30 charge may be insignificant on a large withdrawal, yet the same fee can consume a meaningful percentage of a $200, $500 or $1,000 withdrawal.
This is why small-account traders should evaluate the percentage cost of withdrawing money, not just the headline withdrawal fee.
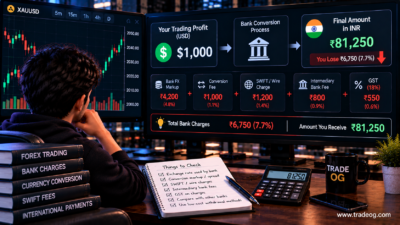
The total cost can include a broker withdrawal charge, payment-processor fee, currency-conversion spread or markup, intermediary-bank charge and receiving-bank fee. Not every transaction has every charge, but even one fixed fee can have a disproportionate impact on a small withdrawal.
Why Fixed Withdrawal Fees Hurt Small Accounts More
The basic mathematics is simple:
Effective withdrawal cost (%) = total fees ÷ withdrawal amount × 100
| Withdrawal | Total fees | Effective cost |
|---|---|---|
| $200 | $25 | 12.5% |
| $500 | $25 | 5% |
| $1,000 | $25 | 2.5% |
| $5,000 | $25 | 0.5% |
The fee did not change. The economic impact changed because the withdrawal amount changed.
Small Trading Accounts Face a Different Cost Problem
A trader with a $500 account may spend weeks generating a $50 or $100 profit. If a large percentage of that amount disappears during withdrawal, the trader’s real return can be much lower than the trading result shown on the platform.
This is especially relevant for traders who withdraw frequently. A fixed charge applied five times can cost much more than a single larger withdrawal, even when the total amount withdrawn is identical.
Withdrawal Fees Are Not Always Just One Fee
When traders say “my broker charges a $10 withdrawal fee,” that may not represent the complete cost.
- Broker withdrawal fee: a charge imposed by the trading platform.
- Payment-processor fee: a charge associated with the selected payment route.
- Currency conversion cost: a spread or markup in the exchange rate.
- Correspondent-bank charge: a cost that can occur during international transfers.
- Receiving-bank charge: a fee applied by the destination bank where applicable.
For Indian traders receiving a foreign-currency payout, the exchange rate itself can therefore be just as important as the visible withdrawal fee.
Why Currency Conversion Can Make the Cost Higher
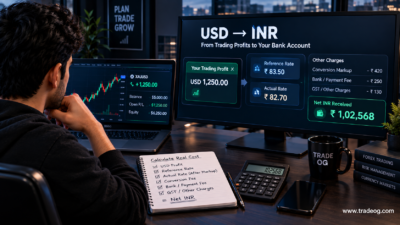
Suppose you withdraw $500 and expect to receive INR using a public USD/INR reference rate. Your broker or payment provider may use a different executable conversion rate.
The difference between the reference rate and the applied rate is an additional economic cost even if it is not displayed as a separate “withdrawal fee.”
TradeOG explains this in Why Does Your Broker Use a Different Exchange Rate Than Google?.
Example: $500 Withdrawal
Imagine a trader withdraws $500.
| Cost component | Illustrative amount |
|---|---|
| Broker withdrawal fee | $10 |
| Payment processing cost | $5 |
| Currency conversion impact | $8 |
| Other receiving/intermediary costs | $5 |
| Total economic cost | $28 |
A $28 cost on $500 represents 5.6%. The figures are illustrative; actual charges depend on the broker, payment method, bank and currency.
Now consider the same $28 cost on a $5,000 withdrawal. The percentage falls to only 0.56%.
Small Withdrawals vs Large Withdrawals
When the fee structure is partly fixed, larger withdrawals can be more efficient from a percentage-cost perspective.
| Withdrawal | Illustrative total cost | Percentage impact |
|---|---|---|
| $250 | $25 | 10% |
| $500 | $25 | 5% |
| $1,000 | $25 | 2.5% |
| $2,500 | $25 | 1% |
This does not mean traders should automatically wait until they have a large balance. Liquidity needs, account rules, risk management and the provider’s minimum withdrawal requirements still matter.
Why Frequent Withdrawals Can Be Expensive
Consider a trader who makes four $250 withdrawals instead of one $1,000 withdrawal.
If each withdrawal carries a $10 fixed charge, the four transactions cost $40. One $1,000 withdrawal would cost $10 under the same fee schedule.
The difference is created by transaction frequency rather than trading performance.
Before splitting a withdrawal into multiple small transactions, check whether the provider charges a fixed fee per request.
Minimum Withdrawal Limits Can Also Matter
Some providers impose minimum withdrawal amounts or different fees depending on the payment method. A small-account trader can therefore face a practical choice between withdrawing immediately with a high percentage cost or waiting until a larger amount can be withdrawn more efficiently.
Broker terms vary, so the minimum amount and current fee schedule should always be checked before submitting the request.
What Indian Traders Should Check Before Withdrawing
- Check the broker’s withdrawal fee.
- Check whether the payment processor charges separately.
- Check the minimum withdrawal amount.
- Check the conversion rate that will actually be applied.
- Check whether a currency-conversion markup is embedded in the rate.
- Check whether intermediary-bank fees may apply.
- Check whether your Indian bank can deduct receiving charges.
- Calculate the total cost as a percentage of the withdrawal.
For a broader explanation of the conversion process, read How Foreign Currency Conversion Fees Reduce Trading Withdrawals in India.
Weekend Timing Can Add Another Variable
If your withdrawal is converted during a weekend or through a provider that applies weekend pricing, the effective conversion rate can differ from a normal weekday rate.
TradeOG covers this separately in How Weekend Currency Conversion Rates Can Affect Trading Withdrawals.
For a small withdrawal, even a modest exchange-rate difference can matter because the conversion loss is measured against a relatively small principal amount.
How Small Fees Can Distort Trading Performance
Imagine a trader makes $100 in trading profit on a $500 account. If $25 disappears through withdrawal and conversion costs, the trader does not actually retain the full $100 as withdrawable profit.
This distinction matters when measuring performance:
Trading profit ≠ net cash received after withdrawal costs.
A more realistic measurement is:
Net withdrawal return = amount withdrawn − all withdrawal and conversion costs.
This helps traders compare the economics of different brokers and payment methods.
Withdrawal Fees vs Trading Costs
Withdrawal fees should not be analysed in isolation from the rest of the trading cost structure.
- Spread
- Commission
- Swap or financing costs
- Slippage
- Deposit costs
- Withdrawal costs
- Currency conversion costs
A broker with a low headline withdrawal fee may still be expensive if its conversion rate is consistently less favourable. Conversely, a provider with a visible fee may have a competitive total cost if its exchange rate is transparent.
How to Compare Two Withdrawal Methods
Do not compare providers only by asking, “Which one has the lowest withdrawal fee?”
Instead, calculate the amount you actually receive.
| Comparison | Method A | Method B |
|---|---|---|
| Withdrawal amount | $500 | $500 |
| Visible fee | $10 | $0 |
| Conversion impact | $8 | $20 |
| Other costs | $5 | $3 |
| Total economic cost | $23 | $23 |
A “zero withdrawal fee” option is not automatically cheaper if the provider earns more through the exchange rate.
Should Small Traders Withdraw Less Frequently?
Sometimes, yes, if the provider charges a fixed fee per withdrawal and there is no urgent need for the funds. Consolidating withdrawals can reduce the fee percentage.
However, this is not a universal rule. Traders should also consider counterparty exposure, account requirements, cash-flow needs and any minimum withdrawal limits.
How to Reduce the Impact of Withdrawal Fees
1. Compare the total landed cost
Look at the amount that actually reaches your bank account, not just the advertised fee.
2. Avoid unnecessary small withdrawal requests
If a fixed fee applies to every transaction, multiple small requests can increase your total cost.
3. Compare conversion rates
A provider can charge no explicit withdrawal fee while recovering its cost through the FX rate.
4. Check weekend pricing
If your timing is flexible, compare the applicable weekend and weekday conversion conditions.
5. Keep a withdrawal-cost record
Record the requested amount, quoted conversion rate, fees and final bank credit. After several withdrawals, you can calculate your real effective cost.
When a Higher Fee May Still Be Worth Paying
The cheapest headline fee is not always the best choice.
A payment method with a $10 fee may be preferable to a “free” method that gives you a significantly worse conversion rate. Speed, reliability, supported currencies and bank compatibility can also have economic value.
The correct comparison is therefore the total amount received for the same withdrawal amount.
Small Accounts and Compounding
Withdrawal costs can also matter for traders who are trying to compound a small account.
If a trader repeatedly removes profits and pays a high percentage in fees, less capital remains available for future trading. Over many withdrawal cycles, the cumulative effect can become material.
This does not mean traders should keep money at a broker purely to avoid fees. Capital should be managed according to the trader’s risk tolerance, withdrawal needs and counterparty considerations.
A Simple Small-Account Withdrawal Formula
Use this calculation before confirming a withdrawal:
Effective fee percentage = (broker fee + processor fee + bank/intermediary fee + conversion cost) ÷ withdrawal amount × 100
For example, if total costs are $18 on a $300 withdrawal:
$18 ÷ $300 × 100 = 6%
If the same $18 cost applies to a $3,000 withdrawal:
$18 ÷ $3,000 × 100 = 0.6%
The absolute cost is identical, but the effect on the account is completely different.
Final Takeaway
Forex withdrawal fees matter more for small trading accounts because fixed charges consume a larger percentage of smaller withdrawals. A $20 fee may look minor on a $5,000 payout but represents 4% of a $500 withdrawal.
Small-account traders should therefore evaluate the complete withdrawal cost: broker fees, payment-processing charges, currency-conversion spreads, intermediary costs and receiving-bank charges where applicable.
The most useful number is not the advertised withdrawal fee. It is the percentage of your withdrawal that disappears before the money reaches you.
FAQs
Why are withdrawal fees more expensive for small accounts?
Usually because fixed fees represent a larger percentage of a small withdrawal. The dollar fee may be identical, but its impact on the payout is greater.
Is a zero withdrawal fee always better?
No. A provider may charge no explicit withdrawal fee but use a less favourable currency-conversion rate. Compare the final amount received.
Should I combine small withdrawals?
If fixed fees apply per transaction, combining withdrawals can reduce the percentage cost. But consider your cash-flow needs, provider limits and risk considerations.
Can currency conversion cost more than the withdrawal fee?
Yes. A spread or markup embedded in the exchange rate can create a larger economic cost than the visible withdrawal charge.
Does this matter for Indian traders receiving USD?
Yes. When USD or another foreign currency is converted into INR, the applied exchange rate and any additional charges determine the amount that ultimately reaches the Indian bank account.
How should I measure my real withdrawal cost?
Record the foreign-currency amount requested, every fee, the applied conversion rate and the final bank credit. Then calculate the total cost as a percentage of the original withdrawal.
Educational content only. Withdrawal fees, exchange rates, bank charges and payment-provider policies vary and can change. Always check the current terms applicable to your transaction.
[…] guide on why forex withdrawal fees matter more for small trading accounts covers this percentage effect in more […]
[…] complete cost rather than looking at the rupee fee in isolation. TradeOG’s related guide on why forex withdrawal fees matter more for small trading accounts covers this effect in greater […]