Indian traders receiving prop firm payouts usually come across two common routes: USDT/crypto payout and bank transfer. At first glance, the choice looks simple—crypto can move through a wallet, while a bank transfer goes through the banking system. In practice, however, the important differences are the payment route, fees, conversion process, documentation, compliance checks and tax record-keeping.
This guide explains USDT vs bank transfer for prop firm payouts in India in 2026 in simple language, including how each route works, what records to keep, what can happen when money reaches an Indian bank account, and why the payment method alone does not determine the tax treatment.
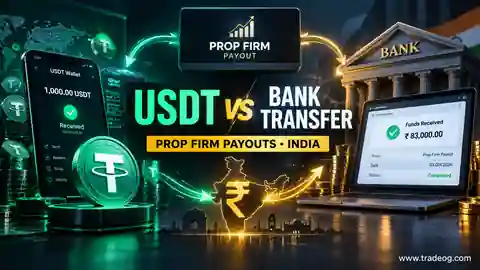
USDT vs Bank Transfer: What Is the Difference?
The basic difference is the route taken between the prop firm and your final INR balance.
- Bank transfer: Prop firm or payment provider → banking/payment channel → currency conversion where applicable → Indian bank account.
- USDT: Prop firm → USDT wallet/platform → conversion or sale where applicable → INR withdrawal → Indian bank account.
A bank transfer can therefore provide a more direct banking trail. A USDT payout adds a digital-asset transaction layer, which means you should preserve both the prop-firm payout record and the blockchain/conversion records.
How a Bank Transfer Prop Firm Payout Works
- You complete the prop firm’s payout requirements.
- The prop firm approves the payout.
- The firm or its payment provider initiates the supported payment.
- The payment moves through the relevant banking or payment network.
- The receiving bank or provider may perform KYC, source-of-funds or other applicable checks.
- If the payment is in a foreign currency, conversion into INR may take place.
- The net amount is credited to your Indian bank account.
For international receipts, a bank may ask for information about the source or purpose of the transaction. RBI guidance explains the role of authorised dealer banks in foreign-exchange transactions and FEMA-related compliance. Traders should provide genuine information and documents rather than selecting a description simply because it appears convenient.
For a broader step-by-step explanation, see Prop Firm Payout to Indian Bank Account: Complete Process.
How a USDT Prop Firm Payout Works
- The prop firm approves your payout.
- You provide the supported wallet address and, where required, the correct USDT network.
- The prop firm sends USDT to the specified wallet.
- You verify the transaction and retain the transaction hash.
- You use a supported route to convert or sell the USDT when you want INR.
- The resulting INR is withdrawn to your bank account, where applicable.
- You keep the complete trail from the original payout to the final bank credit.
The key operational point is that USDT introduces an additional record trail. You may need the prop-firm payout confirmation, wallet details, blockchain transaction, conversion/sale statement, fees and final bank-credit record.
You can also read Crypto vs Bank Transfer for Prop Firm Payouts for a broader process comparison.
USDT vs Bank Transfer for Indian Traders
| Factor | USDT | Bank Transfer |
|---|---|---|
| Basic route | Prop firm → USDT wallet/platform → conversion → bank | Prop firm/payment provider → banking channel → bank |
| Extra transaction layer | Blockchain and digital-asset conversion | Usually no blockchain layer |
| Documentation | Payout proof + wallet/blockchain + conversion + bank records | Payout proof + payment/remittance + bank records |
| Possible fees | Network, platform, spread and withdrawal costs may apply | Transfer, intermediary, FX spread and bank charges may apply |
| Conversion | USDT may need to be converted into INR | Foreign currency may be converted by the provider/bank |
| Main operational risk | Wrong network/address or incomplete crypto records | Bank/payment processing, verification or documentation requests |
| Record reconciliation | More transaction steps to reconcile | Often a simpler bank-based trail |
Which Route Is Easier to Track?
For simple record keeping, a direct bank payout can be easier to reconcile because the final receipt appears directly in your banking records. USDT can require more documentation because there may be several linked events between the prop-firm payout and the final INR withdrawal.
That does not mean USDT is automatically problematic. It means you should keep the complete transaction trail and avoid mixing payout records with unrelated personal crypto transactions.
USDT Conversion to INR: Why the Record Matters
USDT is a virtual digital asset under India’s tax framework. The Income Tax Department provides specific guidance for income from transfer of Virtual Digital Assets (VDAs), including the Section 115BBH regime and Schedule VDA in applicable income-tax returns.
However, it is too simplistic to say that every prop firm payout received in USDT is automatically taxed at 30%. The underlying prop-firm payout and a later VDA transaction are not necessarily the same tax question. The actual treatment depends on the contractual arrangement, nature of the income, residency, the digital-asset transaction and the taxpayer’s complete facts.
For that reason, keep:
- Original prop-firm payout amount and approval.
- Date of the payout.
- USDT quantity received.
- Wallet address and transaction hash.
- Conversion/sale details.
- INR value used in your records.
- Trading/conversion/withdrawal fees.
- Final INR bank credit.
For tax-specific treatment, use the latest Income Tax Department guidance and consult a qualified Indian tax professional for your circumstances.
Is a Bank Transfer Automatically Tax-Free?
No. The payment method does not by itself make an income tax-free.
If you are an Indian resident receiving income connected with a foreign source, the applicable reporting can depend on the nature of the income and your overall tax position. The Income Tax Department provides Schedule FSI for reporting foreign-source income and Schedule FA for specified foreign assets/accounts for applicable residents.
The appropriate income-tax return also depends on the taxpayer’s complete income profile. Do not select an ITR form solely because a payout arrived through a bank or USDT.
Documents to Keep for a Bank Transfer Payout
- Prop firm payout approval or payout statement.
- Prop firm account statement.
- Contract or other relevant commercial documentation, where applicable.
- Payment-provider confirmation.
- Bank statement showing the incoming amount.
- Foreign-currency conversion details.
- Bank/remittance advice or other supporting certificate, where supplied.
- Correspondence with the bank about source or purpose of funds, if any.
Documents to Keep for a USDT Payout
- Prop firm payout approval.
- Prop firm account statement.
- Wallet address used to receive the payout.
- Blockchain transaction hash/explorer record.
- USDT quantity received.
- Date and time of the transaction.
- Conversion or sale statement.
- INR conversion value and fees.
- Final bank statement showing the INR withdrawal.
USDT vs Bank Transfer: Which Has More Fees?
There is no universal answer because the actual cost depends on the prop firm, payment provider, bank, exchange/platform, blockchain network and conversion route.
For USDT, possible costs can include network fees, platform fees, trading spread and withdrawal charges. For bank transfers, possible costs can include transfer fees, intermediary-bank charges, foreign-exchange spread and receiving-bank charges.
Instead of comparing only the advertised payout fee, calculate the net INR amount actually received.
Example: A ₹1,00,000 Equivalent Payout
Assume, only for illustration, that a prop-firm payout has a value of approximately ₹1,00,000 at the relevant conversion rate. The actual amount will vary with exchange rates, fees and the payment route.
| Route | Typical record trail | What to reconcile |
|---|---|---|
| Bank transfer | Payout approval → payment/remittance → bank credit | Gross payout, conversion rate, charges and net INR |
| USDT | Payout approval → blockchain receipt → conversion/sale → bank credit | USDT amount, transaction hash, conversion value, fees and net INR |
This example does not calculate tax. It only shows why the documentation trail can look different for the two routes.
What If Your Bank Asks About the Source of Funds?
Answer accurately and provide genuine supporting documents. If the funds are a prop-firm payout under a contractual arrangement, describe the transaction accurately and provide the payout statement or other relevant evidence.
Do not create a fake invoice, false payment description or incorrect purpose just to make a transaction easier to process. If your bank requests additional information, ask exactly which document or declaration it requires and provide the genuine record.
Common Mistakes Indian Traders Should Avoid
- Assuming USDT automatically means a 30% tax on the entire payout.
- Assuming a bank transfer is automatically tax-free.
- Deleting wallet transaction history after conversion.
- Keeping only the final bank statement and losing the original payout proof.
- Using the wrong USDT blockchain network or wallet address.
- Ignoring conversion spreads and withdrawal charges.
- Giving the bank an inaccurate source-of-funds description.
- Mixing prop-firm payout records with unrelated personal crypto activity.
- Choosing an ITR form without considering the complete income profile.
- Relying on old tax or regulatory information without checking the current rules.
A Simple Payout Record-Keeping System
Create one digital folder for every payout. A useful structure is:
- Payout request and approval.
- Prop firm account statement.
- Payment-provider or bank confirmation.
- Wallet transaction hash, if USDT was used.
- Conversion/sale statement.
- Bank credit entry.
- INR calculation and fees.
- Tax working papers.
This makes reconciliation much easier months later and reduces the risk of losing evidence when a bank, accountant or tax professional asks about a transaction.
USDT vs Bank Transfer: Quick Checklist
| Question | USDT | Bank Transfer |
|---|---|---|
| Keep payout proof? | Yes | Yes |
| Keep transaction records? | Yes, including blockchain records | Yes, including bank/payment records |
| Can fees reduce the final INR? | Yes | Yes |
| Can tax questions arise? | Yes | Yes |
| Does the payment method alone determine tax? | No | No |
Frequently Asked Questions
Is USDT better than a bank transfer for prop firm payouts?
They are different payment routes. The relevant comparison depends on the prop firm’s supported methods, fees, processing route, documentation requirements and your ability to maintain complete records. There is no single route that is suitable for every trader.
Can Indian traders receive prop firm payouts in USDT?
Some prop firms and payment providers support USDT or other digital-asset payout routes, while others do not. The available method depends on the specific provider and its current payout terms. Always check the firm’s current official payout policy.
Does receiving USDT automatically mean the entire payout is taxed at 30%?
No automatic conclusion should be made from the payment method alone. Section 115BBH relates to income from transfer of VDAs. The underlying prop-firm payout can raise a separate classification question, so the complete facts and transaction trail matter.
Is a prop firm payout to an Indian bank account tax-free?
No. Receiving money through a bank does not by itself make the underlying income tax-free. The tax treatment depends on the nature and classification of the income and the taxpayer’s circumstances.
What should I keep for a USDT payout?
Keep the prop-firm payout approval, account statement, receiving wallet address, blockchain transaction hash, USDT quantity, conversion/sale statement, fees and final INR bank-credit record.
What should I do if my bank asks for proof of the payout?
Provide genuine documents that explain the transaction, such as the prop-firm payout statement and payment record. If the bank requests a specific declaration or supporting document, ask the bank what it requires and respond with accurate information.
Final Takeaway
USDT and bank transfer are different payout rails, not different methods of avoiding tax. A bank transfer can create a more direct banking trail, while USDT adds a blockchain and conversion layer that requires additional documentation. For Indian traders, the practical priority is to maintain a complete record from the prop firm’s payout approval through the final INR receipt and to have the underlying income and any separate VDA transaction classified correctly.
Official References
- Income Tax Department – ITR-2 guidance
- Income Tax Department – FSI/FA guide
- Income Tax Department – Foreign Assets and Income brochure
- Reserve Bank of India – FEMA/foreign exchange FAQ
Disclaimer: This article is for general educational information only and is not tax, legal, FEMA, banking or financial advice. Prop-firm payout arrangements differ by provider. Tax treatment can depend on the contractual relationship, nature of income, residential status, VDA transactions, foreign-source income, documentation and other facts. Check current official rules and consult a qualified Indian tax professional for advice on your specific circumstances.