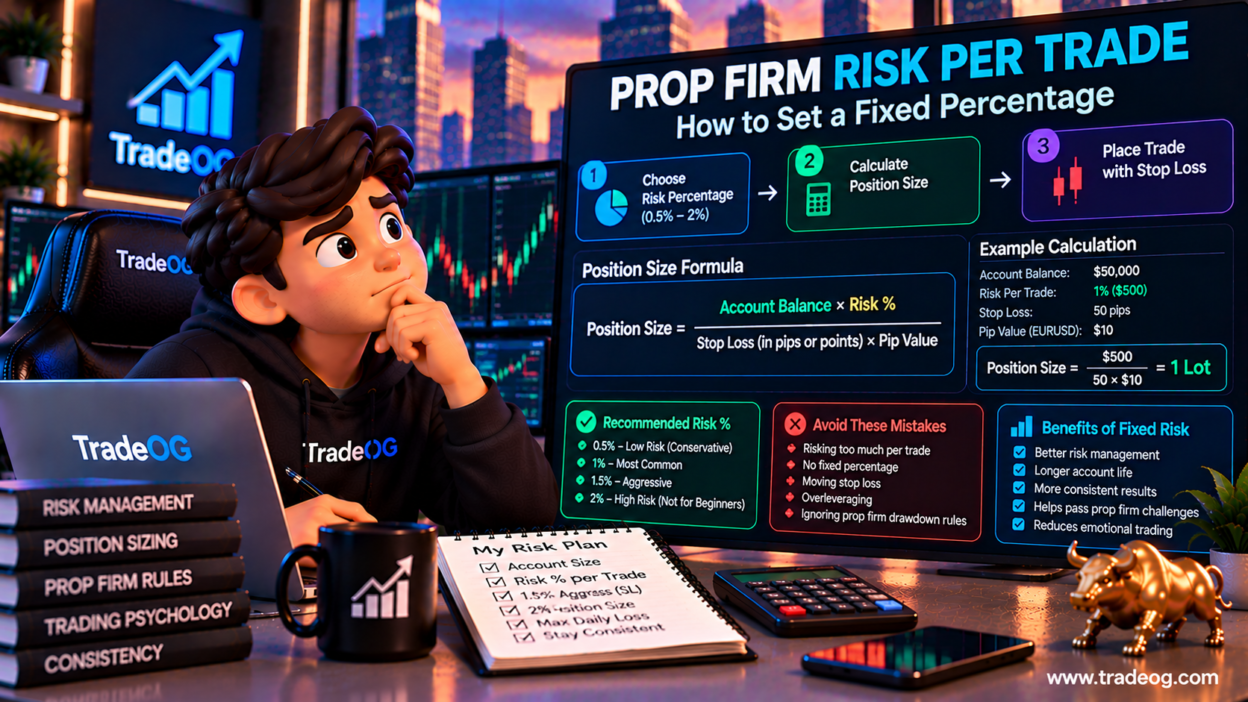
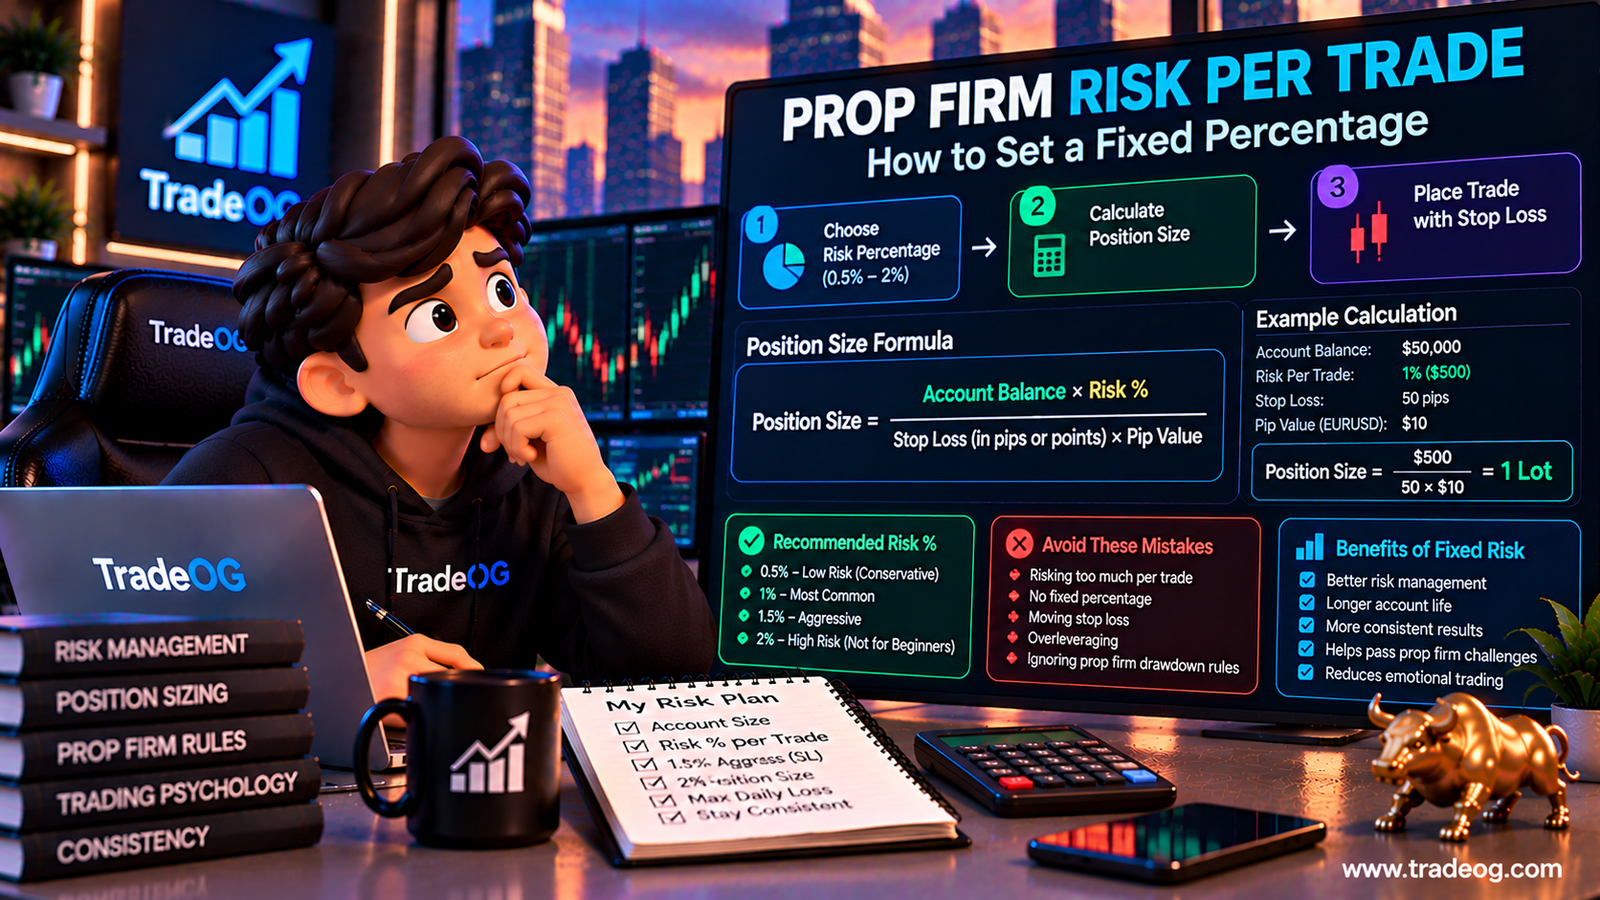
One of the simplest ways to make prop trading more consistent is to decide how much of the account you are willing to risk before you enter a trade. Instead of changing your position size based on confidence, recent wins, or the size of the setup, you can use a fixed percentage risk model.
The idea is straightforward: choose a risk percentage, convert it into a dollar amount, calculate the position size from the stop-loss distance, and keep that process consistent.
But there is an important detail that many traders miss: a fixed percentage does not mean you can ignore the prop firm’s drawdown rules. Your personal risk limit should fit inside the account’s actual loss allowance, leaving room for losing streaks, slippage and execution differences.
What Does Risk Per Trade Mean?
Risk per trade is the maximum planned amount you are willing to lose if a trade reaches its stop-loss.
For example, if your risk plan allows $100 per trade, a properly sized position should be structured so that a stop at the planned level represents approximately $100 of risk before any unexpected slippage or additional costs.
Risk per trade is different from:
- Account balance
- Margin requirement
- Position size
- Daily loss limit
- Maximum drawdown
- Profit target
These numbers interact, but they are not interchangeable.
What Is Fixed Percentage Risk?
With a fixed-percentage approach, you choose a percentage of a defined account value and use it to establish your maximum planned loss.
The basic formula is:
Risk Amount = Account Value × Risk Percentage
For a hypothetical $50,000 account:
- 0.25% risk = $125
- 0.50% risk = $250
- 1% risk = $500
- 1.5% risk = $750
- 2% risk = $1,000
These are mathematical examples, not universal prop-firm recommendations. The appropriate percentage depends on the firm’s drawdown structure, your strategy, volatility, trading frequency and personal risk tolerance.
Fixed Dollar Risk vs Fixed Percentage Risk
There are two common ways traders define their risk plan.
Fixed Dollar Risk
You risk the same dollar amount on every trade. For example, every trade is planned around a maximum loss of $100.
Fixed Percentage Risk
You risk the same percentage of a defined account value. If the reference account value changes, the dollar risk changes with it.
For prop traders, it is important to define exactly which account value you are using. You might base your calculation on the initial account size, current balance, current equity, or remaining drawdown. Those approaches produce different results.
The Most Important Decision: What Is Your Risk Base?
Before calculating position size, write down the number that your percentage applies to.
For example:
Risk Base = $50,000 starting account
Risk Percentage = 0.5%
Maximum Planned Risk = $250
If instead you recalculate 0.5% from current equity after every trade, the dollar risk changes as the account changes.
Neither method should be treated as universally correct. The key is consistency and making sure the chosen method does not conflict with the prop firm’s rules.
How to Calculate Risk Per Trade Step by Step
Step 1: Choose a Risk Percentage
Start with a percentage that leaves substantial room between your normal trade risk and the account’s drawdown limit.
For example, you might test a plan using 0.25%, 0.5% or 1% as hypothetical risk levels and compare how many consecutive losses the account could withstand.
Do not choose a percentage simply because another trader uses it. Your strategy’s losing streak, average trade frequency and execution characteristics matter.
Step 2: Calculate the Dollar Risk
Use:
Dollar Risk = Risk Base × Risk Percentage
Example:
$50,000 × 0.5% = $250 planned risk
Step 3: Determine Your Stop Distance
Your stop should come from the trade setup and market structure rather than being placed at an arbitrary distance simply to fit a position size.
For example, suppose an MNQ trade has a planned stop 50 points away.
Step 4: Calculate Risk Per Contract
For a futures contract, a simplified calculation is:
Risk Per Contract = Stop Distance × Dollar Value Per Point
If the risk per contract is $100 and your maximum planned risk is $250:
$250 ÷ $100 = 2.5 contracts
Because you cannot trade half a contract in this example, you would need to round down to a position that stays within the planned risk, or adjust the setup if your trading rules permit it.
Step 5: Check the Prop Firm’s Contract Rules
Your mathematical position size is not automatically your permitted position size.
Check the firm’s current rules for:
- Maximum contracts
- Mini and Micro contract limits
- Instrument restrictions
- Daily loss rules
- Maximum loss or drawdown
- Volatility restrictions
- News or session rules
The final position size must satisfy both your own risk plan and the firm’s rules.
Example: Fixed Percentage Risk on a $50K Account
Suppose you use a hypothetical $50,000 starting balance and choose 0.5% planned risk.
Risk Amount = $50,000 × 0.005 = $250
Now assume your selected futures setup has a stop distance that creates $80 of risk per contract.
You can calculate:
$250 ÷ $80 = 3.125 contracts
You cannot place 3.125 contracts, so you would round down to 3 contracts.
Planned risk would then be approximately:
3 × $80 = $240
That leaves approximately $10 of room before the planned $250 risk level, although real execution can differ because of slippage and other costs.
Why Position Size Should Change When the Stop Changes
This is one of the most important parts of fixed-risk trading.
Suppose your maximum planned risk is $250.
If your stop is close, you can potentially use more contracts while staying near the same dollar risk. If your stop is wider, the number of contracts needs to decrease.
That means position size should normally respond to stop distance, rather than keeping the same number of contracts on every trade regardless of market structure.
A fixed number of contracts is not the same thing as fixed percentage risk.
Fixed Percentage Risk Does Not Mean Fixed Loss
Even if you calculate the position perfectly, the actual loss can differ from the planned risk.
Reasons include:
- Slippage
- Fast market movement
- Gaps
- Partial fills
- Spread changes
- Manual intervention
- Moving the stop
For that reason, treat your calculated risk as a planned risk limit, not a guarantee of the exact final loss.
How Many Losing Trades Can Your Risk Model Survive?
Before using a percentage, run a simple losing-streak calculation.
Suppose your risk is 0.5% per trade and you experience ten consecutive losses, with each loss exactly matching the planned risk.
The simple arithmetic loss would be approximately:
10 × 0.5% = 5%
Real account behavior can differ depending on whether your risk is calculated from a fixed starting value or recalculated from changing equity.
This exercise is useful because it forces you to think about your strategy’s losing streak rather than focusing only on its average trade.
Risk Per Trade vs Prop Firm Drawdown
This is where prop trading differs from ordinary percentage-risk calculations.
If your account has a $2,500 maximum loss allowance, risking 1% of a $50,000 starting value means $500 of planned risk per trade. Five full losses would consume the entire theoretical allowance before considering slippage or any other account activity.
That does not mean five losses will actually breach every prop account. Different firms use different drawdown mechanisms, and some use daily limits, trailing thresholds or other conditions.
The point is to calculate your risk against the actual loss buffer available under your specific account rules.
A Better Way to Think About Risk Percentage
Instead of asking, “What percentage should every prop trader use?” ask:
- How large is my actual drawdown buffer?
- How many consecutive losses can my plan tolerate?
- What is my strategy’s historical losing streak?
- How often do I trade?
- How much slippage can occur in my market?
- Does my position size stay within the firm’s limits?
- Will my risk remain manageable during high-volatility sessions?
This produces a more useful risk framework than copying a percentage from another trader.
Should You Use 0.5%, 1% or 2%?
There is no single percentage that is appropriate for every prop trader.
A smaller percentage generally creates more room for consecutive losses, while a larger percentage increases the dollar impact of every losing trade.
For example, on a hypothetical $50,000 reference value:
| Risk % | Planned Risk | Losses Equal to $2,500 Buffer* |
|---|---|---|
| 0.25% | $125 | 20 |
| 0.50% | $250 | 10 |
| 1.00% | $500 | 5 |
| 1.50% | $750 | 3.33 |
| 2.00% | $1,000 | 2.5 |
*Simplified arithmetic assuming every loss equals exactly the planned risk and ignoring compounding, slippage, fees and account-specific rules. It is an illustration, not a prop-firm rule.
The table shows why percentage selection should be connected to drawdown capacity.
Fixed Risk During a Losing Streak
One advantage of a predefined risk model is that it can prevent emotional position sizing.
Without a rule, a trader might increase size after a loss because they want to recover the account quickly. That changes the risk profile precisely when the account is already under pressure.
A fixed-risk plan creates a mechanical boundary:
Loss → same predefined risk → next valid setup
The purpose is not to guarantee recovery. It is to prevent a losing streak from automatically turning into an even larger risk-taking streak.
Do Not Increase Risk Just Because You Are Profitable
The opposite problem can happen after a strong winning streak.
A trader may become more confident and increase position size without changing the underlying strategy. If the next few trades lose, the account can give back a meaningful portion of the previous gains.
If you want to increase risk after reaching a specific account milestone, define the rule before trading rather than making the decision emotionally during a session.
Fixed Percentage Risk and Different Futures Contracts
Different futures contracts have different dollar values per point and tick. That means the same stop distance can create very different dollar risk.
For example, two setups can both use a 20-point stop while producing very different dollar risk because the contracts have different specifications.
Always calculate risk from the actual contract you are trading rather than assuming that the same number of points means the same amount of money across markets.
What About Micro Futures?
Micro contracts can provide smaller position increments than their larger counterparts, which can make risk sizing more granular.
That can be useful when your calculated risk falls between the available contract sizes.
However, Micro does not automatically mean that a trade is safe. You still need to calculate:
- Stop distance
- Dollar value per point
- Number of contracts
- Total planned risk
- Remaining drawdown
Fixed Risk vs Maximum Daily Loss
Your per-trade risk and daily loss limit should be treated as separate controls.
For example, a trader might plan to risk $250 per trade while also setting a personal daily stop of $500. After two full losses, trading stops for the day even though the prop firm’s official daily limit may be larger.
A personal limit can be stricter than the firm’s limit. It should not be designed around using the firm’s maximum allowed loss as your normal trading budget.
A Simple Fixed-Percentage Risk Plan
Use this framework as a starting template and adapt it to your account rules:
- Define the risk base. Decide whether the percentage is based on starting balance, current equity or another clearly defined value.
- Choose a conservative risk percentage. Base it on drawdown capacity and your historical losing streak.
- Calculate the dollar limit. Multiply the risk base by the percentage.
- Set the technical stop. Place the stop where the trade thesis is invalidated.
- Calculate position size. Divide maximum planned risk by risk per contract.
- Round down when necessary. Do not exceed the planned risk simply to use another contract.
- Check prop-firm rules. Confirm contracts, instruments, daily limits and other restrictions.
- Record the trade. Log planned risk versus actual loss.
Track Planned Risk vs Actual Risk
Your trading journal should contain both numbers.
| Journal Metric | Example |
|---|---|
| Risk Base | $50,000 |
| Risk Percentage | 0.50% |
| Planned Risk | $250 |
| Stop Distance | 50 points |
| Contracts | 3 |
| Expected Loss at Stop | $240 |
| Actual Loss | $265 |
| Difference | $25 |
If the difference between planned and actual risk repeatedly becomes large, investigate execution, slippage, stop movement or position-size calculations.
Common Fixed-Percentage Risk Mistakes
- Using the headline account size without checking drawdown: A $50,000 account label does not necessarily mean you have $50,000 of loss capacity.
- Using the same contract count on every setup: Different stop distances create different dollar risks.
- Moving the stop farther away: This increases actual risk without changing the original calculation.
- Adding to losing positions: Additional contracts can push total risk beyond the original percentage.
- Ignoring slippage: The actual loss can exceed the planned stop loss.
- Copying another trader’s percentage: Risk should fit your own drawdown and strategy.
- Using the prop firm’s maximum loss as your normal risk budget: A firm’s limit is a boundary, not a recommended amount to lose.
- Changing the formula mid-month: Inconsistent risk rules make performance analysis harder.
Fixed Percentage Risk and Expectancy
Risk percentage also changes how your strategy’s expectancy translates into dollars.
Suppose a strategy historically produces an expectancy of +0.30R per trade. If 1R equals $100, the historical average is approximately +$30 per trade before considering how future results differ from the historical sample.
If 1R equals $500, the same +0.30R becomes approximately +$150 per trade.
The strategy’s R expectancy has not changed. The dollar exposure has.
This is why increasing risk percentage can increase both the potential dollar result and the dollar impact of losing streaks.
Frequently Asked Questions
What is a good risk percentage per trade for prop trading?
There is no universal percentage. Choose a level that fits your strategy, historical losing streak, drawdown buffer, trading frequency and the specific prop firm’s rules.
Should risk be based on the $50K account size?
Not automatically. Determine what the account’s drawdown mechanism actually allows and define your risk base clearly. The nominal account size and the amount you can lose before a breach are not necessarily the same number.
Can I risk 1% per trade in a prop firm account?
Mathematically, you can calculate 1% of a defined reference balance, but whether that risk is appropriate depends on the account’s drawdown, your strategy and the firm’s rules. Calculate how a normal losing streak would affect the available buffer before adopting the percentage.
Should I use the same percentage after a loss?
If your plan is based on fixed risk, the answer should be predetermined. Do not increase risk simply to recover a previous loss. If your percentage is calculated dynamically from equity, the dollar amount may change automatically, so document that methodology.
Is fixed percentage risk better than fixed dollar risk?
Neither is universally better. Fixed dollar risk provides a constant monetary exposure, while fixed percentage risk changes dollar exposure as the chosen reference value changes. The more important requirement is that the method is defined, measurable and compatible with your drawdown rules.
Final Takeaway
A fixed percentage risk model gives prop traders a simple way to control position size:
Risk Amount = Risk Base × Risk Percentage
Then convert that dollar risk into a position size using the stop distance and contract value.
The key is not finding a magical percentage. It is building a risk number that leaves enough room for normal losing streaks, execution differences and the prop firm’s actual drawdown structure.
Keep the process mechanical: define the risk base, calculate the dollar limit, place the technical stop, size the position, check the firm’s rules and record planned versus actual risk.
That approach makes your risk measurable—and makes it much easier to review whether your trading process is actually consistent over time.