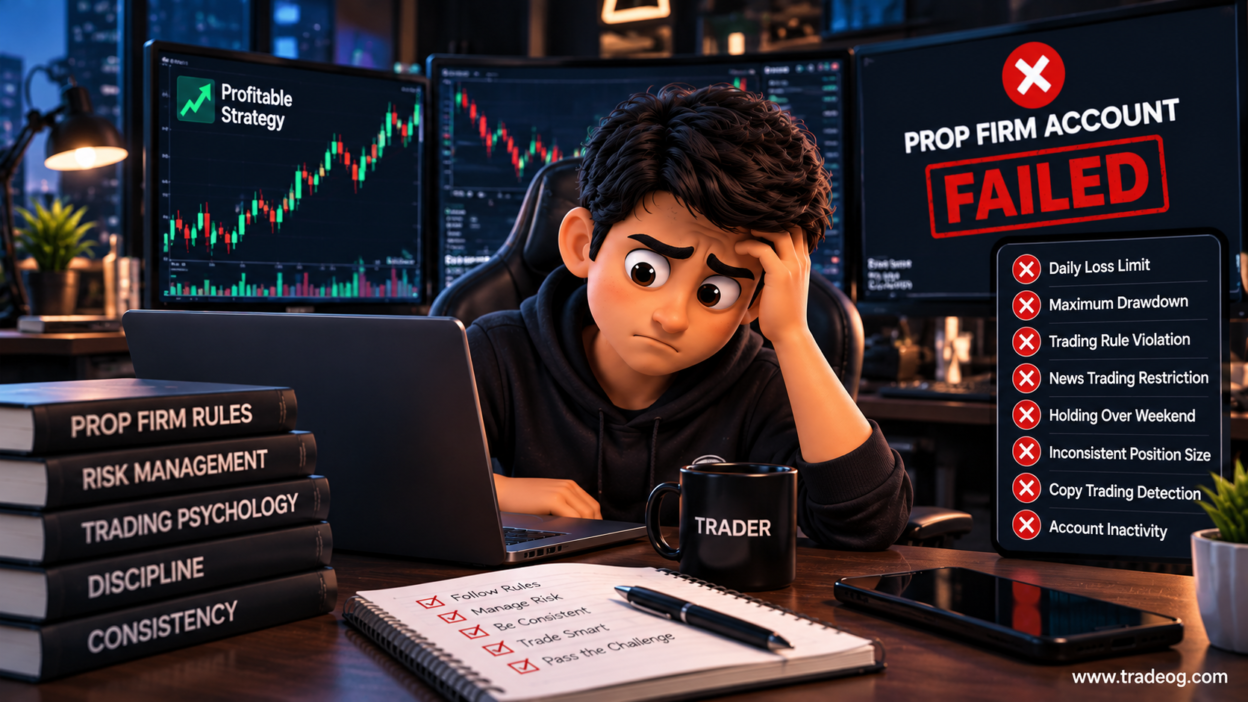
A profitable trading strategy does not automatically mean a prop firm account will survive. This is one of the most important differences between trading your own account and trading under a proprietary trading firm’s risk framework.
You can have a strategy with a genuine statistical edge, a positive expectancy and profitable backtesting, yet still fail an evaluation or lose a funded account because the way you execute the strategy conflicts with the firm’s account rules.
The problem is usually not that the strategy stopped working. It is that strategy profitability and rule compliance are two different things.
Profitability Is Not the Same as Account Survival
When traders evaluate a strategy, they often focus on win rate, average reward-to-risk ratio, drawdown and total return. A prop firm evaluates something broader: whether your trading behaviour stays inside its permitted risk limits.
For example, a strategy might make 8% over a large sample while occasionally producing a 7% drawdown. If a particular prop firm’s maximum drawdown is 6%, that strategy can be profitable in the long run but still be unsuitable for that account.
The key question is therefore not only “Does my strategy make money?” but also “Can my strategy make money without violating the account’s rules?”
1. Your Maximum Drawdown Can Be Too Large
Maximum drawdown is one of the most common reasons a profitable strategy can fail a prop firm account.
A strategy may recover from deep temporary losses when traded with sufficient capital and time. A prop firm account may not give you that room. If the account has a relatively tight maximum loss threshold, a normal losing streak can end the account before the strategy has an opportunity to recover.
This creates a practical distinction between strategy drawdown and allowed account drawdown. Your historical drawdown must fit comfortably inside the firm’s current limit rather than merely staying below it on paper.
2. Daily Loss Limits Can Stop a Good Strategy
A strategy can be profitable over weeks or months while still having individual days with losses larger than a firm’s daily loss allowance.
Imagine a system that has positive expectancy but occasionally loses 2.5% during a volatile session. If the account’s daily loss limit is 2%, that trading day can become an account failure even if the strategy later recovers.
This is why traders should measure their historical worst trading day, not just their average daily result.
3. Position Sizing May Be Too Aggressive for the Rules
Many traders increase position size because their strategy has a high win rate. The problem is that a high win rate does not eliminate losing streaks.
If position sizing is too aggressive, a few consecutive losses can breach a daily loss limit or maximum drawdown before the statistical edge has time to play out.
A strategy that works with 1% account risk per trade may become unsuitable when the same entries are traded at 3% or 4% risk.
4. A Profitable Strategy May Have Poor Risk-of-Ruin Characteristics
Two strategies can generate the same return while having completely different risk profiles.
For example, Strategy A may make money through many small gains and controlled losses. Strategy B may produce long periods of small gains followed by occasional large losses. Both can look profitable in a backtest, but Strategy B may be much harder to operate under a strict prop firm drawdown model.
Traders should examine losing streaks, consecutive losses, peak-to-valley drawdown, daily loss distribution and recovery time—not just net profit.
5. The Strategy May Conflict With Trading Restrictions
A profitable setup can still become a problem if the prop firm’s rules restrict certain trading behaviour.
Depending on the firm’s current terms and account type, restrictions may apply to areas such as news trading, weekend holding, overnight exposure, certain execution methods, copy trading, prohibited strategies or other forms of trading activity.
These rules are firm-specific and can change. Always read the current rulebook for the exact account you are trading rather than relying on a general list found online.
6. Holding Trades Through News Can Change the Risk Profile
A strategy may perform well during normal market conditions but behave very differently around major economic releases.
News events can create rapid price movements, wider spreads and execution conditions that differ significantly from ordinary sessions. If a firm’s rules restrict trading around specific news events, an otherwise profitable system may become incompatible with the account.
Even where news trading is permitted, traders should test whether their historical results depend heavily on those high-volatility periods.
7. Weekend and Overnight Rules Matter
Some strategies rely on holding positions for long periods. A trader may therefore assume that a profitable swing setup can be transferred directly to a prop account.
That assumption can be wrong if the account has restrictions around weekend positions, market closures or specific holding periods.
Before using a swing strategy, check whether its required holding time fits the firm’s current trading conditions.
8. Your Strategy May Need More Capital Than the Account Rules Allow
Capital requirements are often overlooked. A strategy may need a certain amount of drawdown room to survive its normal losing periods.
If your historical system needs a 10% risk buffer but the prop account permits only a 5% maximum drawdown, the strategy is effectively undercapitalised for that environment.
This does not necessarily mean the strategy is bad. It means the strategy-to-account fit is poor.
9. Scaling Up Too Quickly Can Break the System
Another common mistake is increasing position size after a few winning trades.
A trader may start with conservative risk, build confidence after a profitable week and then double the size. A normal losing sequence can suddenly have a much larger effect on the account.
Risk should normally be based on a predefined plan rather than recent profits or emotions.
10. Correlated Positions Can Create Hidden Risk
Opening several trades can look diversified when the positions are actually exposed to the same underlying market driver.
For example, multiple positions involving closely related instruments can lose together during one market move. If each trade is sized independently, total portfolio exposure may become much larger than the trader realises.
When evaluating a prop strategy, calculate risk at the portfolio level rather than looking only at each individual trade.
11. Execution Differences Can Turn a Backtest Into a Different Strategy
A backtest assumes specific entry, exit and execution conditions. Live trading can produce different spreads, slippage, fills and timing.
These differences matter particularly for strategies that use tight stop losses or trade frequently. A small increase in execution cost can reduce the expected edge.
Before using a strategy on a prop account, compare backtested assumptions with realistic live or simulated execution data.
12. Psychological Pressure Can Change Your Execution
Trading a personal account and trading an evaluation account can feel completely different.
Once a trader starts thinking about passing a challenge, avoiding a daily loss limit or protecting a funded account, normal decision-making can change. Traders may close winners too early, move stop losses, increase size after losses or avoid valid setups.
The strategy can remain profitable while the trader’s execution becomes inconsistent.
How to Test Whether Your Strategy Fits a Prop Firm
Before committing to an account, create a simple compatibility test.
- Measure historical maximum drawdown. Compare it with the firm’s maximum drawdown and leave a meaningful safety buffer.
- Measure the worst daily loss. Check whether normal losing days can breach the daily limit.
- Count maximum consecutive losses. Size positions so a normal losing streak does not create an account-threatening drawdown.
- Review holding periods. Identify trades that may conflict with overnight or weekend conditions.
- Review news exposure. Determine how much of the strategy’s performance comes from high-impact events.
- Calculate portfolio exposure. Treat correlated trades as a combined risk rather than separate bets.
- Stress-test the strategy. Increase spreads, add slippage and simulate losing streaks beyond the historical sample.
- Build a rule checklist. Confirm every operational requirement before trading the account.
A Simple Example
Suppose a strategy has a long-term positive expectancy and historically produces a 5% maximum drawdown. A trader might assume it is safe on any account with a larger headline drawdown allowance.
But suppose the trader increases position size by 50%, experiences a worse-than-average losing streak and holds multiple correlated positions at the same time. The effective drawdown can become much larger than the original backtest suggests.
The strategy did not necessarily fail. The implementation failed to respect the risk budget of the account.
How to Reduce the Chance of a Prop Firm Account Failure
The goal should not be to maximise the return of an evaluation account. The goal is to keep the strategy’s risk comfortably inside the account’s constraints.
- Use conservative risk per trade.
- Set a personal daily stop below the firm’s hard daily loss limit.
- Avoid increasing size simply because you are in profit.
- Track total exposure across correlated positions.
- Keep a record of rule-sensitive trades.
- Check the firm’s latest terms before trading around restricted events or periods.
- Use a pre-trade checklist when the account has strict restrictions.
- Stress-test the strategy before scaling it.
Final Takeaway
A profitable strategy can still fail a prop firm account because profitability is only one part of the equation. Drawdown limits, daily loss rules, position sizing, trading restrictions, correlated exposure, execution conditions and trader behaviour can all determine whether the strategy survives long enough to realise its statistical edge.
The best prop firm strategy is therefore not necessarily the one with the highest backtested return. It is the one that can generate its expected return while staying comfortably within the account’s risk and operational rules.
Disclaimer: This article is for educational purposes only and is not financial advice. Prop firm rules, account conditions and trading restrictions vary between firms and account types and may change. Always verify the current official terms before trading.