
Futures trading can look simple on a price chart: the market moves up or down by a few points, and your profit or loss changes. But for a new prop trader, one of the most important concepts to understand is futures point value. A move of one point does not have the same dollar impact on every futures contract.
The contract you trade determines how much each point is worth. That difference can materially change your stop-loss risk, daily loss exposure and remaining drawdown buffer.
What Is Futures Point Value?
Futures point value tells you how much your profit or loss changes when the futures price moves by one full index point for one contract.
The basic calculation is:
Dollar P&L = Price Movement in Points × Point Value × Number of Contracts
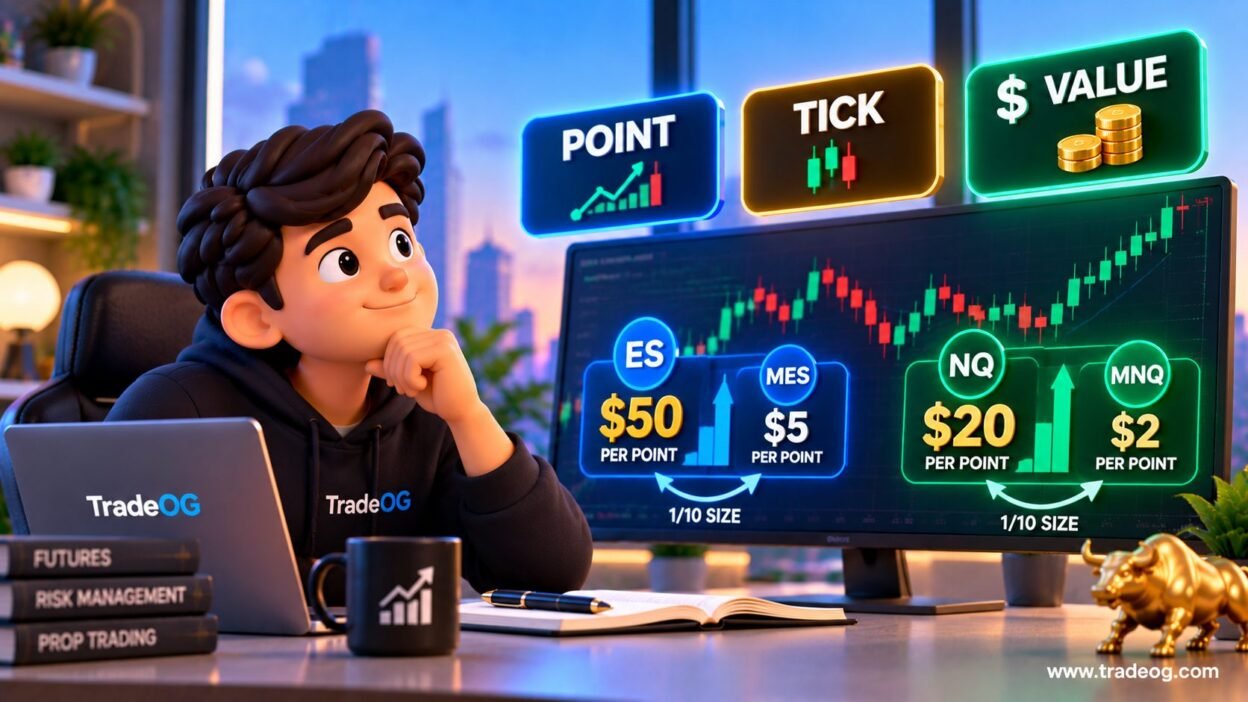
For example, CME lists the E-mini S&P 500 (ES) at $50 per index point, while the Micro E-mini S&P 500 (MES) is $5 per point. That means a 10-point move is $500 on one ES contract but $50 on one MES contract.
Point vs Tick: Do Not Mix Them Up
A point is a full index-point movement. A tick is the minimum price increment allowed for that contract.
For example, CME’s current specifications show MNQ has a 0.25-point minimum tick and a $2 multiplier. Therefore, one tick is worth $0.50 per contract. A full 1-point move is four ticks, or $2.
This distinction matters because traders sometimes say “10 ticks” when they actually mean “10 points.” The dollar difference can be significant.
Common Futures Point Values for Prop Traders
| Contract | Point Value | Typical Minimum Tick | Value Per Tick |
|---|---|---|---|
| ES | $50/point | 0.25 point | $12.50 |
| MES | $5/point | 0.25 point | $1.25 |
| NQ | $20/point | 0.25 point | $5 |
| MNQ | $2/point | 0.25 point | $0.50 |
CME describes Micro E-mini equity index futures as one-tenth the size of their larger E-mini counterparts. Its current Nasdaq-100 specifications list MNQ at $2 per point, while the larger NQ contract is $20 per point.
Example: How Much Is a 20-Point Move?
Suppose a trader buys one MNQ contract and price moves 20 points in the trader’s favor.
20 × $2 = $40 profit
If the same 20-point move happens against the position:
20 × $2 = $40 loss
Now compare one NQ contract:
20 × $20 = $400
The market moved the same number of points, but the dollar result is ten times larger because the contract multiplier is ten times larger.
Why Point Value Matters More in Prop Firm Challenges
Prop firm traders are usually working inside predefined loss and drawdown limits. That makes contract sizing directly connected to risk management.
Imagine a hypothetical account where the remaining drawdown buffer is $1,000. A trader using one MNQ contract with a 50-point stop risks:
50 × $2 = $100
With one NQ contract, the same 50-point stop would represent:
50 × $20 = $1,000
The chart setup could be identical, but the dollar risk is completely different. This is why new traders should calculate contract risk before placing an order rather than choosing a contract based only on how the chart looks.
How to Calculate Your Futures Trade Risk
Use this simple formula:
Trade Risk = Stop Distance in Points × Point Value × Contracts
Example: 30-point stop on 2 MNQ contracts:
30 × $2 × 2 = $120
Example: 8-point stop on 1 ES contract:
8 × $50 = $400
Once you know the dollar risk, compare it with your prop firm’s actual daily loss and maximum-loss rules. Those rules vary by firm and account model, so always verify the current rules before trading.
Point Value and Drawdown Buffer
Your account’s headline size does not tell you how much you can safely risk on the next trade. The more useful number is your remaining drawdown buffer.
For example, if your account has $1,500 of remaining room before its applicable loss threshold and your planned trade risks $150, the theoretical stop risk consumes 10% of that remaining buffer.
That does not mean the trade is automatically appropriate. Slippage, commissions, multiple positions and changing drawdown rules can alter the actual result. The calculation simply gives you a clearer starting point.
Why Beginners Often Miscalculate Futures Risk
- Confusing points with ticks: A 0.25-point tick is not a full point on ES, MES, NQ or MNQ.
- Ignoring contract multiplier: The same chart movement can have very different dollar consequences.
- Calculating from account size only: Remaining drawdown is often more relevant than the advertised account size.
- Forgetting multiple contracts: Risk scales with the number of contracts.
- Ignoring execution conditions: A stop order does not guarantee the exact fill price during fast markets.
ES vs MES: A Simple Risk Comparison
Because MES is one-tenth the size of ES, traders can use smaller dollar increments when sizing positions. CME gives ES a $50-per-point multiplier and MES a $5-per-point multiplier.
Consider a 12-point stop:
- 1 ES: 12 × $50 = $600
- 1 MES: 12 × $5 = $60
- 5 MES: 12 × $5 × 5 = $300
This illustrates why smaller contracts can provide more granular position sizing. However, a Micro contract is not automatically low risk. Risk still depends on the stop distance and number of contracts.
NQ vs MNQ: Another Important Example
For Nasdaq-100 futures, CME lists NQ at $20 per point and MNQ at $2 per point.
A 40-point stop therefore represents:
- 1 NQ: 40 × $20 = $800
- 1 MNQ: 40 × $2 = $80
- 4 MNQ: 40 × $2 × 4 = $320
Again, the price movement is identical. The contract multiplier changes the financial result.
A Quick Futures Point Value Checklist
- Identify the exact futures contract.
- Check the current point value and minimum tick.
- Measure your stop distance in points.
- Multiply points × point value × contracts.
- Compare the result with your remaining drawdown buffer.
- Check your prop firm’s current contract and risk restrictions.
- Allow for slippage and trading costs instead of assuming a perfect fill.
Final Takeaway
Understanding futures point value is one of the simplest ways for a new prop trader to avoid position-sizing mistakes. A point on ES is not worth the same as a point on MES, and a point on NQ is not worth the same as a point on MNQ.
Before entering a trade, calculate the dollar impact of your stop using the actual contract, point value and number of contracts. Then compare that risk with the drawdown room you actually have available. This turns a chart-based decision into a measurable risk-management decision.