

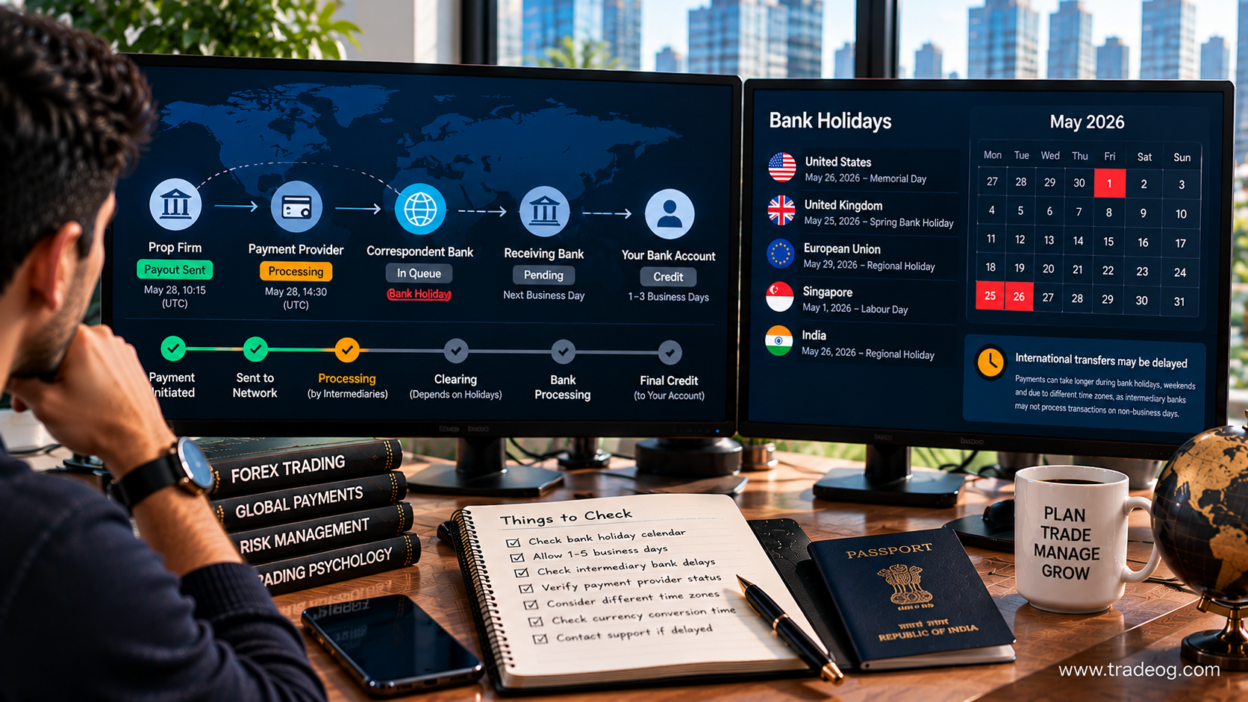
International trading payments can feel unusually slow when a bank holiday falls somewhere along the payment route. You may see a withdrawal marked as approved or sent, while the money does not appear in your bank account until the next working day or even later.
This does not necessarily mean the payment is stuck. Cross-border payments can involve the sending bank, payment provider, correspondent bank, clearing or settlement infrastructure and the receiving bank. If one of those institutions is closed for a local holiday, the transaction may wait for the next available processing window.
For traders receiving forex withdrawals, broker payments or prop firm payouts, understanding this distinction is important. A payment can move quickly through the international messaging network and still take longer to reach the final account because the last mile is governed by local banking hours and processing rules.
Why Bank Holidays Matter for International Trading Payments
A bank holiday is more than a day when a bank branch is closed. Depending on the country and payment rail, a holiday can affect payment-system operating hours, settlement cycles, treasury operations, compliance teams and the receiving bank’s ability to post incoming funds.
The Bank for International Settlements notes that differences in operating hours and holidays between jurisdictions can create delays in cross-border settlement. Its work on payment-system operating hours also highlights that many real-time gross settlement systems do not operate normally on weekends and public holidays. BIS research on cross-border payment operating hours explains why aligning those windows can improve payment speed.
This means a payment does not need to be “broken” to take longer on a holiday. It may simply be waiting for the next operating window.
The International Payment Chain Is Longer Than It Looks
When a trader withdraws money from an international broker or prop firm, the payment may follow a route similar to this:
- Broker, prop firm or payment platform approves the withdrawal.
- The sending institution creates the payment instruction.
- The payment enters the relevant banking or payment network.
- An intermediary or correspondent bank may process the payment.
- The receiving bank receives the payment information and funds.
- The receiving bank performs its own checks and posts the credit.
Each stage can have its own operating calendar. The sending bank may be open while the receiving bank is closed. The receiving bank may be open while an intermediary is observing a holiday. A payment can therefore move through one part of the route while waiting at another.
The BIS describes correspondent banking as a network in which banks maintain accounts with banks in other jurisdictions to facilitate cross-border payments. This structure is one reason international payments can have more processing points than domestic transfers. BIS’s explanation of correspondent banking provides additional background.
Bank Holiday vs Weekend: Why Both Can Affect Settlement
Weekends and bank holidays are related but not identical.
A weekend may already be a non-processing day for a particular settlement system. A public holiday can add an extra non-working day during what would otherwise be a normal banking week.
For example, imagine a payment is released on Friday afternoon in the sending country and Monday is a public holiday in the receiving country. The payment could spend the weekend waiting for the next normal receiving-bank processing cycle, then encounter the Monday holiday before the beneficiary account is credited.
The practical result is that a payment described as taking “one business day” can take longer in calendar time when a holiday sits inside the route.
Not Every Bank Holiday Affects Every Payment
This is an important point for traders.
A holiday in one country does not automatically stop every international payment. The effect depends on which institutions and payment systems are involved.
If the sending bank, relevant intermediary and receiving bank are all operating normally, a holiday elsewhere may have little or no visible effect. But if the payment depends on a bank or settlement system that is closed, the transaction can wait.
Payment systems can also have different holiday calendars. A currency may have its own settlement conventions, while a correspondent bank follows the calendar of its operating jurisdiction.
That is why the most useful question is not simply “Is today a bank holiday?” but rather:
“Is today a non-processing day for a bank or payment system involved in my payment route?”
Why International Payments Can Be Fast but Still Reach Your Bank Late
Modern cross-border payment networks can transmit payment instructions very quickly. Swift reports that most payments on its network reach the beneficiary bank rapidly, but the final stage between the beneficiary bank and the customer’s account can take much longer. Swift describes this final stage as the last mile.
Its current payment-speed guidance says the last mile is heavily influenced by local infrastructure, regulatory requirements, bank operating practices and whether the receiving market supports continuous processing. It also explicitly notes that weekends and holidays can affect crediting when the beneficiary bank or domestic payment system does not operate continuously. Swift’s international payment timing guide explains this distinction.
So a trader can reasonably see a payment reach a bank quickly but still wait for the bank to post it to the account.
Different Holiday Calendars Can Create Extra Delays
Cross-border trading payments often involve two or more countries. Each country can have its own public holidays, banking holidays and payment-system calendars.
Consider a simplified USD-to-INR withdrawal:
- The payment originates with a US-based institution.
- A payment provider or correspondent handles the international route.
- The receiving account is with an Indian bank.
A US holiday can affect the sending side. An Indian bank holiday can affect the receiving side. A holiday affecting an intermediary can affect the middle of the route.
The same withdrawal amount can therefore arrive on different dates depending on the payment route and the institutions used.
Currency Conversion Can Add Another Processing Stage
Many Indian traders receive international payments in a foreign currency while maintaining an INR bank account. That means the payment may need to be converted before the final amount is credited.
The conversion itself does not necessarily stop on every bank holiday, but the surrounding banking and settlement process can be affected by the holiday calendar. A payment may be received by an institution but not converted or posted until the next available processing window.
This is also why the amount shown by a trading platform or payment provider may not match the final INR amount in your bank statement. Exchange rates, bank spreads and applicable charges can affect the final credited amount.
For related reading, see TradeOG’s guides on why your bank statement can show a different amount than a forex withdrawal and how bank conversion charges can reduce trading returns.
Compliance Teams Can Also Work on Business-Day Schedules
A payment may reach a financial institution but still require an operational or compliance step before the account is credited.
Cross-border payments can involve regulatory reporting, beneficiary checks, payment-purpose information, sanctions screening and other controls. The BIS notes that some payment frictions are deliberately maintained for compliance and risk-management purposes rather than being purely technical inefficiencies.
When a holiday reduces staffing or operating hours, a payment requiring manual review may wait for the next working period.
This does not mean a holiday automatically triggers a compliance review. It simply means that a payment already subject to a normal verification process may take longer when the relevant team or system is unavailable.
Cut-Off Times Matter More Around Holidays
Bank holidays become particularly relevant when a payment is submitted close to a daily cut-off time.
Suppose a payment provider receives your withdrawal request late in the business day. If the instruction misses the day’s processing cut-off and the following day is a bank holiday, the effective processing date may move to the next working day.
This can make a delay look larger than it actually is.
The same principle applies before long holiday weekends. A payment initiated late on the final working day can effectively wait through several non-processing periods before the next stage resumes.
How to Tell Whether a Holiday Is Actually Causing the Delay
Do not assume every delayed withdrawal is caused by a holiday. Check the payment chain.
1. Check the payment status
Look for terms such as requested, approved, processing, sent, completed, settled or credited. These statuses can describe different stages.
TradeOG’s guide on why a prop firm payout can show as completed before reaching your bank explains why “completed” does not necessarily mean the beneficiary account has already been credited.
2. Identify the payment method
A bank transfer, payment provider, e-wallet and crypto payout can have completely different settlement processes.
3. Check the relevant countries
Identify the country of the sending institution, any known payment provider or correspondent bank, and your receiving bank.
4. Check the holiday calendars
Look for holidays affecting the actual payment institutions rather than relying only on a generic public-holiday calendar.
5. Check the provider’s business-day estimate
If the provider says a payment normally takes one to three business days, count business days rather than calendar days.
Example: How a Holiday Can Extend a Trading Withdrawal
Imagine an Indian trader requests a $1,000 withdrawal from an international trading platform.
The platform approves it on Friday and sends the payment later that day. The sending institution is closed on Monday for a local bank holiday. The Indian receiving bank is open on Monday, but the payment cannot complete its sending-side processing until the relevant institution resumes operations.
The trader may therefore see:
| Stage | Possible status | What the trader sees |
|---|---|---|
| Friday | Approved / Sent | Payment appears to have left the platform. |
| Saturday-Sunday | Waiting | No bank credit. |
| Monday holiday | Processing | Payment still has not reached final credit. |
| Tuesday | Processing / Received | Bank or payment provider resumes processing. |
| Tuesday or later | Credited | Funds appear in the account. |
This is only an illustration. Actual timing depends on the payment route, currency, cut-off time, institutions involved and their holiday calendars.
Why the Delay Can Be Different for Two Traders
Two traders can request the same amount from the same trading platform and still receive the money on different dates.
Possible differences include:
- Different receiving banks
- Different currencies
- Different payment providers
- Different correspondent banks
- Different account or beneficiary information
- Different request times relative to cut-off
- Different holiday calendars
- Additional verification on one transaction
This is why another trader saying “mine arrived in one day” is not proof that your payment is late.
What Indian Traders Should Do During a Bank Holiday Delay
If a trading withdrawal is delayed around a holiday, the best approach is to track the payment rather than repeatedly requesting it.
- Save the transaction ID.
- Record the date and time the payment was marked sent or completed.
- Identify the payment method and currency.
- Check whether the sending or receiving country has a bank holiday.
- Check the provider’s stated business-day settlement window.
- Review your bank statement and transaction history.
- Wait through the relevant business-day window.
- Contact the provider if the stated window has passed.
When contacting support, ask for the transaction reference and the date the payment was actually released into the banking network. This is more useful than simply asking, “Why is my payout late?”
Bank Holiday Delay vs Payment Problem
| Situation | More likely explanation | What to do |
|---|---|---|
| Payment sent just before a holiday | Normal settlement timing may be extended | Count business days. |
| Payment status has not changed for several working days | Possible processing or verification issue | Contact the provider. |
| Provider says completed but bank has no credit | Last-mile bank processing may still be pending | Request transaction/reference details. |
| Bank confirms rejected or returned payment | Beneficiary or payment-route issue | Ask provider for the reason and next step. |
| Amount arrives lower than expected | Conversion rate or charges may apply | Compare the statement and payment details. |
Does a Bank Holiday Always Mean a Several-Day Delay?
No.
Some payment systems operate continuously, and some modern instant-payment arrangements can process transactions outside traditional banking hours. Swift also reports that international payment infrastructure is becoming faster and more predictable in some corridors.
However, the existence of a fast payment network does not guarantee that every bank in every country credits every incoming international payment 24/7. Swift’s current guidance makes the same distinction: the final credit can depend heavily on the receiving country’s infrastructure and the beneficiary bank’s operating practices.
So the correct rule is not “bank holiday equals three-day delay.” The better rule is:
A bank holiday can extend the settlement window when a relevant bank, payment system or operational process is not running normally.
How to Plan Trading Withdrawals Around Holidays
If you need trading profits for a specific expense, do not plan around the optimistic end of a payment provider’s estimate.
Build a buffer around:
- Public holidays in the sending country
- Public holidays in India
- Weekends
- Currency-specific settlement calendars
- Payment-provider cut-off times
- Bank processing times
This is particularly useful when withdrawing larger amounts. A trader who needs the funds on a particular date should submit the withdrawal early enough to allow for normal settlement variation.
Final Takeaway
International trading payments can take longer on bank holidays because cross-border payments depend on multiple institutions, payment systems and operating calendars. A payment can move quickly through the international network while waiting for the next working window at the sending bank, intermediary, settlement system or receiving bank.
The biggest mistake is treating a payment status such as Sent or Completed as identical to Bank Credited. They are not necessarily the same event.
For Indian traders, the practical approach is simple: identify the payment route, check the relevant holiday calendars, count business days, keep the transaction reference and contact the payment provider when the stated settlement window has actually been exceeded.
Bank holidays can slow the process, but a holiday-related delay by itself does not mean your trading withdrawal has failed or disappeared.
FAQs
Can a bank holiday delay a forex withdrawal?
Yes. If a relevant bank or payment system is closed, processing or settlement may wait until the next working period.
Can an international payment move during a bank holiday?
It depends on the payment rail and institutions involved. Some systems operate continuously, while others have restricted operating hours or settlement calendars.
Why does my payment show sent but not credited?
Sent usually refers to release into the payment route. The receiving bank may still need to process and post the payment to your account.
Do Indian bank holidays affect foreign-currency withdrawals?
They can. If your Indian receiving bank or a relevant domestic processing system is closed, final crediting may move to the next available processing window.
Should I worry if my trading withdrawal is delayed by one bank holiday?
Not necessarily. First compare the elapsed business days with the provider’s stated settlement window and check whether the relevant institutions were operating.
What should I ask support if a holiday delay continues?
Ask for the payment release date, transaction reference, payment route or provider, and whether the funds have reached the beneficiary bank.
[…] For more detail, read Why International Trading Payments Can Take Longer on Bank Holidays. […]