

If you are trading a futures prop firm account, the account size is not the number you should use to measure your real risk. The more important figure is the Maximum Loss Limit (MLL) — the level your account cannot reach under the firm’s rules.
But how is a futures prop firm MLL actually calculated?
The answer depends on the program. Some firms use a static loss floor, while others use an end-of-day or intraday trailing method. Some calculate the threshold from balance, while others may monitor equity or unrealized P&L in real time. That means the same $50,000 account label can have a very different practical risk structure from one program to another.
In this guide, we will break down the mathematics behind MLL, show simple examples, explain trailing calculations, and cover what Indian futures traders should check before relying on a firm’s advertised account size.
What Is a Futures Prop Firm Maximum Loss Limit?
The Maximum Loss Limit is the account’s defined loss boundary. It represents the lowest account level permitted by the program before a breach, liquidation, failure or closure occurs, depending on the firm’s rules.
A simple static example looks like this:
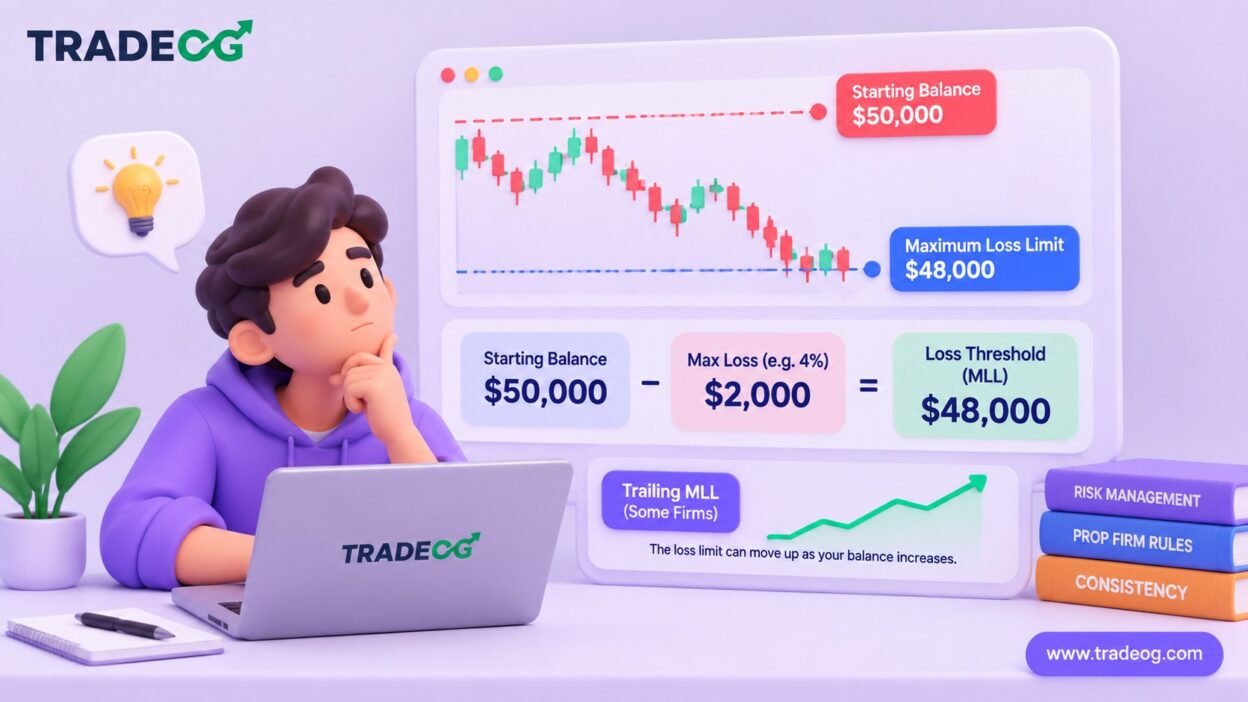
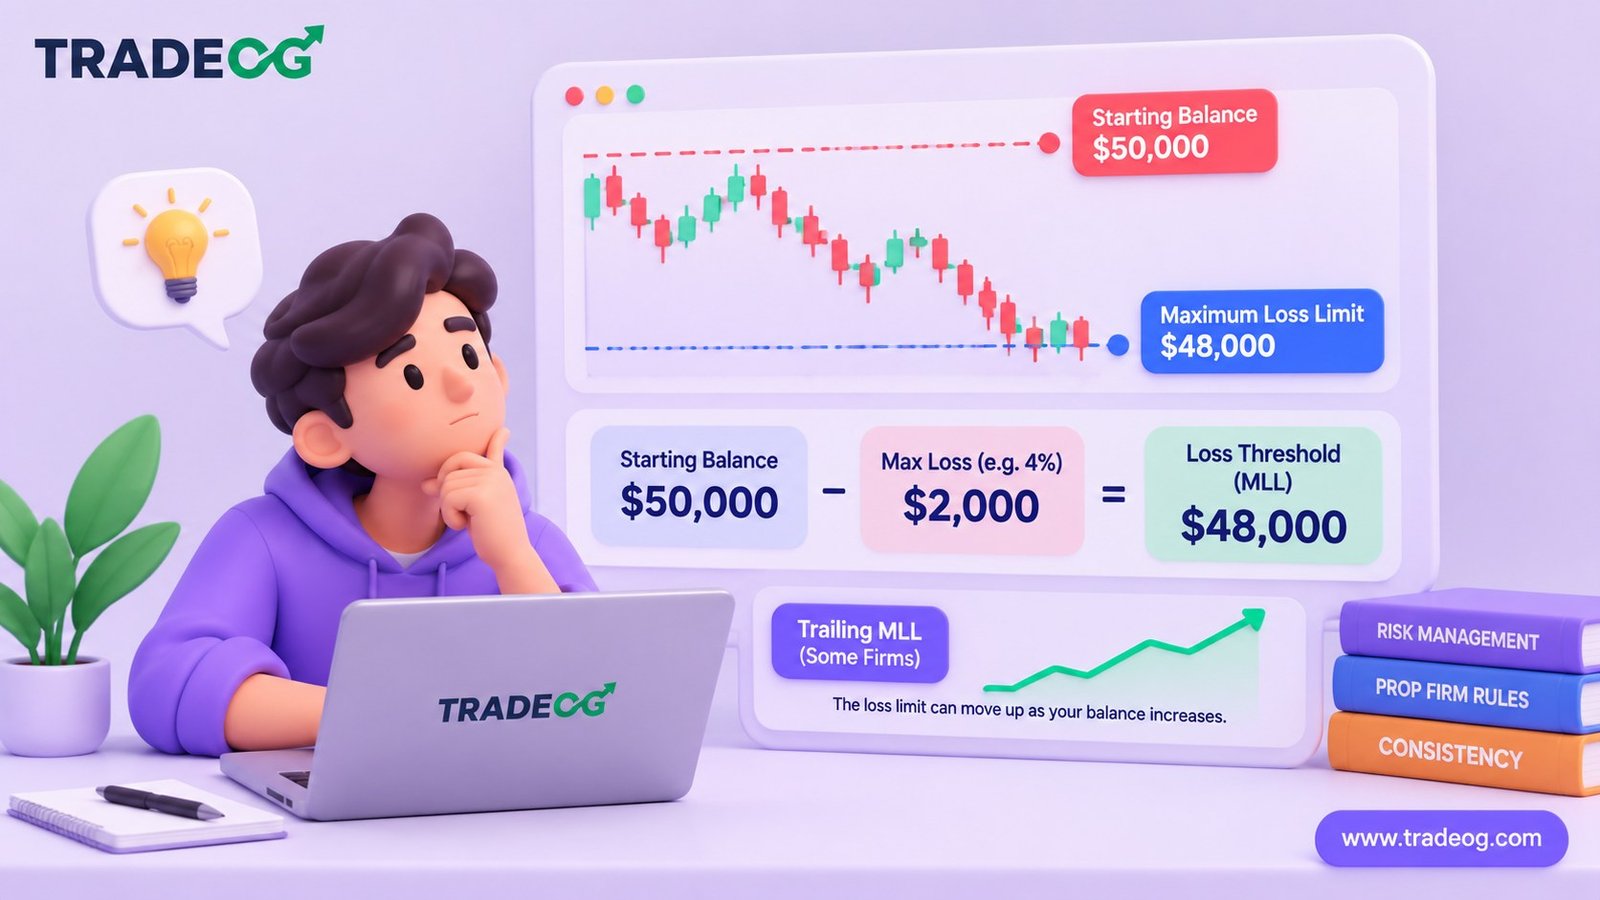
Starting Balance − Maximum Allowed Loss = MLL Threshold
If a hypothetical account starts at $50,000 and permits a $2,000 maximum loss:
$50,000 − $2,000 = $48,000
In that simplified model, $48,000 is the account floor.
However, this does not mean every $50,000 futures prop account will always have a $48,000 MLL. The firm’s published rules determine the actual amount and calculation method.
Basic MLL Formula
For a fixed or static model, the calculation can be represented as:
MLL = Starting Balance − Maximum Loss Allowance
For example:
| Account | Maximum Loss | Initial MLL |
|---|---|---|
| $25,000 | $1,000 | $24,000 |
| $50,000 | $2,000 | $48,000 |
| $100,000 | $3,000 | $97,000 |
These numbers are examples, not a universal industry schedule. As a current real-world example, Topstep publishes $2,000, $3,000 and $4,500 MLL amounts for its $50K, $100K and $150K Trading Combine sizes.
The important lesson is that you should use the firm’s current published parameters rather than assuming a standard percentage such as 4% or 5%.
Is MLL Always Static?
No.
This is where futures prop firm risk rules become more complicated.
An MLL can be implemented as a static threshold or as a trailing threshold. Some firms also use different methods at different stages of their program.
Topstep currently describes its standard Maximum Loss Limit as a trailing limit that rises as the end-of-day balance increases and stops moving once it reaches the starting balance. Its separate $25K Labs Static Trading Combine uses a non-trailing $1,000 MLL.
How Static MLL Is Calculated
With a static MLL, the threshold does not move upward when the account makes money.
Imagine:
- Starting balance: $25,000
- Static maximum loss: $1,000
- MLL: $24,000
If the account grows to $26,000, the MLL remains $24,000.
If the account later falls to $25,000, the trader has given back $1,000 from the high, but the account is still $1,000 above the original MLL.
This creates a simple relationship:
Account Equity − Static MLL = Current Risk Buffer
If equity is $25,000 and the MLL is $24,000:
$25,000 − $24,000 = $1,000 buffer
Topstep’s current $25K Labs static program is an example of a published non-trailing structure: the $1,000 MLL remains fixed at $24,000 as the account grows.
How Trailing MLL Is Calculated
A trailing MLL changes as the account reaches higher reference values.
A simplified trailing formula can be written as:
Trailing MLL = Reference Peak − Drawdown Allowance
The important word is reference. The firm decides whether that reference is based on end-of-day balance, intraday balance, equity, realized P&L or another defined calculation.
For example, suppose a program has:
- Starting balance: $50,000
- Drawdown allowance: $2,000
Initial threshold:
$50,000 − $2,000 = $48,000
If the reference balance later reaches $51,000 and the rule trails by $2,000:
$51,000 − $2,000 = $49,000
The MLL has moved from $48,000 to $49,000.
If the account then drops back to $50,000, the threshold may remain at $49,000 because the trailing floor normally does not move downward.
End-of-Day Trailing MLL Example
An end-of-day trailing model updates the threshold according to the firm’s end-of-day calculation.
Consider a simplified example:
| Day | End-of-Day Balance | Drawdown Allowance | Example MLL |
|---|---|---|---|
| Start | $50,000 | $2,000 | $48,000 |
| Day 1 | $50,500 | $2,000 | $48,500 |
| Day 2 | $51,000 | $2,000 | $49,000 |
| Day 3 | $50,200 | $2,000 | $49,000* |
*Illustration assumes the threshold trails upward only and does not move down after a losing day.
Topstep’s current documentation uses an end-of-day trailing method for its standard MLL and explains that the limit rises with end-of-day balance but never moves downward.
Intraday Trailing MLL
An intraday trailing model can be more dynamic because the reference point may change during the trading session.
For example, suppose:
- Starting balance: $50,000
- Trailing allowance: $2,000
- Account temporarily reaches $52,000 during an open trade
If the firm’s rules use that intraday peak as the reference, the threshold could move to:
$52,000 − $2,000 = $50,000
If the open trade then reverses and equity falls toward $50,000, the trader may be close to the threshold even though the account is still profitable compared with its original $50,000 starting balance.
This is why the exact words in a firm’s rulebook matter. “Trailing drawdown” by itself does not tell you whether the calculation is intraday or end-of-day.
Does Unrealized P&L Count in MLL?
Sometimes it does, and this can be critical.
Unrealized P&L is the profit or loss on an open position that has not yet been closed. If a firm’s risk system monitors the threshold in real time using unrealized P&L, a temporary move against an open futures position can trigger liquidation.
Topstep currently states that its MLL is monitored in real time and includes both realized and unrealized P&L. Its documentation gives an example where an open position pushes the account through the limit, triggering liquidation even though the final realized balance after execution can end up back above the threshold.
This means a trader should not calculate MLL risk using closed trades alone when the program’s rules include live equity or unrealized P&L.
Balance vs Equity: Why the Difference Matters
| Measure | Meaning | Why It Matters |
|---|---|---|
| Balance | Account value after closed trades | Useful for end-of-day or realized calculations |
| Equity | Balance plus/minus open-trade P&L | Important when unrealized P&L is included |
| Peak Balance | Highest relevant balance under the firm’s formula | Can determine a trailing threshold |
| Peak Equity | Highest relevant equity under the firm’s formula | Can make intraday trailing rules more dynamic |
Never assume that a firm’s “balance” and “equity” rules mean the same thing. Read the definition in the actual program agreement.
What Happens When the MLL Is Breached?
The consequence is program-specific.
Depending on the futures prop firm, a breach may trigger automatic liquidation, temporary trading restrictions, evaluation failure or permanent account closure.
Topstep currently says that if its MLL is hit, positions can be liquidated immediately. It also notes that market execution and slippage can cause the final realized balance to differ from the MLL after a breach.
Therefore, traders should not assume that they can touch the threshold and then manually exit before the rule applies.
MLL vs Daily Loss Limit
MLL is also different from a Daily Loss Limit.
| Rule | What It Measures |
|---|---|
| Maximum Loss Limit | Account-level loss boundary |
| Daily Loss Limit | Maximum permitted loss during a trading session |
| Trailing Drawdown | A loss boundary that can move upward with account performance |
| Position Limit | Maximum contracts or exposure allowed |
A trader can therefore remain above the MLL but still hit a Daily Loss Limit. Conversely, staying inside a daily loss limit does not guarantee that the account is far from its overall MLL.
How to Calculate Your Current MLL Buffer
Once you know the firm’s current threshold, the simplest personal calculation is:
Current Buffer = Current Equity − Current MLL Threshold
Example:
- Current equity: $52,400
- Current MLL threshold: $50,000
- Current buffer: $2,400
That $2,400 is the remaining distance to the hard threshold under this simplified example.
For risk management, many traders choose to stop well before the firm’s hard limit rather than using the entire buffer. The exact personal limit depends on the trader’s strategy, position size and the program’s rules.
Why the Advertised Account Size Can Be Misleading
A futures prop firm’s $50K, $100K or $150K label should not automatically be interpreted as the amount you can lose.
For example, Topstep’s current published parameters show a $2,000 MLL for its $50K Trading Combine, $3,000 for $100K and $4,500 for $150K. That means the account label and the actual loss allowance are very different numbers.
Topstep also describes its Express Funded Account as starting at a $0 balance even though the account label represents buying power. Its published MLL then trails upward as the balance grows and locks at $0 once the specified threshold is reached.
Different providers use different structures, so always calculate risk from the actual rules.
How Payouts Can Affect the Effective Loss Floor
Payouts can make MLL calculations more important because withdrawing money can reduce the balance that remains in the account.
Some programs explicitly change the loss floor after a payout.
For example, Topstep’s current payout documentation says the MLL is set to $0 after the first payout in its Express Funded Account, and the remaining balance becomes the effective loss floor.
This is a good example of why traders should calculate the MLL again after a payout rather than assuming the pre-payout risk level remains unchanged.
Worked Example: $50K Futures Prop Account
Consider a hypothetical $50,000 futures account with a $2,000 trailing loss allowance.
At the Start
Starting balance = $50,000
Drawdown allowance = $2,000
Initial MLL = $48,000
After a $1,000 Gain
Reference balance becomes $51,000.
New MLL = $51,000 − $2,000 = $49,000
After a $500 Loss
Account balance becomes $50,500.
If the threshold does not trail downward:
MLL remains $49,000
Current buffer:
$50,500 − $49,000 = $1,500
The trader is still profitable relative to the original $50,000 starting point, but the available drawdown buffer is now $1,500.
How Indian Traders Should Track MLL
If you trade futures through a prop firm from India, keep these numbers visible before and during each session:
- Starting balance
- Current balance
- Current equity
- Current MLL threshold
- Distance to MLL
- Daily Loss Limit
- Maximum position size
Also note the firm’s trading session timezone. A “trading day” can follow the firm’s platform or exchange schedule rather than Indian calendar dates.
MLL Calculation Checklist Before Joining a Prop Firm
- What is the starting balance or buying-power label?
- What is the initial MLL?
- Is the MLL static or trailing?
- If trailing, is it EOD or intraday?
- What is the drawdown amount?
- Does the threshold use balance or equity?
- Does unrealized P&L count?
- When does the threshold update?
- Can the threshold move down?
- When does it stop trailing?
- What happens after a payout?
- What happens when the threshold is touched?
- Does slippage affect liquidation?
- Is there a separate Daily Loss Limit?
Simple MLL Formula to Remember
For a static program:
MLL = Starting Balance − Fixed Maximum Loss
For a simplified trailing program:
MLL = Highest Relevant Reference Value − Trailing Drawdown
But the second formula is only a framework. The firm’s rules determine what “highest relevant reference value” actually means.
Final Takeaway
Understanding how a futures prop firm Maximum Loss Limit is calculated is more important than looking at the headline account size.
In a static model, the loss floor can remain fixed. In a trailing model, the threshold can move upward as the account grows. In an intraday model, the threshold may react to live account performance. If unrealized P&L is included, an open position can breach the limit before the trade is closed.
For Indian futures traders, the practical calculation is simple once the firm’s methodology is known:
Current Risk Buffer = Current Equity − Current MLL Threshold
Keep that number visible, maintain a personal buffer below the firm’s hard threshold, and verify the current official rules before trading.
Do not assume that a $50K or $100K account label tells you how much you can actually lose. The MLL methodology, Daily Loss Limit, position limits and payout rules determine the practical risk of the program.
[…] For a deeper explanation, see TradeOG’s How Futures Prop Firm Maximum Loss Limit Is Calculated. […]
[…] That means a trader can be within the news policy and still breach the account’s risk limits because of a fast adverse move. For more detail on how a futures prop firm Maximum Loss Limit can work, see How Futures Prop Firm Maximum Loss Limit Is Calculated. […]
[…] For a prop trader, the key question is how much of the remaining drawdown that move represents. See our related guide: How Futures Prop Firm Maximum Loss Limit Is Calculated. […]