
When evaluating a prop trading strategy, two numbers appear again and again: risk-to-reward ratio and win rate. Traders often try to decide which one matters more, but looking at either metric in isolation can give a misleading picture.
A strategy can win frequently while losing money if its average losses are too large. Another strategy can lose more trades than it wins and still produce positive results if its average winners are substantially larger than its average losers.
For prop traders, the more useful question is how these metrics combine with position sizing, drawdown, trading costs and expectancy.
What Is Risk-to-Reward Ratio?
The risk-to-reward ratio (R:R) compares the amount you are willing to lose on a trade with the profit target you are seeking.
If a trade risks $100 to target $200, the planned risk-to-reward ratio is 1:2.
- 1:1 = risk $1 to target $1
- 1:2 = risk $1 to target $2
- 1:3 = risk $1 to target $3
- 1:4 = risk $1 to target $4
These are planned ratios. The realized result can be different because of early exits, partial closes, slippage, stop movement or other execution decisions.
What Is Win Rate?
Win rate is the percentage of trades that finish with a profit.
The basic formula is:
Win Rate = Winning Trades ÷ Total Trades × 100
For example, if 60 of 100 trades close profitably, the win rate is 60%.
Win rate does not tell you how large those wins were or how large the losing trades were. That is why it needs to be viewed alongside average win and average loss.
Risk-to-Reward vs Win Rate: The Core Difference
| Metric | What It Measures | What It Does Not Tell You |
|---|---|---|
| Risk-to-Reward | Planned loss compared with planned profit | How often the target is reached |
| Win Rate | Percentage of profitable trades | Size of winners and losers |
| Expectancy | Average historical result per trade | Which future trade will win or lose |
This is why asking whether R:R or win rate is “more important” is incomplete. Both describe different parts of the same trading process.
The Break-Even Win Rate for Different R:R Ratios
If every winning trade and losing trade exactly matches a fixed planned R:R, the theoretical break-even win rate can be calculated as:
Break-Even Win Rate = Risk ÷ (Risk + Reward)
This produces the following simplified figures:
| Risk-to-Reward | Theoretical Break-Even Win Rate |
|---|---|
| 1:1 | 50% |
| 1:2 | 33.33% |
| 1:3 | 25% |
| 1:4 | 20% |
| 1:5 | 16.67% |
These figures are mathematical illustrations, not guarantees of trading performance. Real results can differ because actual exits, fees, slippage, partial positions and changing trade sizes may not match the planned ratio.
Example: 1:1 R:R With a High Win Rate
Suppose a hypothetical strategy has:
- Win rate: 70%
- Average winner: +1R
- Average loser: -1R
Its simplified expectancy is:
(0.70 × 1R) − (0.30 × 1R) = +0.40R
Despite using a 1:1 payoff structure, the high win rate produces positive mathematical expectancy in this simplified example.
Example: 1:3 R:R With a Lower Win Rate
Now consider another hypothetical strategy:
- Win rate: 35%
- Average winner: +3R
- Average loser: -1R
Expectancy becomes:
(0.35 × 3R) − (0.65 × 1R) = +0.40R
This example produces the same simplified expectancy as the first strategy, even though the win rate is much lower.
The lesson is important: different combinations of win rate and payoff can produce similar expectancy.
Why High Win Rate Can Be Misleading
A high win rate looks attractive, but it does not automatically mean a strategy has positive expectancy.
Imagine a strategy that wins 80% of the time but makes only $20 on an average winning trade while losing $150 on an average losing trade.
Its simplified expectancy is:
(0.80 × $20) − (0.20 × $150) = $16 − $30 = −$14
The strategy wins four out of five trades but has negative expectancy in this example.
This is one reason prop traders should avoid judging a system from its win rate alone.
Why a Low Win Rate Can Still Work
A lower win rate can be compatible with positive expectancy when average winners are sufficiently larger than average losses.
For example:
- Win rate: 40%
- Average winner: +2.5R
- Average loser: -1R
Expectancy:
(0.40 × 2.5R) − (0.60 × 1R) = +0.40R
Only four out of ten trades are profitable, yet the simplified average result is positive.
The trade-off is psychological as well as mathematical. A lower win-rate system can produce longer losing streaks, which may be difficult to follow consistently.
Prop Firm Drawdown Changes the Equation
Prop trading adds another layer: drawdown is usually a hard constraint.
A strategy can have positive expectancy and still experience a sequence of losses large enough to create a serious account drawdown.
For example, a 1:3 strategy may have attractive theoretical payoff characteristics, but if its actual win rate is unstable and losing streaks are long, the trader still needs enough drawdown room to survive normal variance.
Track these metrics together:
- Win rate
- Average win
- Average loss
- Realized R:R
- Expectancy
- Maximum drawdown
- Longest losing streak
- Risk per trade
Planned R:R vs Realized R:R
This distinction is often overlooked.
You might plan a 1:3 trade but repeatedly take profit at +0.8R because you become uncomfortable when the market retraces. Your actual average winner may therefore be much smaller than your original target.
Conversely, a trader might occasionally hold winners beyond the original target, producing an average winner larger than the planned target.
For this reason, your journal should track:
- Planned risk
- Planned reward
- Actual loss
- Actual profit
- Realized R
Risk-to-Reward and Position Size Are Different
A 1:3 setup does not automatically mean that the trade is low risk.
Risk is determined by the amount of capital exposed if the stop is reached.
For futures, a simplified position-risk calculation is:
Dollar Risk = Stop Distance × Dollar Value Per Point × Number of Contracts
Changing the number of contracts changes the dollar risk even when the chart-based R:R remains identical.
For prop traders, position size should therefore be considered alongside the account’s remaining drawdown buffer and applicable contract limits.
Risk-to-Reward and Win Rate by Setup
Do not calculate these metrics only for your entire account.
Tag each trade by setup and calculate statistics separately where you have a meaningful sample.
For example, compare:
- Breakout trades
- Pullback trades
- Trend-continuation trades
- Reversal trades
- News-session trades
- Different market sessions
A strategy can have a strong overall win rate because one setup performs well while another setup is consistently negative.
Expectancy Is the Bridge Between R:R and Win Rate
Expectancy brings win frequency and payoff size together.
A simplified formula is:
Expectancy = (Win Rate × Average Win) − (Loss Rate × Average Loss)
If results are measured in R, the same concept can be expressed using average R per winning and losing trade.
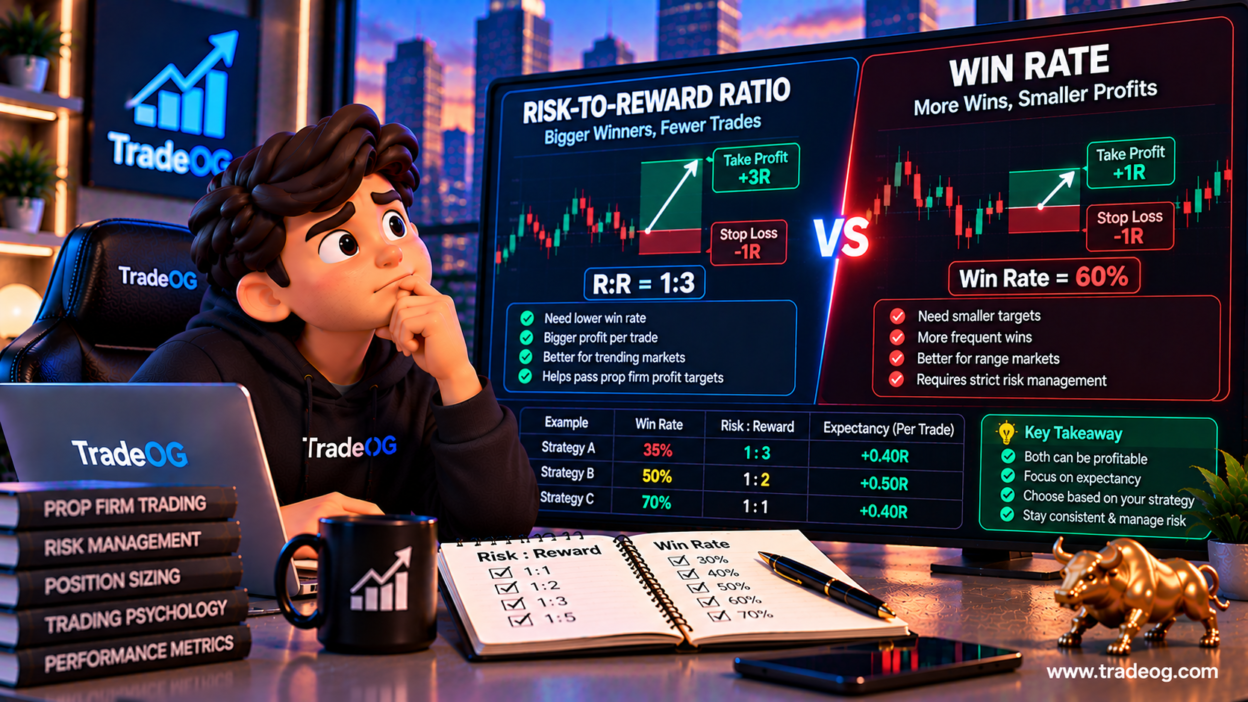
Consider this comparison:
| Strategy | Win Rate | Average Win | Average Loss | Expectancy |
|---|---|---|---|---|
| A | 35% | +3R | -1R | +0.40R |
| B | 50% | +2R | -1R | +0.50R |
| C | 70% | +1R | -1R | +0.40R |
These hypothetical results show why a trader should examine the full distribution of outcomes instead of selecting a strategy from one headline metric.
Trading Costs Can Reduce the Advantage
Commissions, exchange fees, spread and slippage can reduce realized results.
This matters particularly for high-frequency strategies where the expected profit per trade is relatively small.
If a strategy has a very small positive expectancy before costs, its net expectancy can be materially lower after trading expenses.
For a prop trading journal, use a consistent method and record net trade results when evaluating what the strategy actually produced.
How to Track R:R and Win Rate in Your Journal
| Journal Field | What to Record |
|---|---|
| Setup | Strategy or entry model |
| Planned Risk | Initial dollar risk or 1R |
| Planned Reward | Initial profit target |
| Planned R:R | Example: 1:2 |
| Actual P&L | Net trade result |
| Realized R | Actual result divided by planned risk |
| Win/Loss | Final trade classification |
| Exit Reason | Target, stop, discretionary or other |
After enough trades, calculate average win, average loss, win rate, realized R:R and expectancy for the complete dataset and each major setup.
Common Mistakes When Comparing R:R and Win Rate
- Chasing a high win rate: A high percentage of wins can hide oversized losses.
- Chasing a huge R:R: A very large target may be reached too infrequently for the strategy to work.
- Using planned R:R as actual performance: Your realized results may be very different.
- Ignoring drawdown: Positive expectancy does not remove losing streaks.
- Ignoring costs: Small statistical edges can be reduced by commissions and slippage.
- Changing risk after losses: Increasing size to recover losses can alter the strategy’s original risk profile.
- Comparing tiny samples: A few trades can make win rate and average R move dramatically.
Which Metric Should Prop Traders Focus On?
Instead of selecting either R:R or win rate as the only metric, evaluate the combination that produces your actual results.
A useful hierarchy is:
- Define acceptable risk per trade.
- Track actual win rate.
- Track actual average win and average loss.
- Calculate realized R:R.
- Calculate expectancy.
- Measure maximum drawdown and losing streaks.
- Review results by setup and market condition.
This approach keeps the analysis connected to the actual trading process rather than a single attractive statistic.
Final Takeaway
Risk-to-reward ratio and win rate are not competing metrics. They describe different parts of a trading strategy and become much more useful when combined with average win, average loss and expectancy.
A high win rate can work with modest reward multiples. A lower win rate can work with larger average winners. Neither outcome is guaranteed, and neither metric alone tells you whether a prop trading strategy will survive its drawdown constraints.
For prop traders, track realized R:R, win rate, expectancy, risk per trade, maximum drawdown and losing streaks together. The objective is not to maximize one number; it is to understand whether the complete risk-and-reward profile is consistent with your trading plan and account rules.