Gold traders often hear a simple rule: falling Treasury yields are bullish for gold. The rule is useful, but it is incomplete.
Nominal yields and real yields are not the same thing. A 10-year Treasury yield can fall because inflation expectations are falling, because growth expectations are weakening, because markets expect easier monetary policy, or because investors are demanding less compensation for holding long-duration bonds. The gold reaction can differ significantly depending on what is happening underneath the headline yield.
For XAU/USD traders, this distinction is important because gold is influenced more by the real opportunity cost of holding a non-yielding asset than by the nominal Treasury yield alone. The World Gold Council’s 2026 research continues to highlight real rates, the US dollar and growth expectations as important variables in gold’s response to changing macro conditions.
Nominal Yield vs Real Yield: The Basic Difference
A nominal Treasury yield is the stated yield on a government bond before adjusting for inflation expectations.
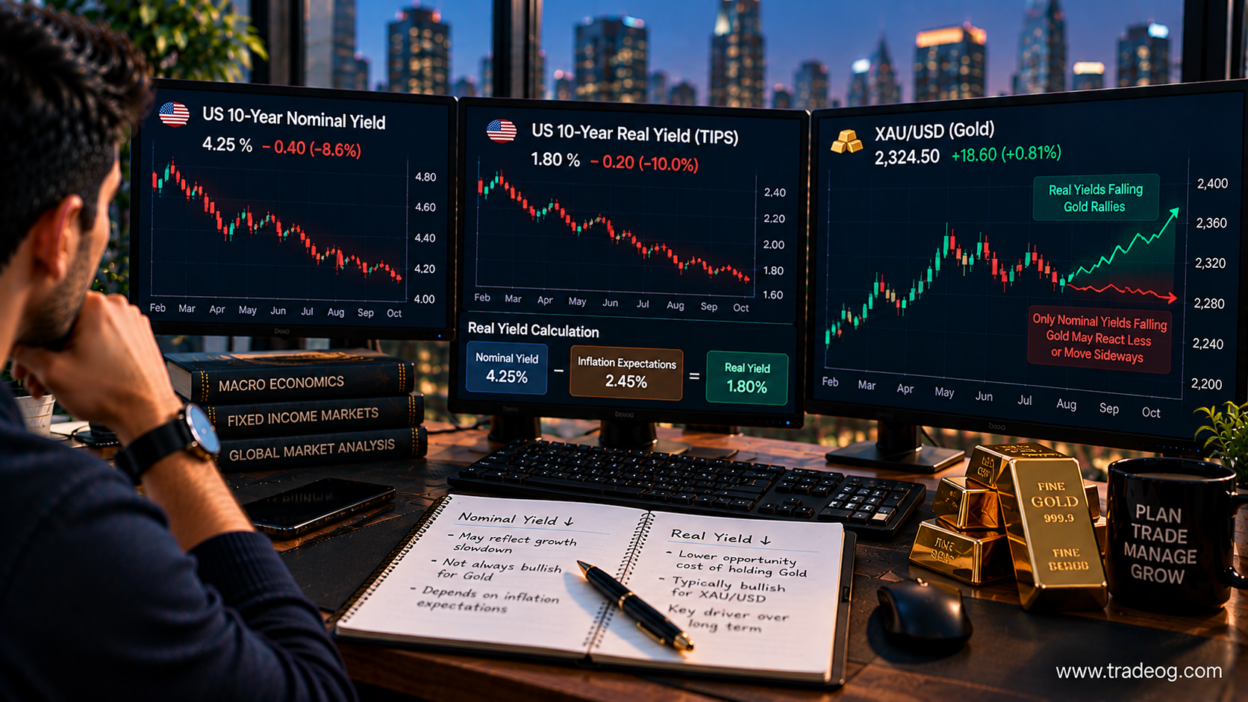
A real yield attempts to measure the return after accounting for expected inflation. A simplified relationship is:
Real yield ≈ Nominal yield − Inflation expectations
For example, imagine the US 10-year nominal yield falls from 4.50% to 4.20%.
If expected inflation remains around 2.50%, the simplified real yield falls from approximately 2.00% to 1.70%. That is generally a meaningful decline in the opportunity cost of holding gold.
But suppose the nominal yield falls from 4.50% to 4.20% because inflation expectations fall from 2.50% to 2.00%. The simplified real yield would remain around 2.20%, meaning real yields have actually increased.
Both situations produce a 30-basis-point decline in nominal yields. Yet their implications for gold can be very different.
Why Gold Cares About Real Yields
Gold does not pay a coupon or interest. When an investor holds gold instead of a government bond, the investor gives up the potential income from that bond.
That foregone return is part of gold’s opportunity cost.
When real yields rise, inflation-adjusted returns on government securities become more attractive. This can create a headwind for gold.
When real yields fall, the relative advantage of holding inflation-adjusted government debt decreases. That can make gold comparatively more attractive.
This is why a falling real yield can be a more useful gold signal than a falling nominal yield.
The relationship is not mechanical, however. The World Gold Council notes that gold has continued to perform even during periods of historically restrictive US real rates, partly because central-bank buying and Asian investor demand can offset the traditional rate relationship.
Scenario 1: Nominal Yields Fall and Real Yields Also Fall
This is usually the cleaner bullish environment for gold, although it is still not a guaranteed buy signal.
Suppose:
- 10-year nominal yield: 4.50% → 4.20%
- Inflation expectations: 2.50% → 2.45%
- Approximate real yield: 2.00% → 1.75%
Here, most of the nominal yield decline is not being cancelled by a large fall in inflation expectations. Real yields are falling as well.
For gold, the opportunity cost of holding a non-yielding asset is declining.
If the US dollar is also weakening and growth concerns are increasing, the environment can become even more supportive for XAU/USD.
This is broadly consistent with the World Gold Council’s 2026 scenario work, which identifies falling rates, a weaker dollar and increased risk aversion as factors that can support gold.
Scenario 2: Nominal Yields Fall but Real Yields Stay High
This is where the simple “yields down = gold up” rule becomes unreliable.
Suppose:
- 10-year nominal yield: 4.50% → 4.20%
- Inflation expectations: 2.50% → 2.10%
- Approximate real yield: 2.00% → 2.10%
Nominal yields have fallen by 30 basis points, but the simplified real yield has increased by 10 basis points.
Why? Inflation expectations fell even faster than nominal yields.
For gold, this can mean that the opportunity-cost environment has actually become less favourable despite the headline Treasury yield falling.
This is one reason gold can sometimes fail to rally when traders see falling Treasury yields on their screens.
Scenario 3: Nominal Yields Fall Because Growth Expectations Collapse
Another situation occurs when investors suddenly become worried about economic growth.
They may buy government bonds, pushing Treasury prices higher and yields lower. Gold can benefit because markets may begin pricing lower policy rates and greater economic uncertainty.
But the gold reaction depends on the complete macro picture.
If the growth scare produces a powerful US dollar rally, the dollar can offset part of gold’s positive response. If investors simultaneously seek liquidity in dollars, XAU/USD may initially behave differently from what the falling-yield signal suggests.
Later, if markets move from “growth scare” to “easier policy and lower real yields,” gold can receive stronger support.
The timing matters.
Scenario 4: Nominal Yields Fall Because Inflation Expectations Collapse
This is a very different environment.
Suppose a sharp disinflation shock causes investors to expect significantly lower future inflation. Bond yields fall because the inflation component of the yield is declining.
Gold does not necessarily receive the same bullish impulse.
If real yields remain elevated or rise, investors may still find inflation-adjusted bonds attractive relative to gold.
In other words, lower inflation is not automatically bullish for gold simply because it pushes nominal yields lower.
This distinction is especially useful when interpreting CPI, PCE, PPI and inflation-expectation data.
The Inflation-Expectation Component Is the Missing Piece
Think of the nominal yield as containing several components rather than one simple number.
A simplified framework is:
Nominal yield ≈ Real yield + Expected inflation + Term premium effects
The relationship is not an exact accounting identity for every market quote, but it is a useful framework for traders.
If nominal yields fall, ask:
- Did real yields fall?
- Did inflation expectations fall?
- Did the term premium fall?
- Did expectations for Fed policy change?
- Did growth expectations change?
The answer determines how much information the nominal yield move actually contains for gold.
Why the 10-Year Yield Alone Can Mislead XAU/USD Traders
A trader watching only the US 10-year Treasury yield sees one line on a chart. But gold is responding to a much larger macro system.
For example, the 10-year yield could fall while:
- real yields remain elevated;
- DXY strengthens;
- inflation expectations collapse;
- equity markets remain strong;
- safe-haven demand remains weak.
In that environment, gold may rise only modestly, consolidate, or even decline.
Conversely, nominal yields could remain relatively high while real yields fall and the dollar weakens. Gold can then remain strong despite what appears to be a bearish nominal-rate environment.
TradeOG’s earlier article Gold and US Treasury Yields: Understanding the Relationship explains the broader relationship between gold and Treasury yields, while What Is Real Yield and Why Does It Matter for Gold Traders? goes deeper into the real-yield mechanism.
Falling Nominal Yields Can Be Bullish for Different Reasons
Not every falling-yield environment has the same meaning. Consider four common explanations.
1. Expectations of Fed easing
If markets price future rate cuts, shorter- and longer-duration yields can fall. If the move reduces real yields and weakens the dollar, gold can respond positively.
2. Falling inflation expectations
If yields fall mainly because inflation expectations decline, the gold response can be weaker, particularly if real yields remain firm.
3. Growth scare
Weak economic data can push investors into Treasuries. Gold may benefit from lower yields and defensive demand, but the dollar’s reaction becomes important.
4. Term-premium compression
Long-term yields can decline because investors demand less compensation for duration risk. If real yields barely change, the effect on gold can be less direct than a similar move in real yields.
What Happens When Real Yields Fall but Nominal Yields Barely Move?
This is an especially interesting setup for gold traders.
Suppose the 10-year nominal yield stays around 4.20%, but inflation expectations increase from 2.20% to 2.60%.
The simplified real yield falls from approximately 2.00% to 1.60%.
Gold can become more attractive because inflation-adjusted bond returns are falling even though the headline nominal yield has barely changed.
This is one reason XAU/USD can rally while a trader looking only at the 10-year nominal yield sees almost no change.
The market is effectively saying: the nominal return has not changed much, but the purchasing-power-adjusted return has deteriorated.
Why Falling Real Yields Do Not Guarantee a Gold Rally
Real yields are important, but gold has multiple demand sources.
The World Gold Council’s recent research is particularly useful here. It notes that central banks and Asian investors have become increasingly important drivers of gold demand, meaning gold can perform differently from what US real-rate relationships alone would suggest.
Other variables include:
- US dollar direction
- geopolitical risk
- ETF flows
- central-bank purchases
- positioning and momentum
- economic growth expectations
- equity-market stress
- physical demand
Therefore, falling real yields should be treated as a major macro input, not a guaranteed entry signal.
How the US Dollar Changes the Yield Signal
Gold is quoted in US dollars, so the currency can amplify or offset a yield-driven move.
Imagine real yields fall sharply. That is normally supportive for gold. But if the dollar simultaneously strengthens because global investors are seeking dollar liquidity, the XAU/USD reaction can be muted.
Conversely, falling real yields accompanied by a weaker DXY can create a much cleaner bullish backdrop.
This is why advanced XAU/USD analysis should often compare three charts:
- XAU/USD
- US 10-year real yield
- DXY
Nominal 10-year yields then provide another layer of context rather than the entire signal.
For more on this interaction, see Why Gold Sometimes Rises When the Dollar Also Rises and How US Dollar Strength Affects Gold Prices for Indian Traders.
A Practical Comparison for XAU/USD Traders
| Nominal Yields | Real Yields | Typical Gold Interpretation |
|---|---|---|
| Falling | Falling | Generally supportive |
| Falling | Flat | Potentially supportive, but weaker |
| Falling | Rising | Can be neutral or bearish |
| Flat | Falling | Potentially bullish |
| Rising | Falling | Mixed; inspect inflation expectations |
| Rising | Rising | Usually a stronger headwind |
These are analytical tendencies, not fixed trading rules. Gold can deviate from them when geopolitical risk, central-bank demand, positioning or other forces dominate.
How to Read a Yield Move During a US Data Release
Suppose CPI comes out and Treasury yields immediately fall.
Do not buy XAU/USD simply because the 10-year yield is red.
Instead, ask:
- Did the inflation number change expectations for future inflation?
- Did the market price more Fed easing?
- Did real yields fall?
- Did DXY weaken?
- Did XAU/USD break and hold above a meaningful level?
- Was the first gold move confirmed after the initial volatility?
This last point is important because headline-driven markets can produce a fast first reaction followed by a complete repricing. TradeOG’s How XAU/USD Repricing Happens After the First News Spike explains why the first candle after major news should not automatically be treated as the final market interpretation.
How Indian Traders Can Use This Framework
For Indian traders focused on XAU/USD during London and New York hours, the framework can be simplified into a dashboard.
Before taking a macro-sensitive gold setup, check:
- US 10-year nominal yield: Is it rising or falling?
- US 10-year real yield: Is the inflation-adjusted return changing?
- DXY: Is the dollar confirming or contradicting the yield move?
- US economic data: Is the market repricing inflation or growth?
- XAU/USD structure: Is price actually accepting the new information?
If nominal yields are falling and real yields are falling while DXY is weakening, the macro backdrop is generally more supportive for gold.
If nominal yields are falling but real yields are rising and DXY is strengthening, the headline yield signal should be treated cautiously.
For Indian traders, this is especially useful around US CPI, PCE, NFP, FOMC decisions and major Treasury-market repricing events.
A Simple Five-Step Yield-to-Gold Checklist
Step 1: Start with nominal yields
Identify the direction and magnitude of the Treasury yield move.
Step 2: Find the reason
Determine whether the move is being driven by inflation expectations, growth expectations, Fed policy expectations or term-premium changes.
Step 3: Check real yields
This is the critical step. A nominal yield move without confirmation from real yields can produce a misleading gold signal.
Step 4: Check DXY
A falling real yield plus a weakening dollar is generally a cleaner supportive combination for XAU/USD than falling yields alone.
Step 5: Wait for price confirmation
Use XAU/USD market structure, support and resistance, breakouts, retests or liquidity behavior to determine whether the macro signal is actually being accepted by the gold market.
Common Mistakes Traders Make
- Watching only the 10-year nominal yield. This hides the inflation component.
- Assuming every yield decline is bullish for gold. Real yields can rise while nominal yields fall.
- Ignoring inflation expectations. They can explain why nominal and real yields diverge.
- Ignoring DXY. Currency moves can offset the yield signal.
- Trading the macro signal before price confirms it. A fundamentally supportive environment can still produce poor entries.
- Treating correlation as causation. Gold responds to a network of macro variables, not one bond-market number.
Frequently Asked Questions
Is falling nominal yield always bullish for gold?
No. Gold can react weakly or even negatively if falling nominal yields are accompanied by falling inflation expectations and rising real yields.
Why are falling real yields usually more important for gold?
Real yields are closer to the inflation-adjusted opportunity cost of holding gold. When real yields fall, the relative advantage of interest-bearing assets can decline.
Can gold rise when nominal Treasury yields are rising?
Yes. If inflation expectations or other factors rise faster than nominal yields, real yields can fall. Gold can also receive support from geopolitical risk, central-bank demand, a weaker dollar or other drivers.
What should I watch with the US 10-year yield?
Watch the US 10-year real yield, inflation expectations and DXY alongside the nominal 10-year yield. Together they provide much more information than the headline yield alone.
Does a falling real yield guarantee a gold rally?
No. It is a supportive factor, not a guaranteed signal. Gold can be influenced by the dollar, risk sentiment, positioning, central-bank demand, physical demand and technical structure.
What is the simplest rule for XAU/USD traders?
Do not ask only whether nominal yields are falling. Ask whether real yields are falling and whether the dollar confirms the move. Then wait for XAU/USD price action to confirm the trading setup.
Final Takeaway
Falling nominal yields and falling real yields can look identical on a headline Treasury chart, but they can represent very different macro conditions.
If nominal yields fall because inflation expectations are falling even faster, real yields may rise and gold may not receive the expected bullish impulse. If nominal yields fall while real yields also decline, the opportunity cost of holding gold can fall, creating a more supportive environment for XAU/USD.
The key relationship for gold traders is therefore not simply:
Yields down = Gold up.
A better framework is:
Nominal yields → inflation expectations → real yields → DXY → XAU/USD.
Use that chain to understand why yields are moving, then let actual XAU/USD price structure determine the trade.
Disclaimer: TradeOG provides educational and informational content only. Nothing in this article should be treated as financial, investment, legal, tax, banking or professional advice. Market relationships can change across different economic regimes, timeframes and events. Always conduct your own research and manage risk before making trading decisions.