Forex traders often focus on the exchange rate when converting trading withdrawals into Indian rupees. But when the amount is small, the rate shown on a currency converter is not always the rate that determines how much INR finally reaches your bank account.
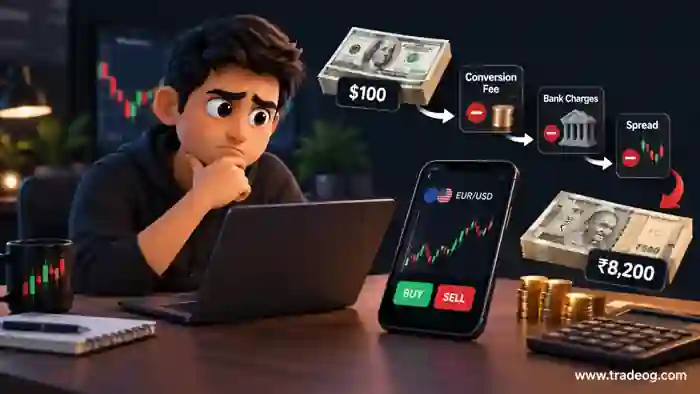
This is why a small forex withdrawal can feel surprisingly expensive after conversion to INR. A fixed bank charge, payment-processing fee, foreign-exchange spread, intermediary charge or minimum transaction fee can take a much larger percentage of a small transaction than of a larger one.
Why Does Forex Trading Cost More When Converting Small Amounts Into INR?
The main reason is simple: some currency-conversion costs are fixed or have minimum charges, while the amount being converted is small. A ₹300 or ₹500 equivalent charge has little impact on a large withdrawal, but it can significantly reduce a small withdrawal.
For example, suppose a trader converts USD 100 into INR. If the total conversion-related cost is USD 5, the trader has effectively paid 5% before considering any movement in the exchange rate. On a USD 1,000 conversion, the same USD 5 cost would represent only 0.5%.
The exact charges depend on the broker, payment method, bank, payment processor and transaction route. There is no single forex conversion fee that applies to every Indian trader.
What Makes Small Forex Conversions More Expensive?
1. Fixed transaction charges
Some payment providers or banks apply a fixed fee to an international transaction or currency conversion. A fixed charge does not become smaller just because the withdrawal amount is smaller.
That creates an important difference between percentage cost and absolute cost. A ₹200 charge on a ₹20,000 conversion is 1%, while the same ₹200 charge on a ₹5,000 conversion is 4%.
2. The foreign-exchange spread
The exchange rate available to a customer can differ from the mid-market rate displayed by a public currency converter. The difference is commonly described as the FX spread.
For an Indian forex trader, the relevant question is not simply “What is USD/INR today?” It is “What USD/INR rate will my payment provider or bank actually use for this transaction?”
3. Payment processor fees
A withdrawal may pass through a payment service or financial institution before the funds reach an Indian bank account. Depending on the route, processing costs may be built into the exchange rate or charged separately.
Small withdrawals can be particularly sensitive to these costs because there is less transaction value over which to spread the charge.
4. Minimum fees
Some services use minimum charges. This means that a transaction below a certain size can effectively have a higher percentage cost.
For example, a service charging the equivalent of ₹150 for processing would have a much greater percentage impact on a ₹5,000 transaction than on a ₹50,000 transaction.
5. Intermediary or correspondent bank charges
International payments can sometimes involve more than one financial institution. Depending on the payment method and transaction structure, intermediary charges may affect the amount ultimately received.
These costs are not always obvious when a trader initiates a withdrawal, which is why the final INR received can sometimes differ from an initial estimate.
Small Forex Withdrawal vs Large Withdrawal
Consider a simplified example. These figures are for illustration only and are not a quote from any particular bank, broker or payment provider.
| Withdrawal | Example total cost | Approximate cost percentage |
|---|---|---|
| USD 100 | USD 5 | 5% |
| USD 500 | USD 7 | 1.4% |
| USD 1,000 | USD 10 | 1% |
The example demonstrates why small transactions can feel expensive even when the nominal fee does not look large. The important number is the effective cost as a percentage of the amount being converted.
Why the Exchange Rate Alone Can Be Misleading
Many traders compare the final INR received with a Google search or currency-converter rate. That comparison can be useful, but it does not necessarily represent the rate used by the bank or payment provider.
The displayed market rate is generally a reference rate. Your actual transaction can include a spread or other conversion adjustment. Therefore, the better calculation is:
Effective INR Rate = Net INR Received ÷ Foreign Currency Amount Sent
This gives you the rate you actually received after the relevant charges included in the transaction.
How Indian Traders Can Reduce the Cost of Small Forex Conversions
Compare the net amount, not just the advertised fee
A provider advertising a low transaction fee is not automatically the cheapest option. Another provider may have a higher visible fee but a better exchange rate.
Before withdrawing, compare the final expected INR amount after all known charges.
Avoid unnecessary small conversions
If your broker and payment method permit it and the arrangement is consistent with applicable rules, consolidating withdrawals can sometimes reduce the relative impact of fixed charges.
This is not a recommendation to delay withdrawals blindly. Traders should consider liquidity needs, platform rules, withdrawal limits, tax considerations and applicable Indian regulations before changing their withdrawal pattern.
Check your bank’s foreign transaction pricing
Do not assume that every bank uses the same conversion methodology. Check the bank’s published charges and the rate used for the relevant transaction type.
Keep a record of the amount sent and amount received
For every withdrawal, record the foreign-currency amount, quoted rate, fees, INR credited and transaction date. After a few transactions, you can calculate your real effective conversion cost instead of relying on assumptions.
How to Calculate Your Real Forex Conversion Cost
Use this simple process:
- Write down the foreign-currency withdrawal amount.
- Record the exchange rate quoted before conversion, if available.
- Record every visible fee.
- Check whether the bank or payment provider deducted anything from the transaction.
- Record the exact INR amount credited to your account.
- Calculate the effective INR rate using the final amount received.
You can then compare the effective rate with a reference market rate for the same time. The difference gives you a practical view of your conversion cost.
Does a Small Forex Withdrawal Always Cost More?
No. A small withdrawal does not automatically have a higher percentage cost. It depends on the pricing structure used by the broker, bank and payment provider.
However, when a transaction includes fixed fees, minimum charges or a relatively wide FX spread, smaller withdrawals are more likely to have a higher effective percentage cost.
What Indian Forex Traders Should Check Before Withdrawing
- Minimum withdrawal amount
- Withdrawal fee charged by the platform
- Currency conversion rate
- FX spread or conversion markup
- Bank receiving charges
- Possible intermediary charges
- Expected INR amount after conversion
- Transaction and withdrawal limits
- Applicable tax and regulatory requirements
Rules and payment availability can vary by provider and can change over time. Traders should verify the current terms directly with the relevant financial institution or platform before making a transaction.
Frequently Asked Questions
Why are small forex withdrawals expensive in India?
Small withdrawals can have a higher effective cost because fixed transaction charges, minimum fees and FX spreads represent a larger percentage of the amount being converted.
Is the USD to INR rate shown online the rate I will receive?
Not necessarily. Online currency rates are useful references, while the bank or payment provider may apply its own conversion rate, spread and transaction charges.
How can I find the real cost of a forex conversion?
Compare the foreign-currency amount sent with the exact INR amount received. The resulting effective rate shows what you actually received after the applicable transaction costs.
Is it cheaper to withdraw a larger amount?
It can be cheaper on a percentage basis when fixed fees are involved, but the best approach depends on the provider’s fee structure, withdrawal rules, your cash-flow needs and applicable requirements.
Can banks charge more for international currency conversion?
Banks and payment providers can have different pricing structures for foreign-currency transactions. Always check the applicable tariff and transaction terms before relying on an estimated conversion amount.
Final Takeaway
The cost of converting forex withdrawals into INR is not determined by the exchange rate alone. Fixed fees, minimum charges, payment processing costs and the FX spread can have a disproportionate effect on smaller transactions.
For Indian traders, the most useful habit is to calculate the net INR received and the effective exchange rate for every withdrawal. Once you track those numbers, it becomes much easier to identify where your money is being lost and whether a different withdrawal method offers better value.