Ask ten funded traders what their per-trade risk is, and at least eight will recite the classic textbook mantra: “I risk 1% per trade.”
It sounds disciplined. It feels conservative. And it is hands down the single fastest way to blow a prop firm evaluation.
The traditional “1% rule” was developed for personal cash accounts where losing 10% of your capital is an unpleasant dip on a performance chart. In the prop firm ecosystem, a 10% loss isn’t a drawdown—it’s an instant breach, a terminated dashboard, and a wasted evaluation fee.
If you want to keep a funded account long enough to take regular payouts, you have to unlearn retail account sizing. Here is the realistic math behind prop firm risk, how to calculate your true capital buffer, and the exact percentage you should risk on every execution.
Risk Per Trade vs Daily Loss Limit: How to Calculate Your Buffer
Related TradeOG guides: daily loss limit vs stop loss, prop firm drawdown, and position sizing based on drawdown.
Related: daily loss limit vs stop loss and prop firm risk management.
The biggest mental trap in modern prop trading is the account balance displayed on your terminal.
When you purchase a $100,000 evaluation account, you do not have $100,000 of risk capital. You have $100,000 of buying power, but your actual capital buffer is solely determined by the firm’s loss limits:
- Maximum Overall Drawdown: Usually 8% to 10% ($8,000 – $10,000).
- Maximum Daily Loss Limit: Usually 4% to 5% ($4,000 – $5,000).
If you risk 1% ($1,000) of the $100,000 face value on a single trade, you aren’t risking 1% of your available room. You are risking 20% to 25% of your entire daily failure buffer in one setup.
Four consecutive losses in a volatile morning session—or two normal losses plus slippage and spread widening during high-impact news—and your account is closed before the New York lunch session begins.
2. Recommended Risk Framework: Evaluation vs. Funded Phase
Because your objectives during a challenge differ fundamentally from those of a live-funded stage, your sizing strategy must adapt.
Phase 1: The Challenge / Evaluation Phase (Risk: 0.25% – 0.50%)
During an evaluation, your goal is to hit a profit target (typically 8% to 10% in Phase 1, 5% in Phase 2) without tripping daily or maximum drawdown tripwires.
- Sweet Spot: 0.25% to 0.50% per trade.
- Why it works: At 0.50% risk on a $100,000 account ($500 per trade), an account with a 5% daily limit ($5,000) can withstand 10 consecutive losing trades in a single day before breaching. At 0.25% risk ($250 per trade), it takes 20 back-to-back stops.
- This provides psychological insulation against streak variance, letting you trade through choppy sessions without fear of an instant liquidation email.
Phase 2: The Funded / Payout Phase (Risk: 0.50% – 0.75% Maximum)
Once funded, the game shifts 180 degrees. You no longer have a profit target or a deadline. Your singular objective is capital preservation and harvesting regular payouts.
- Sweet Spot: 0.50% baseline (scaling to 0.75% only on high-conviction A+ setups).
- In the funded phase, traders often feel tempted to increase size to generate larger dollar payouts quickly. This is where most funded traders blow up within their first 30 days. Maintaining 0.50% risk ensures you stay well outside the trailing drawdown clamp while generating steady, bankable withdrawals.
3. Account Size Cheat Sheet: Dollar Risk by Account Tier
To eliminate guesswork, here is how much you should risk per position based on standard prop firm account sizes:
The Two-Loss Circuit Breaker Rule: Set a personal daily rule to shut down your charts if you take two full losses in a single day. At 0.50% risk, two losses put you at -1.0% for the session—leaving you safely 3% to 4% above the firm’s liquidation cutoff.
4. How Drawdown Models Dictate Position Sizing
Not all drawdowns are calculated identically. How your firm tracks your equity floor directly dictates how much risk you can safely carry.
A. Balance-Based (Static) Drawdown
The loss threshold is fixed at a static level below your initial balance (e.g., $92,000 on a $100,000 account with an 8% static floor). You can maintain a stable 0.50% to 0.75% sizing because your risk cushion expands as you accumulate profits.
B. End-of-Day (EOD) Trailing Drawdown
The floor recalculates at daily market close. If you close higher, your floor trails up. Intraday equity spikes that retrace before the bell do not penalize you. Sizing at 0.50% per trade is optimal.
C. Intraday / Tick-by-Tick Trailing Drawdown (Highest Risk)
Common among futures firms (Apex, Topstep). The drawdown line trails your peak unrealized profit in real time. If a trade goes up $1,500 and retraces to break-even, your drawdown line moved up $1,500 while your P&L gained nothing. With intraday trailing, stick to 0.25% to 0.35% maximum and lock in partial gains aggressively.
5. Step-by-Step Position Sizing Formula
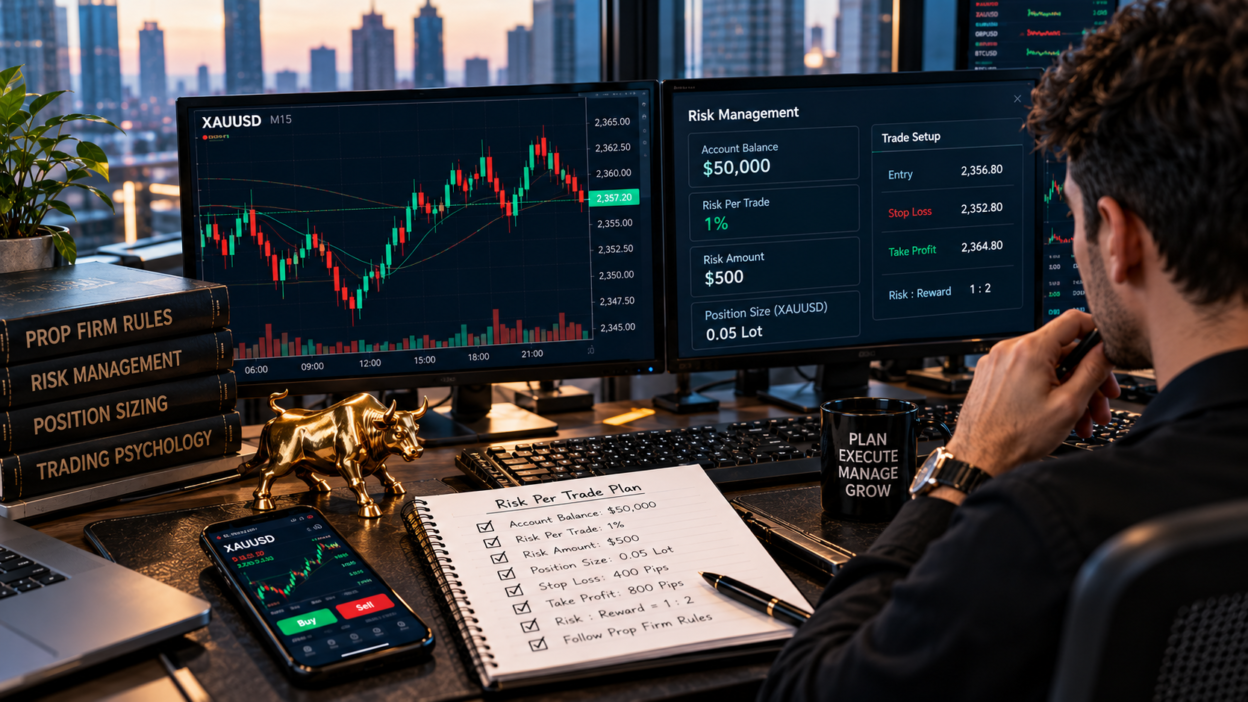
To calculate the exact lot size or contract count for any asset (Forex, Futures, Crypto, or Indices), use this four-step sequence before entering any order:
Lot Size = (Account Balance × Risk %) / (Stop Distance in Pips/Points × Pip/Point Value)Practical Walkthrough: EUR/USD
- Account Size: $100,000
- Target Risk: 0.50% ($500)
- Entry Price: 1.0850
- Stop Loss: 1.0830 (20 pips)
- Pip Value (Standard Lot): $10.00 per pip
Lot Size = $500 / (20 pips × $10.00) = 2.5 Standard Lots
If your setup requires a wider 40-pip stop, your lot size automatically scales down to 1.25 lots. Never expand your risk percentage to justify a preferred lot size—always scale your lot size to match your fixed dollar risk.
6. Three Hidden “Rulebook Traps” That Multiply Risk
1. Simultaneous Correlated Exposure
Opening 0.5% risk on EUR/USD, 0.5% on GBP/USD, and 0.5% on AUD/USD is not three distinct trades. Because all three pairs are pegged against the US Dollar, you are running an aggregate 1.5% short USD position. If a US CPI report drops unexpectedly, all three stops will trigger simultaneously. Cap aggregate open risk across correlated positions at 1.0% to 1.5%.
2. The Consistency Rule
Many firms enforce a consistency rule where no single trading day can generate more than 30% to 40% of your total profit target. Sizing too aggressively (e.g., 1.5% – 2.0%) creates massive winning days that violate consistency rules, forcing you to trade dozens of extra days just to dilute profit distribution.
3. Floating Equity vs. Closed Balance Breaches
Prop firm monitoring engines track real-time equity, not just realized balance. Entering without a hard stop leaves you exposed to slippage or spread widening during rollover that can breach your daily limit before you can manually exit. Always attach hard stops on execution.
7. Frequently Asked Questions (FAQ)
Can I risk 2% per trade in a prop firm challenge?
You can, but mathematically, your probability of failure exceeds 85%. At 2% risk on a $100k account ($2,000), hitting just two consecutive losses pushes you to the brink of a 4% to 5% daily limit. A three-loss streak liquidates the account. It is statistically reckless under prop firm rules.
How many trades should I take per day in a funded account?
Between 1 and 3 high-probability setups. Quality always trumps volume in prop trading. Taking more than 4 trades in a single session significantly spikes commissions, spread friction, and cognitive fatigue.
What should I do if my account drops into 3% drawdown?
Cut your risk per trade by half immediately (e.g., from 0.50% down to 0.25%). Your priority in drawdown is not to make the money back quickly; it is to stabilize the equity curve and restore psychological discipline.
Key Takeaways
- Trade the Buffer, Not the Balance: Your true risk is anchored to the distance to your liquidation floor.
- 0.25% to 0.50% is the Professional Benchmark: It provides sufficient room to pass evaluations while giving you 10 to 20 trade buffers against losing streaks.
- Cap Correlated Exposure: Never hold more than 1.0% to 1.5% total open risk across correlated assets.
- Consistency Outweighs Speed: Sizing small guarantees longevity. Longevity is what unlocks consistent, scalable payouts.