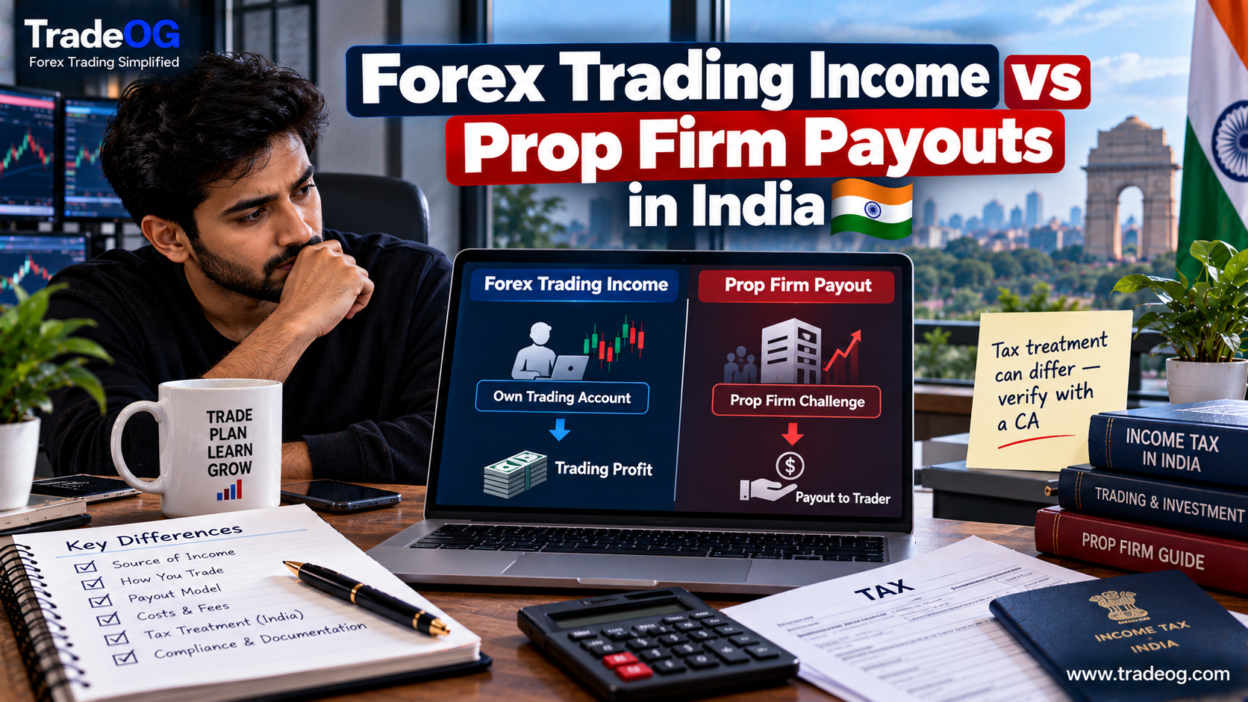
If you trade forex with your own money, the money you make comes from your own trading activity. If you trade through a prop firm, the amount you receive is usually a payout under a contractual arrangement with the firm.
That sounds like a small difference, but for an Indian trader it can affect how you think about the source of income, records, foreign receipts, expenses, tax reporting and compliance.
The Income Tax Department recognises different heads of income, including profits and gains of business or profession, capital gains and income from other sources. The correct classification depends on the actual nature of the activity and the taxpayer’s facts; there is no safe rule that every forex profit or every prop firm payout automatically falls into one category.
Forex Trading Income vs Prop Firm Payouts: The Basic Difference
| Point | Own Forex Trading | Prop Firm Payout |
|---|---|---|
| Who provides the trading capital? | You | The prop firm’s programme may provide trading capital or a simulated/funded environment, depending on its model |
| Who takes the trading risk? | You generally take the risk on your own trading account | The contractual arrangement determines the firm’s and trader’s economic exposure |
| What do you receive? | Your trading result, subject to broker costs and withdrawals | A payout/revenue share or other payment defined by the prop firm’s agreement |
| Trading account ownership | Your broker account | Usually a prop-firm programme account or environment |
| Main records | Broker statements, trades, deposits and withdrawals | Agreement, challenge fees, account records, payout statements and bank/payment records |
| Tax classification | Depends on instrument and activity | Depends on the contractual nature of the payout and your activity |
The biggest mistake is looking only at the word “trading.” Tax treatment follows the underlying transaction and facts, not simply the label used by a website.
What Is Forex Trading Income?
Suppose you deposit ₹1,00,000 into your own trading account and use an authorised route to trade a permitted forex product.
You make trades, pay applicable spread or commission, and your account eventually shows a net gain.
That gain is connected to your own trading activity.
The exact tax treatment depends on what you traded and how you traded it. The Income Tax Department’s current material distinguishes business/profession income from capital gains and other heads, and its ITR guidance uses different return forms depending on the nature of income.
For example, the current ITR framework provides ITR-3 for individuals and HUFs having income under “Profits and Gains of Business or Profession,” while ITR-2 is for individuals/HUFs whose income does not include business or profession income.
That does not mean every trader should automatically choose ITR-3. Your actual facts determine the appropriate return.
What Is a Prop Firm Payout?
A prop firm usually offers a programme in which a trader pays a challenge/evaluation fee or enters another type of trading arrangement, follows specific risk rules, and may become eligible for a payout based on the firm’s contractual model.
For example, a firm might say that a trader receives 80% or 90% of an eligible profit amount. The exact percentage, rules and payout conditions differ from firm to firm.
The important point is that the money you receive is not automatically the same thing as profit generated inside your personal brokerage account.
You may instead be receiving money because you satisfied the conditions of a contract or programme.
A Simple Example
Imagine two Indian traders both receive ₹1,00,000.
Trader A: Own account
Trader A deposits personal money into a trading account, trades a permitted product and makes a net trading gain of ₹1,00,000.
Trader B: Prop firm
Trader B completes a prop-firm programme and receives a ₹1,00,000 payout under the firm’s agreement.
The bank statement may show a similar-looking credit, but the economic source is different.
Trader A has a trading result from personal capital.
Trader B has a payment arising from the prop firm’s contractual payout arrangement.
That difference matters when you maintain records and discuss the transaction with your CA.
Why Prop Firm Payouts Need Separate Attention
There is no special universal Indian tax label that you should simply apply to every “prop firm payout.”
A prop firm’s legal agreement can matter.
Questions that can change the analysis include:
- Are you trading live capital or a simulated account?
- Does the firm pay you a share of trading performance?
- Are you providing services under an agreement?
- Where is the firm legally located?
- Who is the counterparty to your agreement?
- How is the payment described in the payout statement?
- Are you an individual or operating through a business entity?
- Do you regularly carry out the activity as a business?
Because of these differences, an Indian trader should not copy another trader’s tax classification without checking the actual contract.
Does a Prop Firm Payout Automatically Become Salary?
No.
A payment from a prop firm is not automatically salary simply because you receive it regularly.
Salary normally arises from an employer-employee relationship. A prop firm trader may instead be operating under a contractor, revenue-share, performance-based or other contractual arrangement.
The actual agreement and relationship matter.
If you are unsure, show the complete prop-firm agreement and payout statement to your CA rather than describing the payment as “salary” simply because it arrives every month.
Does a Prop Firm Payout Automatically Become Capital Gains?
Not necessarily.
Capital gains generally relate to profits or gains from the transfer of a capital asset. The Income Tax Department describes capital gains under that framework.
A prop-firm payout is not automatically a capital gain just because the firm calls the activity trading.
The underlying contractual arrangement needs to be examined.
Could a Prop Firm Payout Be Business or Professional Income?
It may be possible depending on the facts, but do not treat that as a universal rule.
The Income Tax Department states that profits and gains of a business or profession are chargeable under that head, including profits and gains of a business or profession carried on by the assessee.
If your prop-firm activity is organised and carried out as a regular income-generating activity, your CA may consider business/profession treatment, but the correct classification depends on the contractual facts and applicable law.
This is exactly why the contract is important.
What About “Other Sources”?
Some traders assume that if something is not salary or capital gains, it must automatically be “other sources.” That is not a safe approach.
“Income from other sources” is a residual category. You should first determine whether the income properly belongs under another applicable head.
Do not select a tax head simply because it sounds convenient.
Forex Trading Income Can Also Be Different Depending on the Product
The word “forex” covers different products and markets.
An Indian trader could be referring to:
- Currency derivatives on a recognised Indian exchange
- Permitted forex transactions through authorised persons
- Spot/CFD products offered by an overseas platform
- Other leveraged products
These are not interchangeable from a legal or tax perspective.
Before discussing tax, first identify what instrument you actually traded, through which entity, and under what legal framework.
Important RBI Point for Indian Forex Traders
This is where many online articles become misleading.
The RBI says resident persons can undertake forex transactions only with authorised persons and for permitted purposes under FEMA. It has also cautioned residents against unauthorised electronic trading platforms and stated that remittances for margins to overseas exchanges or overseas counterparties are not permitted under the LRS framework.
Therefore, you should not assume that an overseas forex broker is acceptable simply because it accepts Indian customers or lets you withdraw money.
The tax question and the legality/compliance question are separate questions.
Something being taxable does not automatically mean the underlying activity was permitted.
What About Prop Firms Based Outside India?
This requires extra care.
Many prop firms used by retail traders are incorporated outside India.
If an Indian resident receives money from an overseas firm, there can be foreign-income, banking, documentation and tax-reporting questions depending on the facts.
The Income Tax Department’s current foreign income/asset guidance says residents with foreign income or foreign assets may have disclosure obligations and identifies Schedule FSI for foreign-source income and Schedule FA for foreign assets where applicable. It also notes that ITR-1 and ITR-4 do not contain Schedule FA/FSI.
That does not mean every prop payout automatically requires Schedule FA. A payment is not the same thing as holding a foreign asset. Your actual facts determine the disclosure requirements.
This is another reason not to copy an ITR filing strategy from another trader.
Prop Firm Payout vs Withdrawal From Your Own Broker
These terms are often mixed up.
| Transaction | What it generally represents |
|---|---|
| Withdraw ₹1,00,000 from your own trading account | Movement of your own account balance to your bank; the underlying trading result is the important tax question |
| Receive ₹1,00,000 prop payout | Payment from a prop firm under its contractual payout terms |
| Deposit ₹1,00,000 into your broker | Funding your trading account; not automatically trading income |
| Pay a prop challenge fee | An expense/payment under the prop-firm programme; whether and how it is deductible depends on the applicable tax treatment |
A bank statement alone cannot explain the complete tax character of these transactions.
Is the Full Prop Firm Payout Taxable?
Do not use a simple “yes, every rupee is taxable” or “no, only the profit is taxable” rule without examining the arrangement.
The correct answer depends on what the payment represents, how the contract works and how the income is classified.
For example, if a firm pays a trader a contractual share of eligible performance, the agreement may be important evidence of what the payment represents.
Keep the payout statement rather than relying only on the amount visible in your bank account.
What About the Prop Firm Challenge Fee?
Suppose you pay ₹10,000 to enter a challenge and later receive ₹1,00,000 in payouts.
Do not automatically subtract ₹10,000 from ₹1,00,000 and declare ₹90,000 as taxable income.
Whether a challenge fee is deductible depends on the applicable tax treatment and whether the expense meets the relevant requirements.
The safest approach is to keep the invoice/receipt and ask your CA whether it is allowable in your particular case.
What Records Should Indian Prop Traders Keep?
Good documentation can save a lot of trouble later.
Keep your prop-firm agreement
Save the terms and conditions that were applicable when you joined the programme.
Keep challenge-fee receipts
Download the invoice or payment confirmation.
Keep payout statements
Record every payout, its date, currency and amount.
Keep bank statements
Save the Indian bank credit showing the incoming payment.
Keep payment-provider records
If a third-party payment service was used, retain its transaction confirmation.
Keep trading/account reports
Save dashboard reports showing the account, performance and payout calculation.
Keep exchange-rate evidence
If a foreign-currency payout is converted into INR, maintain enough information to explain the INR value used for your records.
Why Currency Conversion Matters
Suppose a prop firm pays you USD 1,000.
Your Indian bank may ultimately credit an INR amount after conversion.
Do not simply use an arbitrary USD/INR rate months later and expect the numbers to reconcile.
Keep the payment date, foreign-currency amount, INR amount received and relevant bank/payment statement.
If your CA needs a particular exchange-rate methodology for the relevant tax computation, follow that professional guidance.
Example: Own Trading vs Prop Firm
| Example | Own Account Trader | Prop Trader |
|---|---|---|
| Starting arrangement | ₹2,00,000 personal capital | Prop programme with a challenge fee |
| Trading result | ₹50,000 net gain | Firm calculates an eligible payout |
| Cash received | Trader may withdraw part of account balance | Trader receives contractual payout |
| Main evidence | Broker statement and trade history | Agreement, payout statement and payment record |
| Tax question | How should the trading activity be classified? | What is the legal/economic nature of the payout? |
Notice the difference: the first trader owns the trading account and its economic result. The second receives a payment according to a separate agreement.
Does the Payout Date Matter?
Yes, the timing of income recognition can matter, but the correct rule depends on the nature and accounting/tax treatment of the income.
Do not assume that the date you click “withdraw” is always the only relevant date.
Keep both:
- The date the payout became due/was approved
- The date the money was actually received
Your CA can determine which date is relevant for your particular tax treatment.
What If You Receive Payouts Every Month?
Regular payouts make documentation even more important.
If you receive ₹50,000 every month, for example, maintain a monthly ledger:
| Month | Gross payout | Currency | INR received | Fees | Reference |
|---|---|---|---|---|---|
| April | USD 600 | USD | Record actual credit | Record | Payout ID |
| May | USD 750 | USD | Record actual credit | Record | Payout ID |
| June | USD 500 | USD | Record actual credit | Record | Payout ID |
This is much easier than trying to reconstruct twelve months of transactions when filing your return.
Can You Treat Prop Firm Payouts as “Trading Profit” in Your Records?
You can use a simple internal label such as “prop payout” for bookkeeping, but do not let that label decide the tax classification.
Your records should ideally distinguish:
- Personal trading profits/losses
- Prop firm payouts
- Challenge/evaluation fees
- Platform/payment fees
- Bank charges
- Currency conversion differences
This makes the underlying transaction much easier for a tax professional to review.
Can Prop Firm Losses Be Set Off Against Forex Trading Profits?
Do not assume they can.
Set-off and carry-forward rules depend on the nature of each item of income/loss and the applicable provisions.
A prop challenge fee, a failed evaluation, a personal trading loss and a prop payout are not automatically one combined trading P&L.
Keep them separate until your CA determines the appropriate treatment.
What About GST?
This can become relevant when a person’s activity is treated as a supply of services or business activity, particularly where an overseas entity is involved.
However, you should not assume that every prop trader automatically has a GST liability or that every payout is an export of service.
The exact contractual relationship, place-of-supply rules, registration threshold and nature of the activity need to be examined.
If your prop payouts are regular or substantial, ask a CA who understands both income tax and GST to review the agreement.
What About TDS?
A foreign prop firm paying an Indian trader may not operate like an Indian employer or Indian company making a normal domestic payment.
Do not assume that the absence of an Indian TDS certificate means the income is not taxable.
Likewise, do not assume that every foreign payment is subject to a particular withholding mechanism without checking the transaction.
Your responsibility to report taxable income is separate from whether the payer deducted Indian tax.
Foreign Income Does Not Mean Tax-Free Income
This is one of the most common misunderstandings.
If an Indian resident receives income from an overseas entity, the fact that the money was paid in USD or came from outside India does not automatically make it tax-free.
The Income Tax Department specifically publishes guidance on foreign income and foreign assets for Indian residents and notes that foreign income can require disclosure in the appropriate return where applicable.
Always determine the tax treatment from the nature of the income, not simply the country from which the payment arrived.
Do Prop Firm Payouts Need Foreign-Income Reporting?
Potentially, depending on the facts.
For example, if the payer is an overseas entity and the income is treated as foreign-source income, your return may require the relevant foreign-income reporting.
The Income Tax Department says Schedule FSI is used for income accrued or earned from sources outside India and details of tax relief, where applicable. It also says Schedule FA is for foreign assets and income arising from those assets.
But do not confuse foreign income with foreign asset ownership. Receiving a payout from a foreign company does not automatically mean you own a foreign asset.
What ITR Should a Prop Trader File?
There is no universal “prop trader ITR.”
The Income Tax Department’s current guidance says ITR-3 is applicable to individuals/HUFs having income under the head “Profits and Gains of Business or Profession,” while ITR-2 applies to individuals/HUFs with income other than business or profession income.
Therefore, do not choose ITR-3 just because you trade, and do not choose ITR-2 just because the prop firm is foreign.
Determine the nature of the income first.
What About Presumptive Taxation?
This is another area where traders should be careful.
The Income Tax Department describes presumptive taxation provisions for eligible businesses and professions, but eligibility depends on the nature of the activity and statutory conditions.
Do not automatically apply a presumptive percentage to a prop-firm payout simply because someone online says “prop traders use 44AD.”
Ask a CA to confirm whether the activity actually qualifies and how the gross receipts should be treated.
Why You Should Not Copy a YouTube Trader’s Tax Strategy
You may see videos saying:
- “Prop firm payouts are always business income.”
- “Prop payouts are always other income.”
- “Just use ITR-3.”
- “Just pay tax on the money received.”
- “Foreign payouts are tax-free.”
These statements are too broad.
Two traders can receive similar payouts while having different contracts, business structures, residency facts or activities.
Use online content to understand the questions you need to ask—not as a substitute for reviewing your actual documents.
A Practical Tax File for an Indian Prop Trader
Create one folder for each financial year.
Inside it, keep:
- Prop firm agreements
- Challenge/evaluation invoices
- Payout approvals
- Payout statements
- Bank statements
- Payment-provider statements
- Trading dashboard reports
- Currency conversion records
- Broker statements for any separate personal trading
- Tax-return working papers
- CA correspondence
This can turn a confusing foreign-payment trail into a clean record.
How to Explain a Prop Firm Payout to Your CA
Do not simply say:
“I made ₹10 lakh from forex.”
Instead, explain the transaction:
“I entered a prop-firm programme under this agreement, paid this evaluation fee, traded under these rules, became eligible for these payouts, and received these amounts from this foreign entity through this payment method.”
Then give the CA the documents.
That gives them the information needed to analyse the transaction properly.
Own Forex Trading and Prop Trading Can Exist Together
You do not have to choose one.
An Indian trader could theoretically have:
- Personal trading activity
- Prop-firm payouts
- Salary from employment
- Other investment income
Each stream should be tracked separately.
Combining everything into one “trading income” number can make tax reporting and recordkeeping unnecessarily difficult.
What Happens When You Withdraw a Prop Firm Payout?
There are two different events to track:
Event 1: The prop firm approves the payout.
Event 2: The payment reaches your Indian bank account.
The second event can involve a payment provider, foreign bank, currency conversion and Indian bank processing.
Keep the payout approval and the bank-credit evidence together.
Example: USD Prop Firm Payout to India
Imagine a prop firm approves a USD 2,000 payout.
The payment is sent to a supported payment provider, converted or settled into INR, and finally credited to your Indian bank.
Your records should show:
| Record | Example |
|---|---|
| Prop payout approved | USD 2,000 |
| Approval date | Record date |
| Payment reference | Record reference |
| Bank credit | Record actual INR amount |
| Conversion details | Keep bank/payment statement |
| Contract | Keep the applicable prop agreement |
This is far better evidence than a screenshot showing only “Payout successful.”
Five Questions to Ask Before Joining a Prop Firm
- Who is the legal entity I am contracting with?
- What exactly am I being paid for?
- Is the trading account live, simulated or another model?
- How are payouts calculated?
- What documents will I receive for each payout?
Also check where the company is incorporated and how it handles payments to Indian residents.
Five Questions to Ask Your CA
- How should my prop-firm payout be classified?
- Which ITR is appropriate for my complete income profile?
- Are my challenge/evaluation fees deductible?
- Do foreign-income or foreign-asset schedules apply to my facts?
- Do GST or other compliance requirements apply to my arrangement?
Give the CA the actual agreement rather than only a payout screenshot.
Forex Income vs Prop Firm Payouts: The Easy Way to Remember It
Own trading: You use your own account and your trading activity creates the economic result.
Prop firm: You participate in a firm’s programme and receive money according to the firm’s contractual payout rules.
Tax: Do not decide the tax head from the words “forex” or “prop firm.” Look at the actual transaction, contract and applicable Indian tax rules.
Compliance: Taxability and legality are separate. An income being taxable does not automatically make the underlying forex activity permitted.
Frequently Asked Questions
Are prop firm payouts and forex trading profits the same in India?
No. They can have different economic sources. Personal forex trading profits arise from your own trading activity, while a prop payout generally arises under a contractual arrangement with the prop firm.
Are prop firm payouts taxable in India?
A payout received by an Indian resident can have Indian tax implications, but the exact classification and computation depend on the facts. Do not assume that foreign origin makes it tax-free.
Are prop firm payouts business income?
They may be treated as business/profession income in some fact patterns, but there is no universal rule that every prop payout must be classified that way. The contract and nature of the activity should be reviewed.
Are prop firm payouts capital gains?
Not automatically. Capital gains generally relate to gains from transfer of capital assets. A contractual prop payout is not automatically a capital gain.
Are prop firm payouts salary?
Not automatically. Salary generally involves an employer-employee relationship. A prop firm’s contractual payout can have a different legal character.
Does receiving a prop payout from a foreign company make it foreign income?
It can raise foreign-source income and reporting questions depending on the facts and the payer’s location. Keep the agreement, payout statement and payment records and ask a tax professional to confirm the applicable reporting.
Which ITR should an Indian prop trader use?
There is no special prop-trader ITR. The correct form depends on your overall income and whether the income falls under business/profession or another applicable head.
Can I deduct a prop firm challenge fee?
Do not automatically deduct it. Whether the fee is allowable depends on the applicable tax treatment and the relevant conditions.
Can I combine my prop payout with my personal forex profit?
Keep them separate in your records. Your CA can determine the appropriate treatment when preparing the return.
Is prop trading legal for Indian residents?
Do not answer this with a blanket yes or no for every prop firm. The firm’s structure, the actual trading activity, payment arrangement and applicable RBI/FEMA rules matter. RBI says residents should undertake forex transactions only with authorised persons and for permitted purposes, and it cautions against unauthorised electronic trading platforms.
Final Takeaway
Forex trading income and prop firm payouts may look similar in your bank account, but they are not automatically the same type of income.
When you trade your own account, the key issue is the nature of your own trading activity and its resulting profit or loss. When you use a prop firm, the key issue is the contractual relationship and what the payout actually represents.
For Indian traders, keep these two streams separate. Save your broker statements for personal trading and your prop-firm agreement, challenge invoices, payout statements and bank records for prop trading.
The Income Tax Department’s current guidance recognises different income heads and different ITR forms depending on whether income is from business/profession, capital gains or other sources.
And do not forget the separate RBI/FEMA question. RBI states that resident persons can undertake forex transactions only with authorised persons and for permitted purposes, and warns against unauthorised electronic trading platforms.
If your prop payouts are regular or substantial, give your CA the actual prop-firm contract before deciding how to report them. That is much safer than copying a tax formula from another trader on YouTube or Telegram.
Official Sources
- Income Tax Department — Treatment of Income From Different Sources
- Income Tax Department — Individuals With Business/Profession Income
- Income Tax Department — ITR-2 FAQs
- Income Tax Department — Foreign Assets and Income Guidance
- RBI — Caution Against Unauthorised Forex Trading Platforms
Risk disclosure: This article is for general educational information and is not tax, legal, financial or accounting advice. Prop-firm contracts and payout structures differ, and Indian tax and foreign-exchange rules can change. Before filing a return or making a significant prop-firm payout withdrawal, consult a qualified Indian CA/tax professional with your actual agreement and payment records.