One of the most important questions for a futures trader is not simply how much margin a broker or prop firm allows, but how many futures contracts can you safely trade without taking disproportionate risk. The answer depends on your account size, drawdown limit, contract value, stop-loss distance, market volatility and the amount you are willing to lose on one trade.
CME Group explains that position sizing should be based on account size and individual risk parameters. It also notes that traders should size positions from realistic risk scenarios rather than simply using the maximum number of contracts permitted by margin requirements. CME Group position and risk management guidance.
There Is No Universal Safe Number of Futures Contracts
There is no single contract number that is safe for every trader. One contract can be too large for one account and relatively small for another. The same account can also support different contract counts depending on the product.
For example, CME lists the E-mini S&P 500 (ES) at $50 per index point and the Micro E-mini S&P 500 (MES) at $5 per index point. That means the same index move creates roughly ten times the dollar exposure in one ES contract compared with one MES contract.
Therefore, “I can trade five contracts” is not a meaningful risk statement until you specify the product, stop distance and account drawdown.
The Core Formula for Futures Contract Sizing
A practical starting point is:
Maximum Contracts = Maximum Dollar Risk ÷ Risk Per Contract
And:
Risk Per Contract = Stop Distance × Dollar Value Per Point
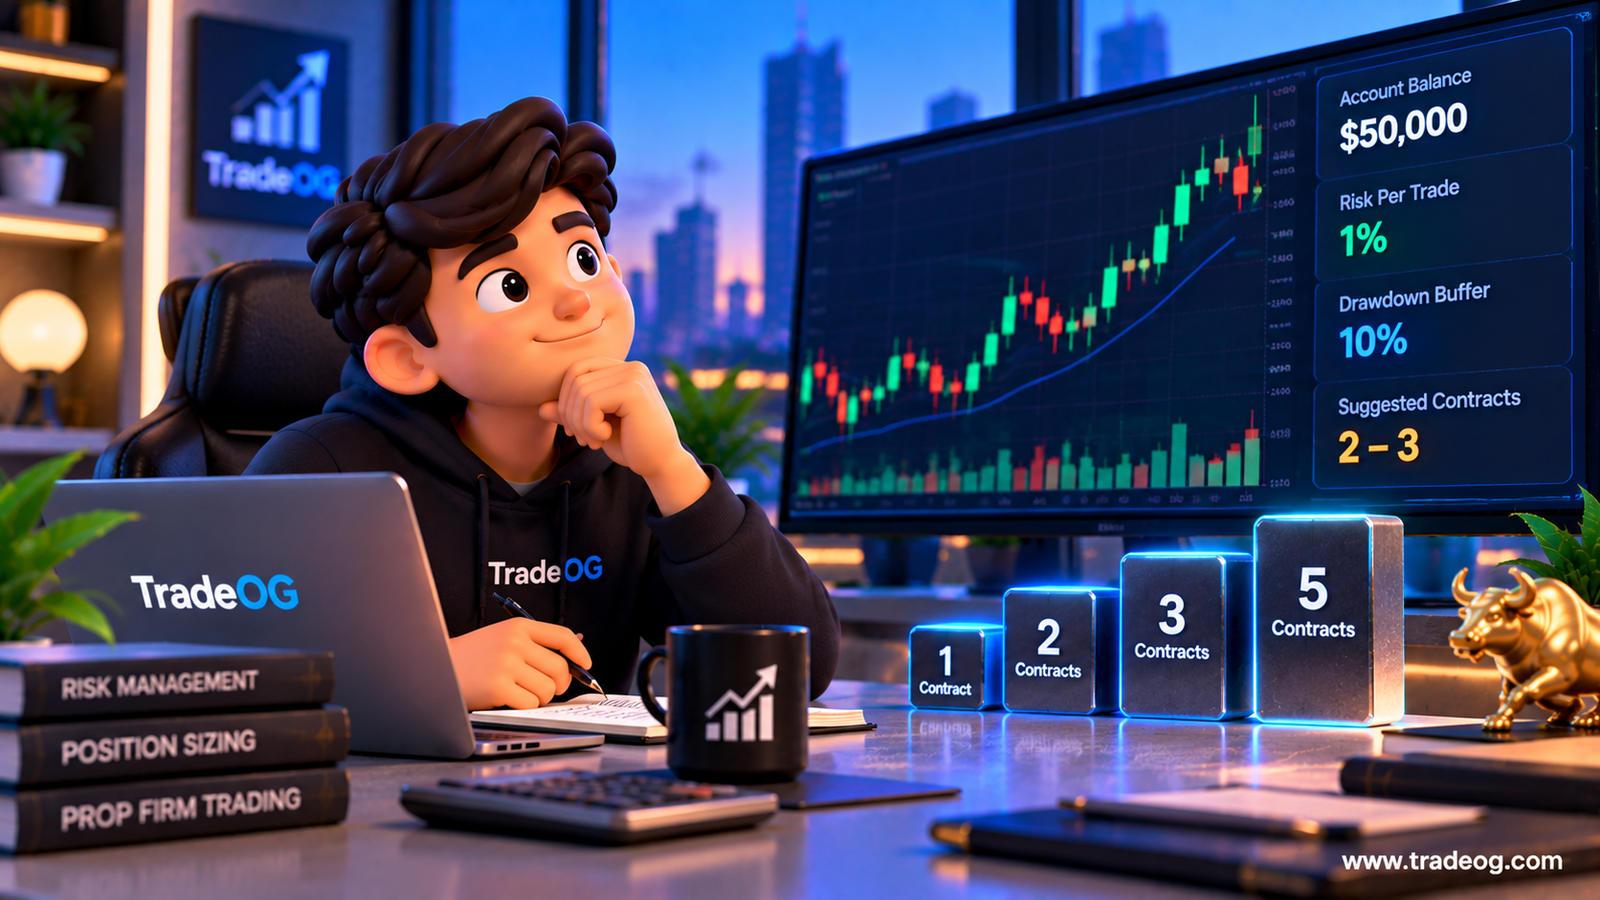
For example, suppose your planned trade risks $100 per contract. If your maximum acceptable loss is $300, the mathematical position-size limit is three contracts:
$300 ÷ $100 = 3 contracts
This is a risk calculation, not a recommendation. Your actual size should also account for slippage, commissions, volatility and the specific rules of your broker or prop firm.
Example: ES Contract Sizing
Suppose one ES contract is worth $50 per index point and your technical stop is 5 points away.
5 points × $50 = $250 risk per ES contract
If your maximum planned loss for the trade is $500:
$500 ÷ $250 = 2 ES contracts
But that calculation assumes the stop executes exactly where expected. During fast markets, actual execution can differ from the stop price because of slippage or gaps. A trader therefore needs a buffer rather than sizing right up to the theoretical maximum.
Example: MES Gives More Position-Sizing Granularity
MES is worth $5 per point. With the same 5-point stop:
5 points × $5 = $25 risk per MES contract
With a $500 maximum planned loss, the mathematical limit would be 20 MES contracts. That does not mean 20 contracts are automatically appropriate. The purpose of the smaller contract is that it allows finer position sizing.
A trader could use 4, 6, 8 or another contract count to adjust exposure more gradually than with ES. CME notes that contract choice and the number of contracts are important variables in managing futures risk.
Why Prop Traders Need a Different Calculation
For a prop firm challenge or funded account, the headline account size is not necessarily the amount you can afford to lose. The more important figure is often the remaining distance to the firm’s loss or drawdown threshold.
Imagine a hypothetical $50,000 prop account with a $2,500 maximum loss limit. If the account has already lost $800, only $1,700 of the original drawdown room remains.
If you risk $250 per trade, the theoretical remaining capacity is:
$1,700 ÷ $250 = 6.8R
That does not mean you should take 6 or 7 consecutive trades at that risk. It simply shows why the remaining drawdown buffer matters more than the headline account balance.
Contract Count Should Be Based on Risk, Not Margin
Futures use margin, which can make a position appear affordable because you control a larger notional value with a smaller amount of posted capital. CME specifically warns traders to consider contract size and risk rather than simply trading the maximum quantity allowed by initial margin.
For a prop trader, this distinction is especially important. A firm may permit a certain maximum contract count, but the maximum allowed quantity is a rule boundary—not necessarily a sensible position size for every setup.
Use the Stop Distance to Calculate Size
Your stop distance can completely change the correct contract count.
| Product | Example Value/Point | Stop | Risk per Contract |
|---|---|---|---|
| ES | $50 | 5 points | $250 |
| MES | $5 | 5 points | $25 |
| NQ | $20 | 10 points | $200 |
| MNQ | $2 | 10 points | $20 |
The values above illustrate why contract size matters. CME’s current equity-futures materials list ES at $50 per point, MES at $5, NQ at $20 and MNQ at $2 per point. Always verify the current contract specifications before trading.
What Percentage of Your Account Should One Trade Risk?
There is no universally correct percentage. A trader might define a fixed dollar risk, a percentage of the remaining drawdown buffer, or another risk framework. The important point is consistency and the ability to survive a normal sequence of losing trades.
For example, if a prop trader has $2,000 of remaining drawdown room and chooses a hypothetical $100 risk per trade, one losing trade consumes 5% of the remaining buffer. If the same trader increases the risk to $300, one loss consumes 15% of the remaining buffer.
The second position is not automatically wrong, but it produces a much faster drawdown path if several trades fail.
Account Balance vs Remaining Drawdown
When calculating futures size for a prop account, track at least these numbers:
- Current account balance
- Current equity
- Maximum loss or drawdown threshold
- Remaining drawdown buffer
- Dollar risk per contract
- Planned number of contracts
- Expected slippage and trading costs
A simple framework is:
Remaining Buffer = Current Equity − Current Drawdown Threshold
Then compare the planned trade’s worst-case loss with that buffer before placing the order.
Volatility Can Change the Safe Contract Count
A position that looks reasonable during a quiet session can become much more aggressive during a high-volatility event. CPI, employment data, central-bank decisions, major earnings releases and unexpected geopolitical events can produce rapid price movement and execution slippage.
CME’s risk-management guidance emphasizes that different futures markets have different volatility and tick-value characteristics. The number of contracts should therefore be considered together with the behavior of the specific market.
Do Not Ignore Slippage
The basic position-sizing formula often assumes that your stop executes at the exact intended price. Real markets do not guarantee that outcome.
If your calculated risk is $100 per contract but a fast market produces an additional $20 of slippage, your realized loss can be greater than the planned $100. The more contracts you hold, the more the dollar impact of execution differences can multiply.
This is one reason why leaving a risk buffer below the theoretical maximum is important.
How Many Futures Contracts Can You Safely Trade?
Use this sequence before every trade:
- Identify the futures product.
- Confirm the current dollar value per point or tick.
- Set the technical stop distance.
- Calculate dollar risk per contract.
- Determine your maximum acceptable trade loss.
- Divide maximum trade risk by risk per contract.
- Round down to a whole contract.
- Check the prop firm’s contract and volatility rules.
- Leave room for slippage and execution costs.
For example, if your maximum planned risk is $300 and each contract risks $85 at the chosen stop, the mathematical result is 3.52 contracts. Because futures contracts are whole units in the normal order-entry process, you would round down to 3 contracts rather than 4. Three contracts would have a planned risk of $255 before costs and slippage.
Common Mistakes New Futures Traders Make
Trading the Maximum Allowed Contracts
A prop firm’s maximum contract limit is not the same thing as a personalized risk limit.
Using Account Size Alone
A $50,000 account label does not tell you how much drawdown room remains. Always check the actual loss threshold.
Ignoring the Stop Distance
Two trades using the same contract count can have completely different risk because their stop distances differ.
Switching From Micro to Mini Without Recalculating
Moving from MES to ES or MNQ to NQ can multiply dollar exposure substantially. Recalculate the risk before changing contracts.
Ignoring Volatility
Fast markets can increase realized losses through larger price swings and slippage.
Final Takeaway
The safest contract count is not determined by the maximum quantity your platform allows. It is determined by the relationship between your remaining risk capital, stop distance, contract value, volatility and trading rules.
CME Group’s position-management guidance emphasizes choosing the number of contracts based on risk scenarios rather than simply using maximum margin capacity. For prop traders, the same principle can be applied to the firm’s drawdown threshold: calculate the dollar risk of the position first, then choose the contract count.
Before entering a futures trade, ask one simple question: “If my stop is hit with some slippage, can my remaining drawdown comfortably absorb the loss?” If the answer is unclear, reduce the position size or reassess the setup.