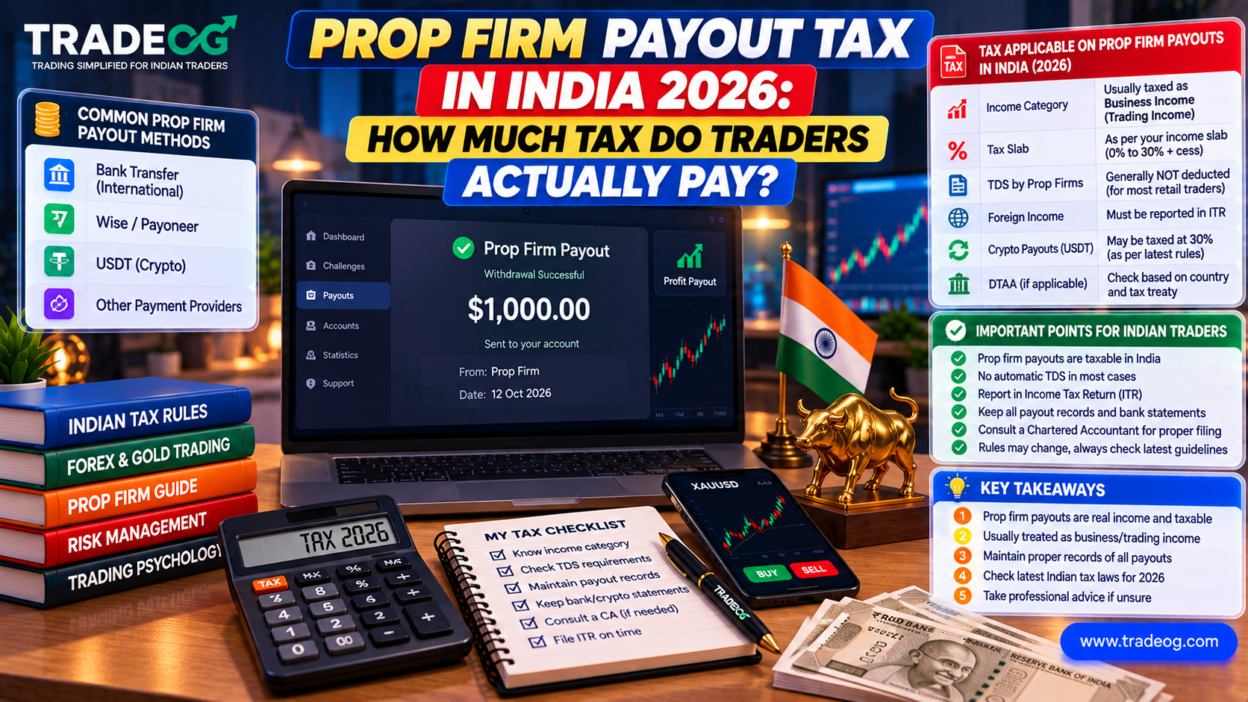
Do Indian traders have to pay tax on prop firm payouts in 2026? In most cases, a payout that represents income earned from a prop-firm arrangement should not simply be ignored because it arrives from an overseas company or through a payment provider. The exact Indian tax treatment depends on the legal and contractual nature of the arrangement, your residential status, how the income is characterized, how it is received, and whether any foreign tax has already been paid.
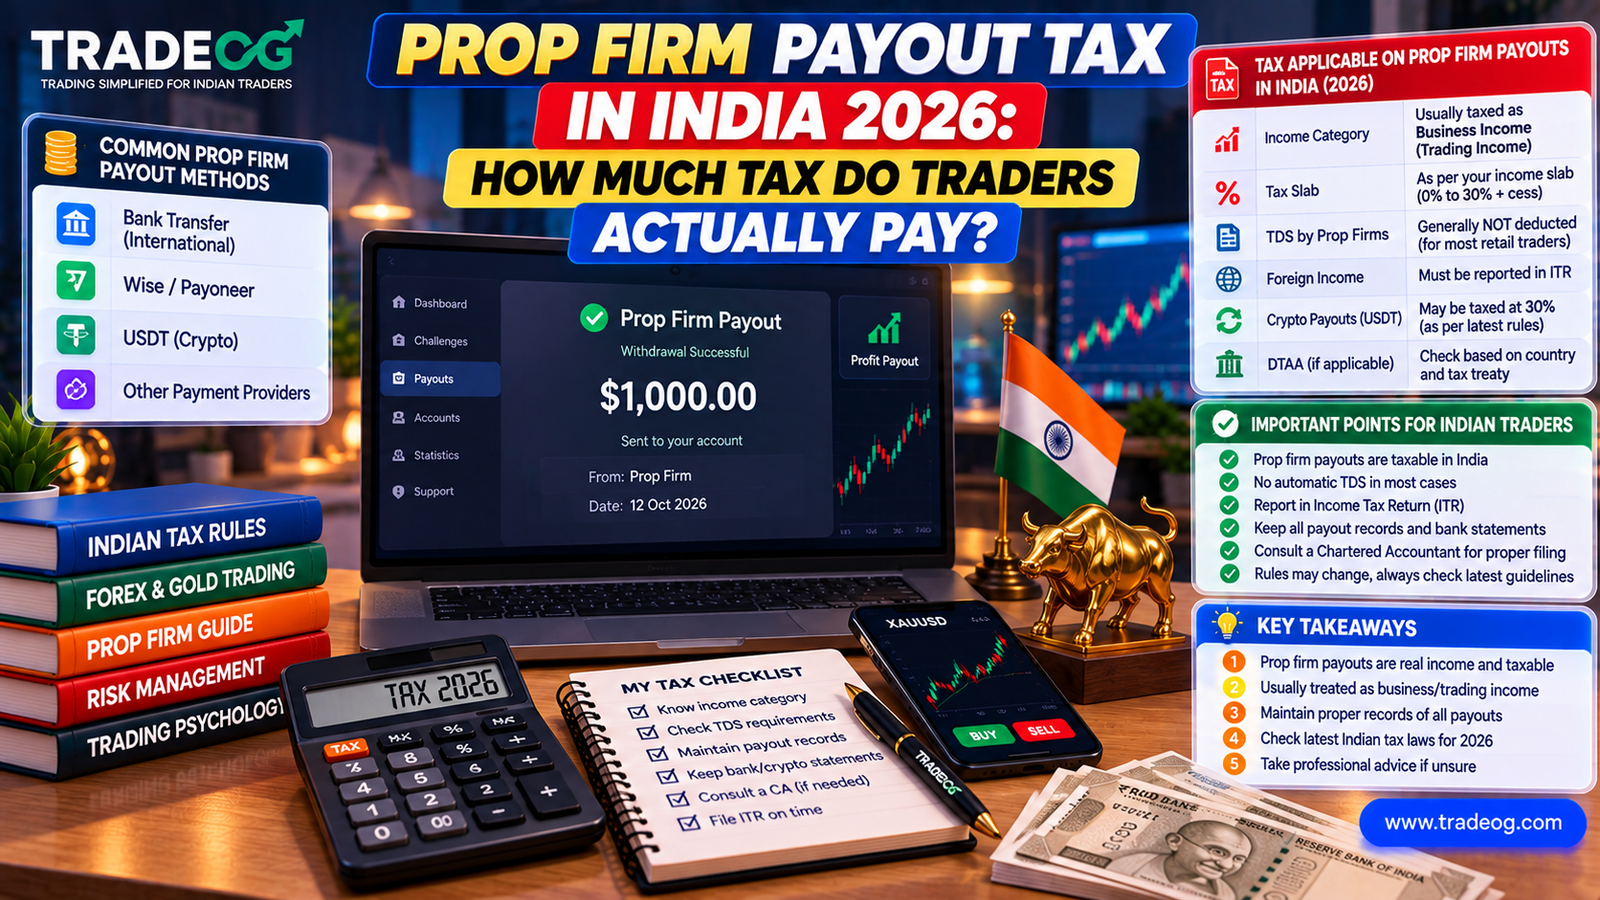
That is why there is no single government-defined “prop firm payout tax rate” for every Indian trader. For many traders, the practical starting point is to examine whether the payout is business/professional income or another category, then apply the rules that actually fit the facts.
Is a Prop Firm Payout Taxable in India?
For an Indian resident, the fact that a prop firm is based outside India does not automatically make the payout tax-free. The Income Tax Department states that foreign income can include income from sources outside India, including business or professional income, and residents with foreign income or foreign assets may have additional reporting obligations. See the Income Tax Department guidance on foreign assets and income.
At the same time, you should not assume that every prop-firm payout is automatically classified as “foreign income” in exactly the same way. The source and character of income depend on the underlying transaction and contractual relationship. That distinction matters when deciding which ITR schedules and tax provisions apply.
There Is No Special “Prop Firm Tax” Slab
One of the biggest misconceptions among traders is that India has a separate fixed tax rate for prop-firm payouts. There is no general provision that simply says “prop firm payout = 30% tax.”
If the payout is treated as ordinary business/professional income, the applicable tax can depend on your total taxable income and the tax regime, along with deductions, allowable business expenses where applicable, surcharge and cess.
For reference, the Income Tax Department’s published new-regime slab structure for AY 2026-27 is:
| Taxable Income | New-Regime Rate |
|---|---|
| Up to ₹4 lakh | Nil |
| ₹4 lakh–₹8 lakh | 5% |
| ₹8 lakh–₹12 lakh | 10% |
| ₹12 lakh–₹16 lakh | 15% |
| ₹16 lakh–₹20 lakh | 20% |
| ₹20 lakh–₹24 lakh | 25% |
| Above ₹24 lakh | 30% |
The Income Tax Department states that resident individuals can receive a section 87A rebate of up to ₹60,000 where taxable income does not exceed ₹12 lakh under the new regime, subject to the applicable conditions. Health and Education Cess is 4% on income tax plus surcharge, if any. See the official AY 2026-27 tax guidance.
Do not read the table as a special prop-firm rate. It is the applicable individual tax slab structure for the relevant return/tax regime, not a separate tax on payouts.
Example: ₹10 Lakh of Prop Firm Income
Suppose, purely as an illustration, a resident individual has ₹10 lakh of taxable income for the year and the income is taxed under the new regime.
The slab calculation before rebate would be approximately:
- First ₹4 lakh: ₹0
- Next ₹4 lakh at 5%: ₹20,000
- Next ₹2 lakh at 10%: ₹20,000
- Total income tax before rebate: ₹40,000
If the taxpayer satisfies the section 87A conditions applicable to that year, the rebate can reduce the income-tax liability substantially or potentially to zero. The exact result depends on the taxpayer’s complete taxable-income position, not simply the amount of one prop-firm payout.
Example: ₹20 Lakh of Taxable Income
Using the same published new-regime slab structure as an illustration:
- ₹0–₹4 lakh: ₹0
- ₹4–₹8 lakh at 5%: ₹20,000
- ₹8–₹12 lakh at 10%: ₹40,000
- ₹12–₹16 lakh at 15%: ₹60,000
- ₹16–₹20 lakh at 20%: ₹80,000
- Tax before cess: ₹2,00,000
- 4% cess: ₹8,000
- Illustrative total: ₹2,08,000
This is only a slab illustration. It does not decide whether a particular trader can claim expenses, presumptive taxation, foreign-tax credit, rebates or other reliefs.
What If Your Prop Firm Pays You in USD?
Receiving a payout in USD does not create a separate “USD tax.” The underlying income is what matters.
If a foreign prop firm sends USD to your Indian bank account, maintain the payout statement, payment confirmation, bank credit, exchange-rate conversion record and relevant agreement. For Indian tax reporting, foreign-currency amounts need to be converted into INR using the applicable rules and prescribed exchange-rate methodology.
Also remember that a bank transfer is evidence of the movement of money; it does not by itself determine the correct income classification.
Does a Foreign Prop Firm Payout Need Foreign Income Reporting?
This is an area where traders should be particularly careful.
The Income Tax Department’s foreign-income guidance says residents with foreign income or foreign assets may need to provide details through the appropriate ITR schedules. Schedule FSI is used for income accruing or arising from a source outside India, while Schedule FA covers specified foreign assets and foreign accounts. See the official ITR-2 guidance and foreign-income disclosure guidance.
Whether your particular prop-firm arrangement requires a specific foreign-income or foreign-asset disclosure depends on the facts. Do not automatically assume that every payout means you have a foreign bank account or foreign asset, but do not ignore the reporting question either.
Which ITR Should a Prop Firm Trader Use?
If the payout is properly characterized as income from business or profession, ITR-3 is generally the relevant return for individuals/HUFs with business or professional income who are not eligible for the simpler forms.
The Income Tax Department describes ITR-3 as applicable to individuals and HUFs having income under the head “Profits or Gains of Business or Profession.” ITR-4 is a simplified option for eligible resident taxpayers using presumptive taxation under sections such as 44AD/44ADA/44AE and meeting the other conditions. See the official business/profession ITR guidance.
There is an important catch for foreign-source income: the Department’s ITR-4 guidance says ITR-4 cannot be used by a person having income from any source outside India. Check the official ITR-4 eligibility conditions before choosing the form.
Therefore, a trader should not choose ITR-4 merely because the payout looks like business income. Eligibility must be checked against the complete facts.
Can Prop Firm Traders Use Section 44AD?
Section 44AD is a presumptive taxation provision for eligible businesses, but eligibility is not automatic for every type of prop-firm arrangement.
The Income Tax Department’s ITR guidance recognizes 44AD as a presumptive business provision and states that the scheme has a gross-receipts limit of ₹3 crore under the applicable conditions. The CBDT’s ITR validation material also reflects the 6% presumptive-income rule for qualifying receipts received through specified banking/electronic modes and 8% for other modes. See the official 44AD FAQ for the applicable conditions.
However, whether a particular prop-firm payout qualifies as eligible turnover/gross receipts of a business for section 44AD is a fact-specific tax question. The prop firm’s agreement and the legal nature of the payout should be reviewed before using presumptive taxation.
Are Prop Firm Challenge Fees Tax Deductible?
This is another question where traders should avoid blanket claims.
If the activity is treated as a business, certain expenses can potentially be relevant under the normal business-income rules when they are incurred wholly and exclusively for the business and satisfy the applicable conditions. But the treatment of a prop-firm challenge fee depends on the facts and the chosen tax method.
If you are using a presumptive taxation scheme, you generally do not calculate taxable business profit by separately deducting every individual expense in the same manner as normal books-based computation.
So keep records of:
- Challenge/evaluation fees
- Reset or retry fees
- Platform and data charges
- Payment-provider charges
- Bank charges
- Software or trading tools used for the activity
- Payout statements
- Contracts and invoices
Keep the records even when you are not sure whether a particular cost will ultimately be deductible.
What About USDT or Crypto Prop Firm Payouts?
USDT payouts require extra care because there can be two different tax questions: the original income received from the prop-firm arrangement and any later transfer/disposal of the crypto asset.
India’s tax-return forms have a dedicated Schedule VDA for income from transfer of virtual digital assets under section 115BBH, and the notified return structure shows VDA transfer income being taxed at the special 30% rate. See the notified ITR form and Schedule VDA.
That does not mean every USDT prop-firm payout should simply be labelled “30% VDA income.” The underlying receipt and any subsequent crypto transfer need to be analyzed separately.
For example, if a payout is received in USDT and later converted into INR, the timing, value, cost basis and nature of each transaction can matter. Keep the wallet address, transaction hash, date/time, INR value, exchange statement and bank credit trail.
Does the 30% Crypto Tax Apply to the Whole Prop Firm Payout?
Not automatically. Section 115BBH specifically deals with income from the transfer of virtual digital assets. A prop-firm contractual payout is not automatically transformed into VDA income simply because the firm used USDT as the payment method.
The tax analysis can become more complicated when the trader receives a digital asset as consideration and subsequently transfers it. Because this area can involve both business-income and VDA rules, professional review is particularly useful for large or repeated USDT payouts.
Does the Prop Firm Deduct TDS?
Do not assume that a foreign prop firm will deduct Indian TDS from your payout.
Indian TDS obligations depend on the payer, recipient, payment type and applicable provisions. A foreign prop firm may not operate an Indian payroll or Indian TDS system for a trader in India. The absence of TDS therefore does not mean that the income is exempt from Indian tax.
Think of TDS and final income-tax liability as two different questions:
- TDS: Was tax required to be deducted at source?
- Final tax: How much tax is actually payable after applying the correct income classification, regime, deductions/rebates and credits?
What If Tax Was Already Paid in Another Country?
If the same income is subject to tax in another jurisdiction, the India-side analysis may involve a foreign tax credit and, where relevant, a Double Taxation Avoidance Agreement.
The Income Tax Department provides Schedule FSI for foreign-source income and Schedule TR for the summary of foreign-tax relief claimed in India. See the official ITR guidance on FSI and TR.
Do not simply subtract a foreign tax payment from your Indian tax bill. The amount of credit, eligible income, country, documentation and treaty provisions need to be checked.
How Much Tax Would You Pay on ₹1 Lakh, ₹5 Lakh or ₹10 Lakh Payouts?
A payout amount by itself is not enough to calculate the final tax because your other income matters.
| Annual Prop-Firm Payout | Can Final Tax Be Determined From Payout Alone? | Why? |
|---|---|---|
| ₹1 lakh | No | Total taxable income and eligibility for rebates matter. |
| ₹5 lakh | No | Salary, other business income and other income can change the result. |
| ₹10 lakh | No | Tax regime, total taxable income and rebate eligibility matter. |
| ₹20 lakh | No | Slab calculation, deductions/allowances where applicable and cess matter. |
| ₹50 lakh+ | No | Surcharge and reporting requirements can become relevant. |
This is why websites or social-media posts claiming “prop firm payouts are always taxed at exactly X%” should be treated cautiously.
What Happens If Your Total Income Crosses ₹50 Lakh?
Surcharge can apply when total income crosses specified thresholds. For individuals, the Income Tax Department currently lists surcharge rates under the new regime of 10% for income above ₹50 lakh up to ₹1 crore, 15% from ₹1 crore to ₹2 crore, and 25% above ₹2 crore under the applicable ranges. Health and Education Cess is 4% on income tax plus surcharge. Marginal relief can also apply in specified situations. See the official surcharge and cess guidance.
High-earning prop traders therefore need more than a simple “30% maximum slab” calculation.
Do You Pay Extra Tax Just Because the Money Came From Abroad?
There is no general rule saying that an ordinary foreign bank remittance automatically carries a separate extra income-tax rate merely because the money crossed the border.
The underlying income still needs to be correctly classified and reported. A bank may also ask for supporting documentation about the purpose and source of a foreign inward remittance.
For this reason, keep your payout statement, contract, payment confirmation, bank advice and correspondence with the prop firm together.
Documents Indian Prop Traders Should Keep in 2026
- Prop-firm agreement or terms of service
- Account/challenge ID and payout history
- Payout approval emails
- Invoices or payout statements, where issued
- Bank statements showing each credit
- Wise/Payoneer/payment-provider statements
- USDT wallet transactions, if applicable
- Exchange statements for crypto conversions
- INR conversion calculations
- Challenge and platform fee records
- Foreign tax certificates, if any
- Previous ITRs and tax-payment challans
Simple Tax-Compliance Workflow for Indian Prop Traders
- Identify the legal nature of the payout. Read the prop firm’s agreement instead of relying only on the word “profit.”
- Determine your residential status. This can materially affect foreign-income reporting.
- Total all relevant income. Do not calculate tax from the prop payout in isolation.
- Choose the correct tax regime and ITR. Business/professional income can affect which return is available.
- Convert foreign-currency receipts correctly. Keep the calculation supporting the INR amount.
- Review foreign-income reporting. Check Schedule FSI/FA requirements where applicable.
- Separate crypto transactions. USDT payouts and later crypto transfers should not be mixed into one unexplained number.
- Claim only supportable expenses or presumptive treatment. Do not invent deductions.
- Check foreign-tax credit. Use the appropriate documentation if tax was paid abroad.
- Maintain an audit trail. The payout amount in your bank account should be traceable to the prop-firm statement.
Common Mistakes Traders Make
“It Came From a Foreign Company, So It Is Tax-Free”
Being paid by a foreign company does not by itself establish tax exemption for an Indian resident.
“Every Prop Firm Payout Is Taxed at 30%”
There is no universal 30% prop-firm payout rate. Ordinary income may fall under the applicable slab system, while specific income categories can have special rates.
“No TDS Means No Tax”
TDS is a withholding mechanism, not a definition of whether income is taxable.
“USDT Means the Whole Payout Is VDA Income”
The special VDA regime concerns income from transfer of virtual digital assets. A payout arrangement involving USDT requires a transaction-by-transaction analysis.
“I Can File Any ITR I Want”
ITR selection depends on the type and source of income and other conditions. The Income Tax Department specifically distinguishes ITR-3 business/profession cases from ITR-4 presumptive cases and lists restrictions for foreign-source income. See the official ITR guidance.
Final Answer: How Much Tax Do Prop Firm Traders Actually Pay?
There is no single 2026 tax percentage that applies to every Indian prop-firm trader. If your payout is treated as ordinary business/professional income, the final tax can be driven by your total taxable income and applicable slab regime, along with rebate, cess, surcharge and any legally available deductions or other adjustments.
If the arrangement involves a foreign prop firm, foreign income, foreign tax, USDT or other crypto, the compliance analysis can become more complicated. The safest approach is to keep a complete payout trail and have the actual contract reviewed rather than choosing a tax category simply because another trader used it.
For Indian traders, the most important principle is simple: tax the underlying income correctly, document where it came from, and do not confuse payout method with tax classification.
For related TradeOG guides, see How Indian Traders Receive Prop Firm Payouts in 2026, Crypto vs Bank Transfer for Prop Firm Payouts, and Prop Firm Payout Verification Explained Step by Step.
Frequently Asked Questions
Is prop firm income taxable in India?
Generally, an Indian resident should not assume that prop-firm payouts are tax-free. The correct tax treatment depends on the nature of the arrangement and applicable Indian tax rules.
Is prop firm payout treated as business income?
It may be, but this is not a universal rule. The contractual relationship and actual activity should be reviewed before deciding the classification.
Is there a 30% tax on prop firm payouts?
Not as a general prop-firm rule. A 30% rate applies to certain specific income categories, including income from transfer of virtual digital assets under section 115BBH, but that does not automatically make every prop-firm payout VDA income.
Do I need to report foreign prop firm income?
If you are resident in India and have foreign-source income or relevant foreign assets/accounts, additional ITR reporting may apply. The exact schedules depend on your facts.
Does receiving USDT make the payout tax-free?
No. Payment in USDT does not create a blanket tax exemption. Both the underlying payout and any later transfer of the digital asset may need separate analysis.
Should I talk to a CA?
For occasional small payouts, you can start by understanding the applicable rules and keeping complete records. For repeated, high-value, foreign or USDT payouts, professional tax review is strongly advisable.
Risk and tax disclaimer: This article is for general educational information and does not constitute tax, legal, accounting, investment or financial advice. Indian tax rules, forms, rates, reporting requirements and interpretations can change. Always verify the latest provisions and obtain professional advice for your specific circumstances before filing an income-tax return.