

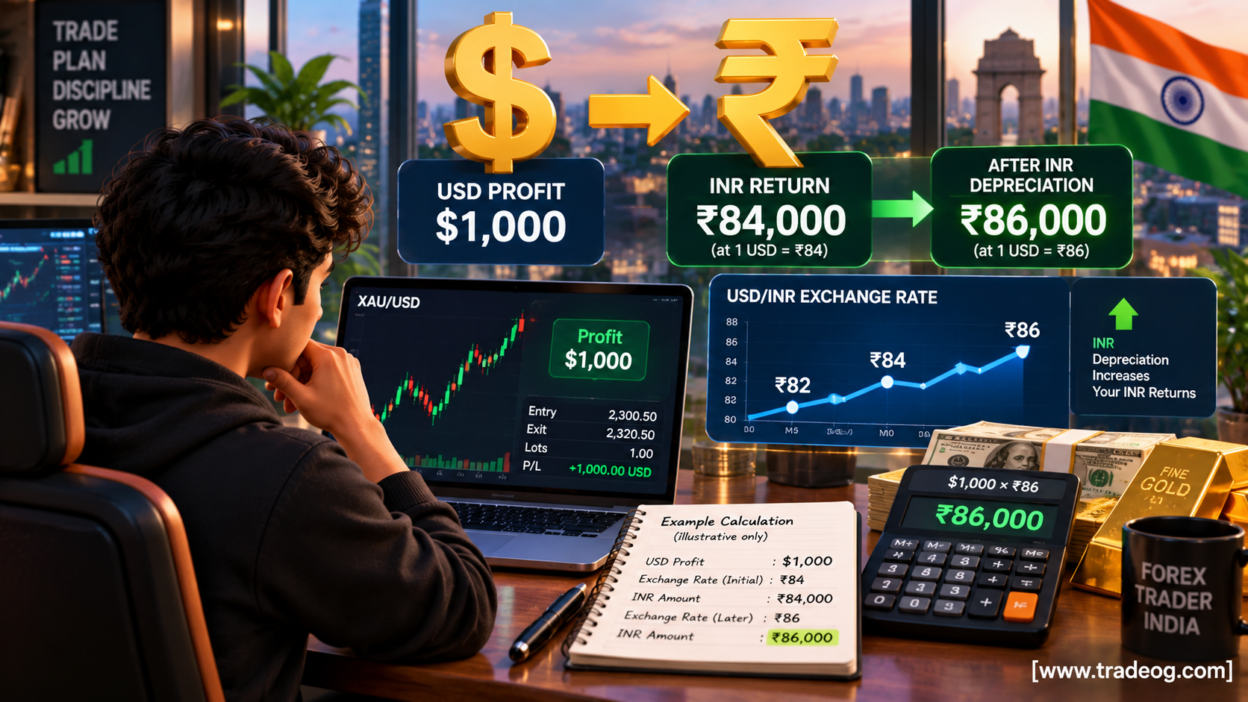
If you trade forex, prop firm accounts, or other USD-denominated instruments from India, your trading statement can tell only part of the story. A trader may make a profit in dollars, while the value of that profit in rupees changes because the USD/INR exchange rate moved during the same period.
That is why Indian traders should separate trading returns from currency returns. The distinction makes performance tracking much clearer. It helps you answer a simple question: Did I make more money because my trading improved, or because the foreign currency became more valuable in INR?
This matters especially when your account, payout or trading results are measured in USD but your actual spending and financial goals are in INR.
What Is a Trading Return?
A trading return is the gain or loss produced by your actual trading activity, before considering what happened to the exchange rate.
For example, suppose you start with $10,000 and finish with $11,000. Your trading return is:
Trading return = ($11,000 – $10,000) ÷ $10,000 × 100 = 10%
The 10% result tells you how your trading capital performed in its original currency. It does not tell you what happened to the rupee value of that capital.
This distinction is useful because a strategy can produce the same USD return in two different years while the INR result looks very different.
What Is a Currency Return?
A currency return comes from the change in the exchange rate between the currency of your trading result and your home currency.
For an Indian trader dealing with USD, the relevant rate is commonly USD/INR. If USD/INR moves from ₹82 to ₹86, one US dollar is worth more rupees at the later rate.
That does not mean your trading strategy suddenly became better. Your foreign-currency result simply became more valuable when expressed in INR.
A basic currency return can be measured as:
Currency return = (Exit USD/INR ÷ Entry USD/INR – 1) × 100
Using ₹82 as the entry rate and ₹86 as the exit rate:
(86 ÷ 82 – 1) × 100 ≈ 4.88%
So, in this simplified example, the currency movement contributed roughly 4.88% to the INR value of the original dollar amount.
Why Mixing the Two Returns Can Be Misleading
Imagine an Indian trader starts with $10,000 when USD/INR is ₹82. The INR value of the starting amount is:
$10,000 × ₹82 = ₹8,20,000
After trading, the account grows to $11,000. At the same time, USD/INR rises to ₹86. The ending INR value becomes:
$11,000 × ₹86 = ₹9,46,000
The rupee value increased by ₹1,26,000.
If you simply look at the INR numbers, you might conclude that the trader generated a return of about 15.37%. But that number combines two different effects: the 10% trading gain and the change in USD/INR.
The correct performance analysis should show both components instead of treating the entire INR increase as trading skill.
The Three Components of Your INR Return
There is a useful mathematical way to understand this.
Let:
- Trading return = Rt
- Currency return = Rc
Your combined INR return is:
Total INR return = (1 + Rt) × (1 + Rc) – 1
When expanded:
Total INR return = Rt + Rc + (Rt × Rc)
The final term is the interaction between trading performance and currency movement.
For the example above:
- Trading return = 10%
- Currency return = approximately 4.88%
- Interaction = approximately 0.49%
That gives a combined INR return of roughly 15.37%.
This is why adding the two percentages mechanically is not always mathematically exact. The currency movement applies to the changing foreign-currency balance as well.
Trading Profit Can Be Positive While INR Performance Is Weak
The same principle works in reverse.
Suppose you make a 10% return in USD, but USD/INR falls during the period. The dollar profit may still be positive, but the INR value of the result can be lower than you expected.
This is particularly important for Indian traders who evaluate their wealth in rupees. A profitable USD trading account does not automatically mean the same percentage gain in INR.
For this reason, keep two performance columns in your records:
- Return in the account currency
- Return after conversion into INR
That simple change can prevent a lot of confusion.
How Prop Firm Traders Should Think About It
Prop firm traders can also use this framework when their payouts are denominated in USD or another foreign currency.
Suppose a prop firm approves a $1,000 payout. Your trading-related result is $1,000. But the amount that ultimately matters for your Indian household budget is the INR value received after the applicable conversion rate and any relevant charges.
If USD/INR changes between the time you assess the payout and the time the funds are converted, the rupee value can change even though the approved USD payout has not changed.
That is why it is useful to keep payout amount, conversion rate, and final INR credit as separate fields in your records.
For more on the conversion side, see our guide on how foreign currency conversion fees can reduce trading withdrawals in India.
Do Not Confuse Currency Gains With Better Trading
This is one of the most important reasons to separate the two returns.
Imagine two traders both generate a 10% USD return. Trader A sees a large increase in INR value because the rupee weakens. Trader B trades during a period when the rupee strengthens.
Their trading performance is identical in the account currency, but their INR results are different.
If they compare only the INR outcome, Trader A may appear to have performed better. That conclusion would be incomplete.
A serious performance review should therefore ask:
- How much did the trading strategy make in USD?
- How much did USD/INR contribute?
- Were conversion costs deducted?
- What amount actually reached the Indian bank account?
A Simple Spreadsheet for Indian Traders
You do not need complicated accounting software to track this. A spreadsheet is enough.
| Field | Example |
|---|---|
| Starting balance | $10,000 |
| Ending balance | $11,000 |
| Trading return | 10% |
| Entry USD/INR | ₹82 |
| Exit USD/INR | ₹86 |
| Currency return | ~4.88% |
| Starting INR value | ₹8,20,000 |
| Ending INR value | ₹9,46,000 |
| Total INR return | ~15.37% |
For actual withdrawals, add another section for conversion fees, bank charges, intermediary charges and the final INR amount credited. This gives you a much more realistic picture of what you actually received.
Our earlier guide on why small forex transactions can cost more to convert into INR explains why the headline exchange rate is not always the same rate reflected in the final amount.
Track Performance in Both USD and INR
For most Indian traders with foreign-currency results, there is no need to choose between USD and INR performance. Track both.
USD performance tells you whether your trading process is working.
INR performance tells you what that result means in your domestic currency.
Both are useful, but they answer different questions.
If your goal is to improve a trading strategy, focus heavily on the return, drawdown, risk and consistency in the account currency. If your goal is to understand purchasing power and household wealth in India, also monitor the INR value and currency effect.
What About INR Depreciation?
INR depreciation can increase the rupee value of an unchanged USD amount. That can be useful when you are measuring the INR value of foreign-currency assets or income, but it should not automatically be described as trading performance.
For a deeper calculation framework, read how Indian traders can calculate their real return after INR depreciation.
The key idea is simple: your trading strategy creates the foreign-currency return; the exchange rate changes the INR value of that result.
Common Mistakes Indian Traders Make
1. Counting USD/INR gains as trading profit
If your account balance increased because of trading, that is trading performance. If its INR value increased because USD/INR moved, that is a currency effect. Keep them separate.
2. Using one exchange rate for the entire period
For performance measurement, the exchange rate at the beginning and end of the measurement period can matter. For actual withdrawals, the conversion rate and charges applied to the transaction matter more.
3. Ignoring conversion costs
A theoretical INR value is not necessarily the amount you receive. Conversion spreads and other transaction costs can reduce the final credit.
4. Comparing traders only by INR profit
Two traders can have the same USD return but different INR outcomes because they converted at different exchange rates. Compare the underlying trading return first.
5. Looking only at a single payout
Currency movements can distort one month’s INR result. Reviewing several months of USD performance alongside INR results gives you a cleaner picture.
A Better Way to Review Your Trading Performance
At the end of every month, record four numbers:
- Starting foreign-currency balance
- Ending foreign-currency balance
- Entry exchange rate
- Exit or actual conversion exchange rate
Then calculate the trading return separately and the INR return separately. If money was actually withdrawn, record the final bank credit as another number.
This creates three useful layers of analysis:
Trading result → Currency-adjusted result → Actual INR received
That is far more informative than looking at a single profit figure on a trading dashboard.
Final Takeaway
Indian traders should separate trading returns from currency returns because they come from different sources.
Your trading strategy determines how much you make or lose in the account currency. USD/INR movements determine how that foreign-currency result changes when measured in rupees. Conversion costs then determine how much you may actually receive after a withdrawal.
Once these three layers are tracked separately, your performance analysis becomes much cleaner. You can identify whether your results came from better trading, currency movement, or both.
Do not let a favourable USD/INR move make an average trading month look exceptional, and do not let an unfavourable currency move make a good trading strategy look worse than it really is.
Disclaimer: This article is for educational and informational purposes only. Exchange rates, conversion methods, fees and the treatment of trading or foreign-currency income can vary by provider and individual circumstances. Verify applicable financial, tax and regulatory requirements with the relevant official sources or a qualified professional.
[…] For a deeper explanation, see Why Indian Traders Should Separate Trading Returns From Currency Returns. […]
[…] currency movement is different from a bank fee. TradeOG’s article on separating trading returns from currency returns explains why Indian traders should keep these two effects […]