

Whether a prop firm breach is determined by equity or balance depends entirely on the firm’s specific drawdown methodology. Most modern prop firms calculate daily loss limits and maximum drawdown using real-time floating equity, meaning open unrealized losses can breach your account even if your closed balance appears completely safe. However, some rules rely on closed balance or end-of-day values. Always verify your firm’s exact formula.
What Is Account Balance?
In financial and proprietary trading, Account Balance represents the realized cash value of your account. It reflects the cumulative financial outcome of all closed trades, deposits, evaluation fees, refunds, and posted transaction debits.
Your balance changes only when an event is finalized:
- When you close an open position (crystallizing either a profit or a loss).
- When a direct administrative adjustment, overnight financing credit/debit, or fee settlement is posted to your ledger.
Crucially, balance does not reflect open market exposure. If you enter a 5-lot position on the German DAX (GER40) and price plunges 80 points against you, your account balance remains completely unchanged on your terminal interface until you manually close the position or your stop-loss order fills. Relying solely on account balance creates a delayed, backward-looking representation of your trading solvency.
What Is Account Equity?
Account Equity represents the live, real-time value of your account at any given millisecond. It measures your true financial standing if every single active position on your account were liquidated at current market prices.
The standard accounting formula for equity across MetaTrader 4, MetaTrader 5, cTrader, and proprietary web platforms is:
Equity = Account Balance + Floating Unrealized P/L ± Overnight Swaps − Open Commissions
For example, if your closed account balance is $100,000, but you are currently holding an open trade with an unrealized floating loss of -$2,000, your live mark-to-market equity is $98,000 (before factoring in ticket commissions or rollover financing fees). Because trading servers continuously poll pricing feeds from liquidity providers, equity fluctuates with every tick of the market.
Equity vs. Balance — Simple Numerical Comparison
To visualize how balance and equity diverge during live market conditions, examine this comparison matrix for a $100,000 evaluation account:
| Trading Situation | Account Balance | Floating P/L | Account Equity | Solvency Status |
|---|---|---|---|---|
| Flat (No Open Positions) | $100,000 | $0 | $100,000 | 100% Capital Available |
| Open Profitable Trade | $100,000 | +$1,000 | $101,000 | Drawdown Cushion Expanded |
| Open Losing Trade | $100,000 | -$2,000 | $98,000 | Drawdown Buffer Contracted |
| Closed Trade After Loss | $98,000 | $0 | $98,000 | Balance Equalizes with Equity |
Notice that as long as trades remain open, balance and equity tell two entirely different stories. While your balance rests at a stable $100,000, your real-time risk profile is dictated entirely by the $98,000 equity figure.
Which One Determines a Prop Firm Breach?
This is the most critical question in prop trading risk management. The answer: there is no universal industry rule.
Proprietary trading firms design their risk engines using distinct architectural models. A single firm may even apply different calculation standards to different rules within the same evaluation program. Depending on your contract, your breach limits may be determined by:
- Intraday Equity Monitoring: The server evaluates live equity on every single price tick. If open floating losses drag equity below the threshold for a fraction of a second, the account is terminated instantly.
- Closed Balance Monitoring: The server only registers breaches when positions are closed and realized losses are booked.
- End-of-Day (EOD) Equity: The server checks equity only once per 24 hours at the daily market close (typically 5:00 PM EST). Intraday floating dips that recover before the settlement bell do not breach the account.
- End-of-Day (EOD) Balance: The daily boundary is calculated strictly against the closed balance at the daily rollover reset.
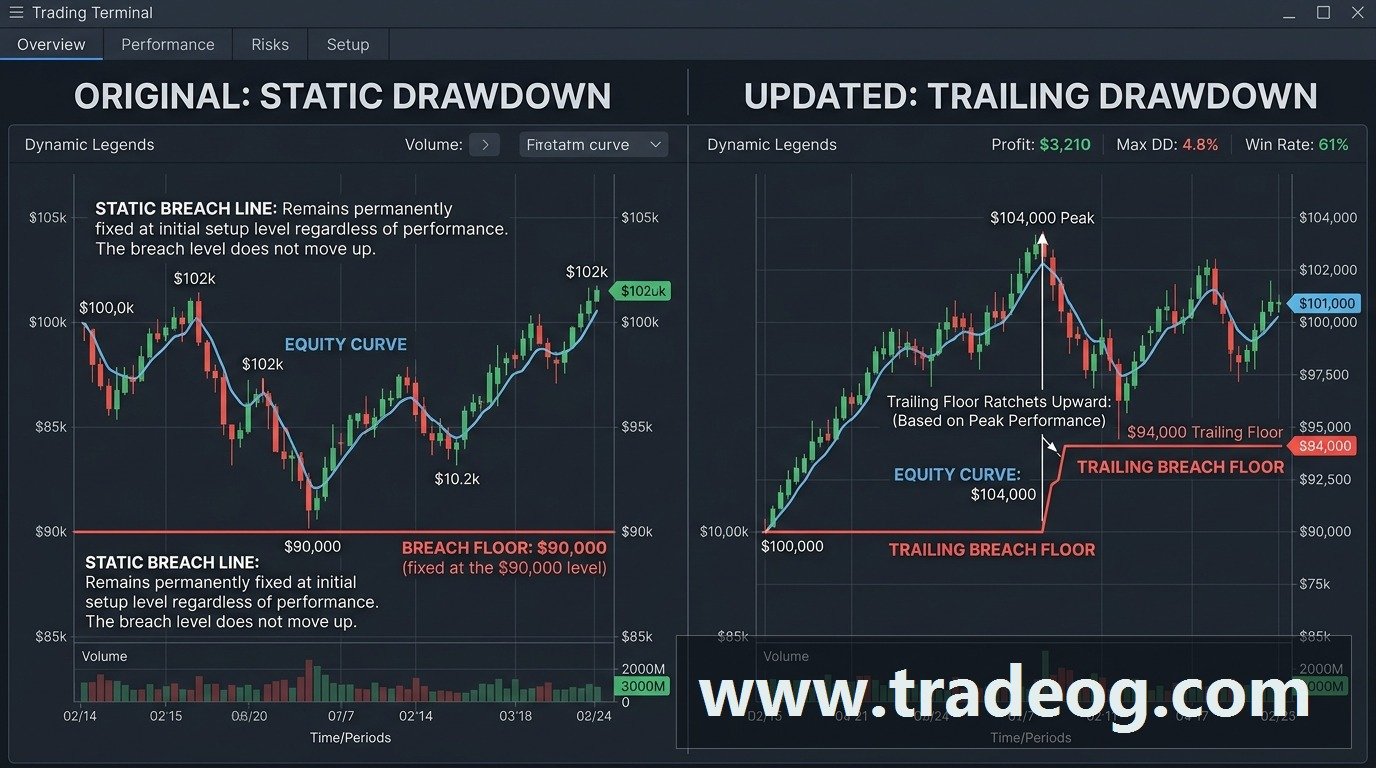
- Static Drawdown vs. Trailing High-Water Mark: Static models fix the breach line below initial capital, whereas trailing models ratchet the liquidation line upward as equity or balance hits new peaks.
Because these methodologies vary drastically across providers, assuming that all firms use balance—or that all firms use equity—is the single most common cause of premature challenge failure.
How an Equity-Based Breach Works
The vast majority of top-tier CFD prop firms utilize equity-based risk engines to monitor both Maximum Daily Loss and overall Maximum Loss. Understanding this mechanism is vital to survival.
The Real-Time Liquidation Trap
Consider an active trader on a $100,000 challenge account with a strict 5% ($5,000) Maximum Daily Loss rule:
- Day’s Starting Balance & Equity: $100,000
- Contractual Liquidation Threshold: $95,000
- Trade Action: The trader enters a 6-lot buy order on Nasdaq (NAS100).
- Market Volatility: The index experiences a sudden 90-point drop.
- Unrealized Floating Loss: -$5,200
- Live Account Equity: $100,000 − $5,200 = $94,800
- Account Balance: $100,000 (unchanged because the position is still open)
In an equity-based system, the server’s automated risk plugin detects that equity ($94,800) has fallen below the $95,000 daily floor. The risk daemon executes an immediate emergency command: it liquidates all open market tickets and revokes server access credentials.
Two minutes later, the market rebounds aggressively, and price surges past the original entry point. The trader looks at their terminal expecting a profit, only to find an automated breach notice: Account Terminated — Maximum Daily Drawdown Exceeded. The trader’s balance remained $100,000 right until the automated liquidation occurred, but the floating equity breach sealed their fate (learn the difference between temporary violations and permanent termination in our guide on prop firm soft breach vs hard breach).
How a Balance-Based Rule Works
In contrast to equity-based engines, a balance-based rule evaluates compliance exclusively using closed, realized trades. These models are more prevalent among legacy futures prop firms (such as certain CME/NYMEX prop programs) and select swing-trading evaluations.
Suppose you are trading under a pure balance-based daily loss model on an account with a $96,000 balance and a $95,000 daily loss floor:
- Current Balance: $96,000
- Open Floating Loss: -$1,500
- Live Account Equity: $94,500
- Breach Status: Compliant / Not Breached
Because the rule is balance-based, the -$1,500 floating loss does not trigger an intraday termination. If the position recovers and you close it for a -$400 loss, your new balance settles at $95,600—comfortably above the $95,000 threshold. However, if you close the trade while it is down -$1,500, your balance drops to $94,500, triggering an immediate balance breach.
Important Note: Do not assume balance-based rules are inherently safer. Prop firms that offer balance-based daily rules frequently offset this flexibility with strict intraday trailing maximum drawdown models or tighter position-sizing caps.
Why Floating Loss Matters
Retail traders often treat floating losses as theoretical paper figures, thinking: “It isn’t a loss until I close it.” In the proprietary trading industry, this mindset is fatal.
Floating loss represents immediate counterparty exposure. Prop firms must protect their capital pools or underlying liquidity agreements against catastrophic margin calls. Floating loss matters for several non-negotiable reasons:
- Continuous Risk Daemon Polling: Prop firm server plugins (such as Trade Monitor or MT5 Manager APIs) check account metrics hundreds of times per minute. Any millisecond breach of an equity floor is captured and logged.
- Stop-Loss Execution Latency: A stop-loss order is not an instantaneous guarantee of exit at your exact price. During high-volatility news releases, slippage can fill your stop-loss significantly deeper than expected, converting a safe floating loss into an account-killing realized balance loss.
- Spread Widening Drag: During the 5:00 PM EST daily rollover or high-impact economic data, bid-ask spreads can expand by 500% to 1,500%. A position sitting with a manageable floating loss of -$3,000 can instantaneously expand to -$4,500 due to spread widening, breaching an equity threshold without any underlying price trend. To understand how spreads trigger liquidation, explore can spread expansion cause a prop firm breach.
Can You Breach a Prop Firm While Your Balance Looks Safe?
Yes, absolutely. This is one of the most common reasons funded traders lose their accounts.
If your prop firm enforces an equity-based drawdown model, your closed account balance provides zero protection against floating market drawdowns. You can hold a pristine account balance of $100,000 with a clean record of closed winning trades, but if a single open trade floats down to $94,900 against a $95,000 daily drawdown threshold, your account is permanently breached. Moreover, even when staying within strict drawdown limits, brokers can monitor non-drawdown parameters; read our analysis on can a prop firm close your account without a drawdown breach.
When reviewing trade performance, never judge your safety by the balance header on your dashboard. Your true operational margin is always measured by the lowest tick of live equity.
Daily Loss vs. Maximum Drawdown: How Metrics Diverge
A frequent point of confusion among traders is assuming that a prop firm uses the same metric for both its daily limit and its overall account limit. In practice, firms frequently combine different calculation models:
| Risk Metric | What It Measures | Common Calculation Metric | Reset Frequency |
|---|---|---|---|
| Maximum Daily Loss | Permitted loss within a single 24-hour server cycle. | Equity-based (starting day balance − live equity) | Resets daily at server midnight (e.g. 00:00 CE(S)T). |
| Maximum Drawdown (Static) | Overall total loss limit across the entire life of the challenge. | Balance-based or Static Equity below initial capital | Never resets; remains fixed at initial floor. |
| Maximum Drawdown (Trailing) | Overall total loss limit trailing behind account equity peaks. | Intraday Equity or EOD Balance high-water mark | Trails upward dynamically as performance rises. |
For example, a firm might calculate your overall Maximum Drawdown statically using closed balance (giving you breathing room on multi-day swings), while strictly evaluating your Maximum Daily Loss using tick-by-tick equity. Failing to distinguish between these two separate rules is a primary source of rule violations.
Static vs. Trailing Drawdown
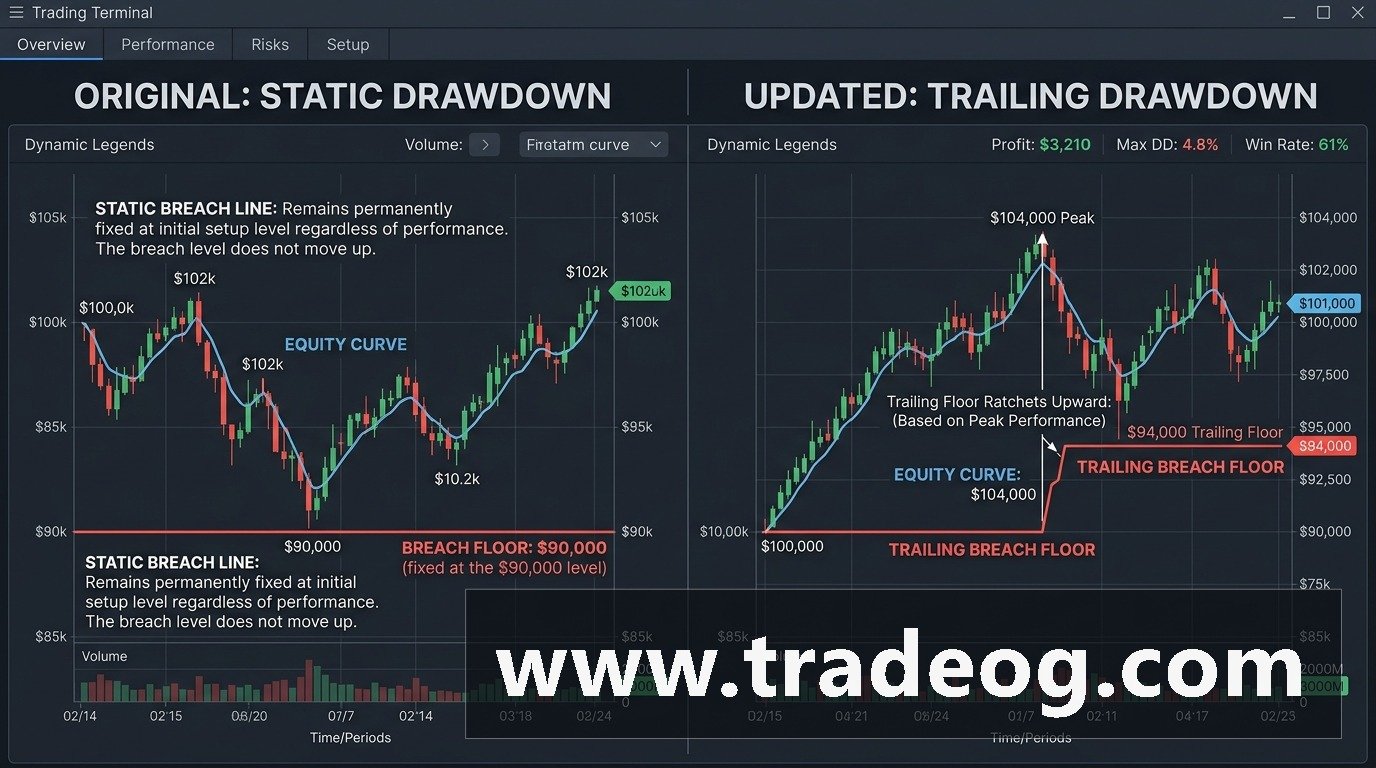
The distinction between equity and balance becomes even more critical when analyzing static versus trailing drawdown structures.
Static Drawdown
In a static drawdown model, your maximum allowable loss is anchored permanently to your initial starting balance. On a $100,000 account with a 10% ($10,000) static limit, your breach line remains fixed at $90,000 forever. If you grow the account to $112,000, your buffer expands from $10,000 to $22,000. Under static rules, both balance and equity fluctuations become easier to manage as profits accumulate.
Trailing Drawdown
In a trailing drawdown model, your liquidation floor moves upward in lockstep with account performance. However, firms implement trailing rules in two fundamentally different ways:
- Balance-Based Trailing: The breach line trails only when you close trades in profit. Open, unrealized floating profits do not pull your floor upward.
- Equity-Based Trailing (Peak High-Water Mark): The breach line ratchets upward in real time as your open floating equity reaches new highs. If your $100,000 account floats up to $106,000 before retracing to $101,000, your trailing drawdown floor (under a 6% rule) climbed from $94,000 to $99,640. Your open retracement just consumed $5,000 of your $6,000 drawdown buffer before the position was even closed! If your provider updates its drawdown structure mid-challenge, review what happens when a prop firm changes drawdown rules.
Balance, Equity, Commission, Swap, and Spread
Execution costs and market frictions interact directly with your account metrics. If you trade high frequency or volume, examine our detailed study on does commission count toward prop firm drawdown. Here is how each factor influences equity and prop firm breach calculations:
| Market / Cost Factor | Does It Directly Affect Balance? | Does It Directly Affect Equity? | Can It Trigger a Prop Firm Breach? |
|---|---|---|---|
| Closed Trade P/L | Yes — instantly credited or debited. | Yes — directly adjusts baseline capital. | Yes — across all prop firm calculation models. |
| Floating Unrealized P/L | No — balance remains static while open. | Yes — updates continuously on every tick. | Yes — on all equity-based daily and trailing rules. |
| Trading Commission | Yes — debited upon ticket execution. | Yes — immediately lowers calculated equity. | Yes — when fees push equity past drawdown boundaries. |
| Overnight Swap Fee | Yes — debited at daily 17:00 EST rollover. | Yes — reduces mark-to-market equity. | Yes — can push overnight swing positions into breach. |
| Bid-Ask Spread | No — indirect execution markup. | Yes — trades open in immediate negative P/L. | Yes — rollover spread expansion directly cuts equity. |
| Order Slippage | Yes — realized upon order fill. | Yes — results in worse starting equity. | Yes — adverse slippage deepens total loss exposure. |
Prop Firm Equity Example: Factoring In Commission and Swap
Let us walk through a comprehensive, real-world calculation showing how small friction costs combine with market movement to pressure account equity:
- Starting Account Balance: $100,000
- Maximum Daily Loss Limit (5% Equity Rule): $5,000 (Floor: $95,000)
- Open Positions: 3 swing positions held across the 5:00 PM EST daily rollover.
- Unrealized Market Floating Loss: -$4,750
- Round-Trip Commissions Debited: -$120
- Accumulated Overnight Financing Swaps: -$80
- Spread Drag at Rollover: -$100
The Equity Calculation
$$\text{Live Equity} = \$100,000 – \$4,750 – \$120 – \$80 – \$100 = \mathbf{\$94,950}$$
While the pure market price movement (-\$4,750) remained inside the allowable \$5,000 cushion, the addition of \$120 in commissions, \$80 in overnight swaps, and \$100 in rollover spread widening pulled total equity down to \$94,950. The risk engine flags a breach of the \$95,000 floor, liquidates all positions, and disqualifies the trader. Factoring every cost into your risk model is the only way to avoid this scenario.
Why Traders Often Misread Their Prop Firm Dashboard
Even seasoned retail traders frequently misinterpret their prop firm dashboards. Platform design and cognitive biases contribute to this disconnect:
- Prominent Balance Typography: Most dashboard UIs display Account Balance in large, prominent green or white fonts at the top of the screen, while Floating Equity is relegated to a smaller, secondary sub-header. Traders naturally focus on the larger, more comforting number.
- Server Reset Disconnects: Daily loss limits reset according to the firm’s server timezone—typically 00:00 CE(S)T (Prague/Berlin) or 5:00 PM EST (New York). A trader calculating daily loss based on their local time in London, Tokyo, or California can misjudge when their daily loss allowance resets.
- Hidden High-Water Marks: In trailing equity accounts, dashboards frequently fail to display a live line showing where the trailing stop currently sits. If you fail to track the highest peak equity reached during the day, you will not know your exact breach floor.
- Terminal vs. Dashboard Latency: There is often a 5 to 30 second polling delay between your MetaTrader/cTrader terminal and the prop firm’s web dashboard. Watching a web dashboard during fast news volatility means you are looking at outdated risk metrics.
12-Step Checklist: How to Check What Determines Your Prop Firm Breach
Before executing your first trade on any challenge or funded account, verify every parameter on this pre-trade risk checklist:
- Access the Official Rulebook: Navigate directly to the prop firm’s official knowledge base or FAQ documentation.
- Locate Maximum Daily Loss: Identify the exact percentage and read the formal formula used to calculate it.
- Search for “Equity”: Check whether the daily loss rule explicitly specifies “based on starting day balance” or “based on starting day equity.”
- Search for “Balance”: Determine whether closed balance is used for daily reset benchmarks.
- Verify Floating Loss Treatment: Confirm whether open, unrealized trade losses count toward daily and overall limits.
- Inspect Commission Rules: Check whether per-lot commissions are debited immediately from live equity.
- Review Overnight Swap Policies: Determine whether overnight holding swap debits are included in daily loss evaluations.
- Check Spread and Rollover Warnings: Confirm whether the firm issues specific warnings regarding spread widening at 5:00 PM EST.
- Identify the Server Timezone: Note the exact platform clock (e.g. 00:00 CE(S)T or 17:00 EST) and calculate how it aligns with your local time.
- Confirm Drawdown Structure: Determine whether overall Maximum Drawdown is static, balance-based trailing, or equity high-water mark trailing.
- Identify Account-Specific Rules: Verify whether “Swing” and “Regular” accounts have different overnight holding and equity rules.
- Contact Live Support for Confirmation: If wording is ambiguous, open a support ticket asking: “Does your risk engine monitor daily drawdown using real-time floating equity or closed balance?” Save the written response.
12 Questions to Ask a Prop Firm About Equity vs. Balance
- Is Maximum Daily Loss calculated using real-time floating equity or closed account balance?
- If an open trade’s floating loss briefly touches the daily limit and recovers, does that trigger a hard breach?
- Is Maximum Drawdown calculated statically or does it trail behind account growth?
- If trailing drawdown is used, does it trail open peak equity or closed balance?
- Does your risk engine deduct commissions and swaps from calculated equity in real time?
- At what exact server time does the daily loss limit reset each day?
- Does the daily loss calculation benchmark against the starting day’s balance or the starting day’s equity?
- Are open floating profits locked into trailing drawdown calculations before the trade is closed?
- What liquidity feeds do your simulated servers use to determine Bid and Ask pricing during rollover?
- If a stop-loss order experiences negative slippage that breaches the daily limit, is that treated as a hard breach?
- Can I hold open swing positions overnight without swap fees pushing my account into a daily breach?
- Where is the official mathematical formula for your daily loss calculation published in your terms of service?
8 Common Mistakes Traders Make
- Watching Balance While Floating in the Red: Monitoring your closed balance while an open trade drops toward your liquidation line leaves you completely defenseless against automated terminations.
- Ignoring Overnight Rollover Spreads: Leaving open trades active through the 5:00 PM EST rollover window exposes fragile accounts to massive bid-ask widening that immediately pulls down equity.
- Assuming All Prop Firms Operate Identically: Switching from an EOD balance-based firm to an intraday equity-based firm without adjusting position sizing leads to immediate rule violations.
- Failing to Account for Commissions and Swaps: Sizing trades up to the absolute dollar limit of your drawdown cushion leaves zero buffer for transaction fees.
- Treating the Full Drawdown Limit as Operational Capital: Trying to risk 4.9% of a 5% daily limit guarantees that normal market noise or slippage will breach your account.
- Miscalculating Server Reset Times: Opening new trades an hour before the daily reset thinking it is already a “new day” compounds two sessions of risk into one.
- Confusing Daily Loss with Maximum Drawdown: Assuming that surviving the overall maximum drawdown means you are safe from daily loss limits (or vice versa).
- Holding Runners on Equity Trailing Accounts: Allowing a winning trade to retrace on an account with intraday equity trailing permanently shrinks your failure cushion.
How to Monitor Your Drawdown Correctly
Professional risk management requires proactive operational controls rather than passive hoping. Follow these guidelines to safeguard your funded status:
- Track Live Equity Exclusively: Configure your trading terminal to keep the Equity and Margin columns permanently visible. Base all risk decisions strictly on your live equity figure.
- Build a 20% Operational Safety Buffer: Never trade up to the contractual limit. If your daily loss limit is $5,000, establish a hard personal rule to cease trading when daily equity decline reaches $4,000. That $1,000 buffer absorbs unexpected slippage, commissions, and spread widening.
- Set Local Alarms for Daily Reset: Place a recurring alarm on your phone 15 minutes before the firm’s daily server reset. Flatten high-leverage day trades before the reset window begins.
- Keep the Official Rulebook Bookmarked: Regularly check your prop firm’s announcement channels for policy revisions, liquidity provider changes, or platform maintenance updates.
Real-World Prop Firm Rule Examples
To demonstrate how leading proprietary trading firms approach this distinction, consider documented policy frameworks from established providers:
Example: FTMO Official Documentation
According to FTMO’s officially published trading objectives documentation, the Maximum Daily Loss calculation is explicitly formulated as:
Current Daily Loss = Initial Day Balance − Current Equity
Where Current Equity = Balance + Open Positions P/L ± Swaps − Commissions
FTMO’s documented formula confirms that daily loss is evaluated continuously against live equity. If open unrealized losses, swaps, or commissions exceed the allowable threshold at any second during the server day, the account is terminated. FTMO also stipulates that if an account starts the day in profit, the daily loss limit benchmarks against whichever is higher between starting balance and starting equity.
Example: Legacy Futures Prop Firms (EOD Models)
Certain futures prop platforms (such as specific CME evaluation combines) utilize End-of-Day (EOD) balance or EOD equity tracking. Under pure EOD rules, intraday floating drawdowns do not trigger liquidations as long as account equity recovers before the daily 5:00 PM EST exchange settlement. However, these programs frequently enforce strict position-size volume caps and trailing drawdown floors.
Notice: These examples illustrate documented institutional models and do not constitute an endorsement or ranking of any specific firm.
Equity vs. Balance Calculator: Conceptual Framework
To calculate your true remaining drawdown cushion before placing an order, apply this mathematical model:
Effective Drawdown Cushion = Current Live Equity − Contractual Liquidation Floor − Estimated Trade Costs
Practical Calculator Walkthrough
- Starting Day Balance: $100,000
- Maximum Daily Loss Limit (5%): $5,000 (Liquidation Floor: $95,000)
- Current Closed Balance: $98,500
- Open Floating Trade P/L: -$1,200
- Current Live Equity: $98,500 − $1,200 = $97,300
- Planned New Order: 2 lots EUR/USD ($14 round-trip commission + approx. $12 entry spread)
$$\text{Effective Cushion} = \$97,300 – \$95,000 – \$14 – \$12 = \mathbf{\$2,274}$$
While a trader looking at their closed balance ($98,500) might believe they have $3,500 of room remaining ($98,500 − $95,000), their true operational cushion is only $2,274. Respecting this calculation prevents unexpected automated breaches. If you suffer a setback and need to rebuild your balance, consult our breakdown on drawdown recovery and how much profit is needed after a loss.
Frequently Asked Questions (FAQ)
What is the difference between balance and equity?
Balance is the realized cash value of your account resulting from closed trades and posted transactions. Equity is the real-time mark-to-market value of your account, calculating your closed balance plus or minus open floating profits, losses, swaps, and commissions.
Do prop firms use equity or balance for drawdown?
Most modern CFD prop firms use real-time floating equity to evaluate both Maximum Daily Loss and Maximum Drawdown. However, specific firms or futures evaluation programs may use closed balance, end-of-day balance, or trailing high-water marks. You must verify each firm’s specific terms.
Can floating loss cause a prop firm breach?
Yes. If your prop firm monitors daily loss or maximum drawdown using equity, an open floating loss that touches or exceeds the allowed threshold will trigger an immediate account termination, even if you never close the position.
Can I breach while my balance is still above the limit?
Yes. If your closed balance is $100,000 and your daily loss limit is $5,000 (floor: $95,000), an open trade with a floating loss of -$5,200 pulls equity down to $94,800. In an equity-based system, your account breaches immediately despite your $100,000 balance.
Does equity include open trades?
Yes. By definition, equity continuously incorporates the unrealized profit or loss of all open market positions, updating on every price tick from your broker’s liquidity feed.
Does commission affect prop firm equity?
Yes. When you open a trade, per-lot commissions are debited directly, immediately reducing your calculated equity and contracting your available drawdown runway.
Does swap affect prop firm equity?
Yes. Overnight financing (swap fees) debited at the 5:00 PM EST rollover directly lowers your account equity. Large negative swaps on swing trades can push an account into a daily breach.
Does spread affect prop firm drawdown?
Yes. Because positions open at the opposite side of the Bid-Ask spread, every new order begins in an immediate floating loss. During illiquid hours, spread expansion directly cuts into your equity buffer.
What is the difference between daily loss and maximum drawdown?
Maximum Daily Loss restricts how much capital you can lose within a single 24-hour server day, resetting each midnight. Maximum Drawdown restricts the total cumulative loss allowed across the entire life of your challenge.
What is trailing drawdown?
Trailing drawdown is a risk model where your maximum loss threshold ratchets upward as your account achieves new high-water mark peaks in equity or balance, permanently locking the failure line higher.
How can I check my prop firm’s drawdown calculation?
Review the firm’s official help center FAQ under “Drawdown Rules,” search specifically for the terms “equity” and “balance,” inspect their daily loss formula, and confirm details with live customer support.
[…] For a complete breakdown of this topic, see our guide on prop firm equity vs balance and which one determines your breach. […]
[…] Conversely, if you carry a negative floating trade across the reset, that floating loss may immediately consume a large portion of your brand-new day’s buffer. To understand how firms evaluate live positions against cash figures, read our guide on prop firm equity vs balance: which one determines your breach. […]
[…] blowout. To understand how live equity fluctuations impact accounts, read our complete guide on equity vs balance and examine how spread expansion and drawdown […]
[…] If the firm enforces a $5,000 daily loss floor based on starting equity ($95,000 floor), this account is only $1,500 away from permanent termination, despite the terminal balance showing zero realized loss. In proprietary trading, equity determines survival. Review our foundational study on equity vs balance. […]
[…] Maximum Drawdown: Static balance drawdown vs trailing equity drawdown. Read Prop Firm Equity vs Balance: Which One Determines Your Breach?. […]
[…] Drawdown Buffer and Calculation Method: Firms offering a generous 10% static drawdown often price higher than firms using a trailing drawdown or tighter 6% to 8% loss limits. For a complete comparison of how drawdown is tracked, review Prop Firm Equity vs Balance: Which One Determines Your Breach?. […]
[…] If the firm calculates the daily limit based strictly on realized and floating losses, the $5,200 actual loss exceeds the $5,000 limit. The account will breach. The exact calculation methodology (e.g., whether it uses starting balance or starting equity) is highly firm-specific, which is why monitoring real-time equity is vital. See our guide on prop firm equity vs balance: which one determines your breach. […]
[…] Because spread widening immediately degrades floating P/L, your equity will contract during low liquidity even while your displayed balance looks completely safe. Under modern prop firm rules, equity is almost universally the metric that determines daily drawdown breaches. Review our comprehensive study on prop firm equity vs balance. […]
[…] master the distinction between static cash figures and live equity tracking, read equity vs balance in prop firm drawdown and verify how timing affects your risk in prop firm server […]